You Traded More. Did You Actually Earn More?

Investing Mindset, Part 1: The first question is not "what was my return," it is "what was left after costs."
A portfolio returning 11.4% a year sounds like a win. It looks different if the market returned 17.9% over the same stretch. Making money and having a good reason to pick a particular method are not the same claim.

The missing comparison on your statement

Brad Barber and Terrance Odean studied 66,465 households at a US discount brokerage. From February 1991 to January 1997, the group that traded most often earned an annualized 11.4% after costs. The group that traded least often earned 18.5%. Before costs, the gap between the two groups was small. The extra activity did not pay for itself. source

These numbers should not be pasted onto today's investors without caveats. It is a single brokerage's sample from an earlier fee environment, and sorting households by trading frequency is not the same as labeling them "swing traders" and "long-term investors." Still, the underlying question holds up: does the extra trading earn back the extra cost it creates?

Comparison groupAnnualized return, after costs
Highest-trading-frequency group11.4%
Lowest-trading-frequency group18.5%

Both figures come from the same US household sample over the same observation window. They describe what happened, not what to expect going forward. source

The stock market as a whole is not a casino

William Sharpe's argument is more precise. Within the same market, the dollar-weighted average return of all active money, before costs, equals the market's return. Once that money pays more in costs, its average return after costs falls below the market's. This is not a claim that no individual investor can succeed. It is arithmetic: not everyone can beat the average at the same time. source

Breaking down the return an investor actually gets

01 Reward for being in the market 02 Extra performance from selection and timing 03 Minus trading and holding costs

Conceptual. The return the market itself pays and the competition for extra returns are two separate things.

There is no good reason to call the stock market as a whole, where companies earn profits and pay dividends, a negative-sum game. But in the separate contest of "who bought and sold better than everyone else," costs are a real drag. And costs do not only matter when a portfolio loses money. Even in a rising market, a trader can end up with less than a simpler alternative would have delivered.

Professionals are not exempt either

According to SPIVA, 67% of US large-cap active funds underperformed the S&P 500 in the first half of 2026. The same report found a lower miss rate for emerging-market equity funds, at 38%. Results varied by market and by period. This statistic does not measure how often individual technical traders fail, and it does not measure the odds that a fund loses money outright. source
Trading more is not proof of earning more.

Sungdong KimAuthor of the Korean book “The US Stock ETF Investing That Never Fails”. A long-term investor in U.S. stocks since 2019.

More by topic

Starting with this story's topics, then what readers are following now

Investor psychology, decision-making and books on investing

S&P 500

This story's topic12 storiesSee all →

The S&P 500 Looks Fine. So Why Do Most Stocks Hurt?

The index sits near its high, yet most of its members are down 20% to 30% or more from their own peaks. A look at the "stealth bear market" and the numbers long-term investors should watch.

Investing

Two Companies Drive 34% of S&P 500 Earnings Growth as AI Pays Sellers First

Nvidia and Micron generate a third of expected earnings growth in US large caps. Apollo says the financial effect of AI is not yet visible in the S&P 493.

Investing

Why Few Investors Profit From Stocks: A Handful of Winners and a Handful of Days

Owning good companies matters, but so does staying invested while they grow. The data suggest the obstacle is rarely information. It is the lack of a structure built in advance to hold up when markets shake.

Macro

Stocks Bounce, but the AI Selloff May Not Be Over: A Two-Week Playbook

The Dow rose more than 1% while the Nasdaq barely moved and semiconductors kept falling. A W-shaped retest looks more likely than a V, and the task now is surviving the next drop.

Investing

S&P 500 Slips 0.22%, but 73% of the Market Fell

Long-term yields above 5% weighed on small caps and semiconductors on Oct. 7. A strong 10-year Treasury auction and a few large tech names limited the index's losses.

Tech

This, Too, Shall Pass. But Investors Should Come Out Tougher

Selloffs will keep coming. Lower debt, less concentration and steady buying can make them easier to live with.

Investor Mind

A 36% Crash by 2027? The Real AI Risk Is Whether the Money Comes Back

Believing AI will change the world is not the same as believing AI stocks will keep rising. The 2027 crash call turns on one question: can investors recover what they are spending?

Investing

HBM

77 storiesSee all →

Memory stacked next to the GPU.

Memory Is Still Short, but Less Short: Checking for the Peak This Week

Citi trimmed its 2027 DRAM and NAND shortage forecasts together. Server pricing remains strong, while consumer markets show weakness. This week's numbers show where the memory boom may peak.

Investing

The Real ASML Number Isn't the 3% Pop, It's the 30% Capacity Hike

ASML's rally isn't just an AI trade. Customers are already locking in 2027 tool slots, and ASML is raising Low-NA EUV capacity by roughly 30% to keep up.

Investing

A 3x P/E is not a discount. It is a verdict on how long memory profits last

Nomura's buy case on Samsung Electronics and SK Hynix does not stop at higher memory prices. It argues that if AI has turned memory from a cyclical component into strategic infrastructure, the formula the market uses to value both companies has to change too.

Investing

2027 Isn't the End: Citi's Case for a Memory Supercycle Running to 2031

Citi says the memory shortage timeline is stretching again. If AI shifts from "train once" models to continual learning, HBM, server DRAM and enterprise SSDs could all fall short at the same time.

Tech

AI ran out of memory before it ran out of GPUs

The HBM bottleneck is spreading into DRAM prices, server costs and the price of the next laptop or phone.

Tech

Has Memory Peaked? Prices Are Cooling, but the Shortage Looks Set to Run to 2028

Price growth has slowed and consumer demand is already breaking. Server and HBM supply remains short, and Micron says more than 75% of its 2027 volume is already committed to customers.

Tech

AI Chip Peak Check: Demand Still Rising, Risk Building in 2027-2029 Supply and Funding

DRAM and NAND contract prices are still climbing and HBM suppliers hold the edge. Power shortages, AI financing costs and simultaneous memory expansion are the risks for later years.

Investing

A building that houses servers and networking gear and supplies them with powe…

Nvidia and Palantir Put AI Inside the Supply Chain - The Real Shift Is That It's Learning Judgment

A single Vera Rubin rack holds 1.3 million parts. The real breakthrough in Nvidia and Palantir's new supply chain AI isn't automating that complexity, it's capturing the judgment calls that used to live only in planners' heads.

Tech

Is Space Cooler for AI? Why Musk Wants Data Centers in Orbit

The next limit on AI may be power and cooling, not GPUs. Elon Musk is looking to Earth orbit for an answer, but the test is cost per hour of compute.

Tech

Musk Sees the Next Phase of AI Infrastructure: Who Can Switch GPUs On, Fast

If neoclouds struggle under financial pressure, AI demand may not shrink. It may simply favor the few operators with the capital and execution to serve it, a shift that could matter for SpaceX and Tesla.

Tech

White House Swaps AI for "SI." The Real Investment Signal Is Infrastructure, Not the Name

An executive order renames artificial intelligence "Super Intelligence" and six frontier labs sign a voluntary safety accord. What investors should watch is the data center, power, nuclear and chip policy now gathered under one national-competitiveness frame.

Tech

The Cheaper Tokens Get, the Bigger Your AI Bill Gets

As AI shifts from training to inference, the token is becoming an industrial commodity. Falling prices are not cutting demand, because agents and automation consume tokens at a scale no human chat session ever did.

Investing

Marvell's $115 Billion Lumentum Deal: Is AI's Next Bottleneck Light, Not Chips?

Marvell's purchase of Lumentum points to a contest beyond GPU speed, in data transfer and power efficiency. Whether the price is right is not yet confirmed.

Tech

Workers in hard hats beside a communications equipment cabin, with a Starship rocket on its launch tower at dusk in the background

SpaceX Forecast at About $730 Billion in 2028 Revenue: The Bigger Opportunity Musk Sees

Sequoia Capital made a bold forecast, and Elon Musk replied, "I think we can do better." The future SpaceX is looking at is far bigger than the rocket launch business. The plan is to link satellite communications, AI data centers and orbital computing into one giant business.

TechEXPLAIN

NVDA

96 storiesSee all →

Who Hits $1 Trillion Next: Reading AMD and ASML by Different Rules

One company is chasing Nvidia's GPU empire. The other sells the machine that draws the chips for every advanced chipmaker, including Nvidia. Both get floated as 2028 trillion-dollar candidates, but the numbers investors need to watch are entirely different.

Investing

China's AI Labs Went Open Source Because They Had to, Not Because They Wanted To
A GPU shortfall pushed Chinese AI labs toward efficiency and open weights, and that constraint is now reshaping the global competition over who controls AI's basic infrastructure.

Tech

Box Shows AI Its Manuals, and the AI Starts Redesigning the Workflow

Box Architect, built with NVIDIA, moves AI from reading documents to designing how work gets done. It has not yet reached beta, so the real-world payoff remains to be seen.

Tech

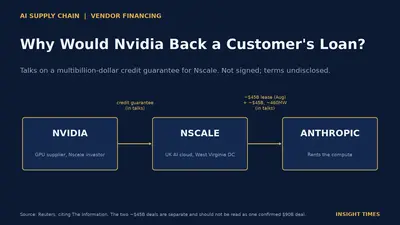
Dark navy cover. Flow diagram: Nvidia to Nscale (credit guarantee, in talks) to Anthropic (~$45B compute lease signed in August plus a separate ~$45B, ~460MW deal in talks). Title: Why Would Nvidia Back a Customer's Loan?

Why Would Nvidia Guarantee Its Customers' Data Center Loans?

Nvidia is reportedly in talks to back financing for Nscale's West Virginia data center. Nothing is signed, and the terms are not public.

Tech

Before Robots Sell, Chips Sell First: Following the Money in the Humanoid Race
Billions of dollars are moving before humanoid robots reach mass sales. Compute suppliers may see revenue first, but that does not guarantee stock returns.

Tech

Tech Selloff: Is the Bull Market Over? Wall Street's Four-Year Chart Says Not Yet

The uptrend has survived five double-digit pullbacks in four years. This time, AI companies' debt and cash flow are the new variables.

Investing

The AI Bubble Question Has Changed: By Late 2026, It's ROIC Over GPUs

There is no sign yet that AI investment is slowing. If anything, hyperscaler spending forecasts keep climbing. But as the scale of that capital has grown, the market's question has shifted from "is AI growing" to "when, and how much, does this capital come back as cash."

Tech