Brent at $109, the 10-year at 4.94%: the discount rate is beating the AI trade

Stocks fell for a fourth straight session on Sept. 10 as producer prices and energy costs pushed long yields toward 5%. After the close, Oracle showed AI demand is converting into signed contracts. The question is no longer demand. It is what multiple the market can pay for it.
Photo Nils Huenerfuerst · CC0 · Wikimedia Commons

The market repriced the cost of money, not earnings

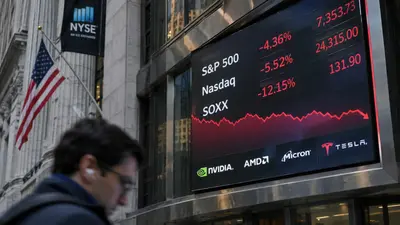
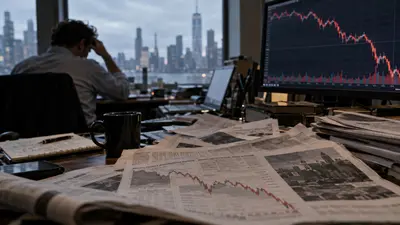
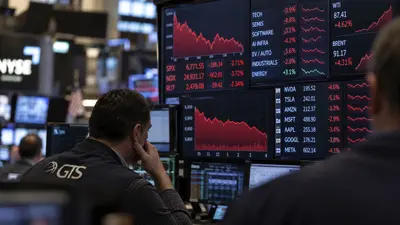
The problem with Sept. 10 was not the size of the decline. It was the persistence of the direction. The S&P 500 fell for a fourth consecutive session, and the Russell 2000 dropped the most of the four major indexes. When small and mid caps, the names most exposed to long yields and funding costs, sell off alongside megacap tech, this stops looking like a valuation adjustment confined to a handful of large stocks.

The immediate pressure came from prices and energy. The August producer price index rose 0.4% on the month and 5.4% from a year earlier. The monthly figure matched expectations, but the annual rate ticked back up from July, and energy prices jumped 4.2% over the month. The market priced the risk that expensive oil slows the disinflation path before it priced any expectation that prices resume falling.

Higher oil, higher inflation expectations, selling in long Treasuries, a higher 10-year yield, a lower present value of future earnings, compressed multiples across AI, semis and software.

The 10-year traded around 4.94% and touched roughly 4.95% intraday. At this level, the number itself matters less than whether the trend keeps grinding toward 5%. Another leg higher in long rates means the fastest-growing companies get the steepest discount rate. That is why fair value falls even when the earnings estimates do not move.

The whole AI supply chain fell together, and that is the clue

Nvidia and the rest of the semiconductor and AI infrastructure complex were weak. But reading that as a demand signal requires more evidence than one session provides. When design, foundry, memory and server names are all pressured on the same day, the cleaner explanation is not a broad drop in orders. It is that the multiple on the entire theme reset to the level of rates.

That means the recovery condition is more likely to show up in the bond market than in a company press release. If the 10-year drops back below 4.9% quickly, AI and software get room to bounce. If it settles above 4.95% and creeps toward 5%, the ceiling on valuations comes down for good businesses and bad ones alike.

Apple +3.56%: the market paid only for certainty

Apple closed at $326.57, up 3.56%. Alphabet gained 0.61% and Microsoft added 0.16%, while Meta fell 1.42% and Amazon slipped 0.20%. This was not an indiscriminate liquidation of tech.

Apple's strength shows that even in a rising-rate tape, money stays with names that have a visible product event and visible earnings. It is harder to call that a return of risk appetite. The real change comes when the Apple pattern spreads to the rest of megacap tech and to semiconductors.

Then, after the bell, Oracle posted very different numbers

Oracle reported fiscal 2027 first-quarter non-GAAP EPS of $1.92 on revenue of $19.3 billion. Total cloud revenue rose 62% to $11.6 billion, and OCI, the core of the story, grew 121% to $7.4 billion. The more important line is RPO, the remaining performance obligations that have been contracted but not yet recognized as revenue. RPO reached $664 billion, up $209 billion from a year earlier.

That is a stronger statement than a forecast that AI data center demand will hold up. It means customer demand for AI compute has already converted into contracts and backlog. Oracle guided fiscal 2027 revenue to at least $90 billion. For anyone arguing the AI infrastructure investment cycle has rolled over, this is an inconvenient print.

It supports the case for sustained GPU demand at Nvidia, leading-edge volume at TSMC, networking and custom accelerators at Broadcom and Marvell, and server and rack integration at Dell and Supermicro. It points the same direction for memory and enterprise SSDs.

Good news comes with a bill. Oracle is spending heavily to expand data center capacity. According to Reuters, capital expenditure in the quarter reached $28.5 billion. AI demand is being confirmed in contracts, and at the same time the capital required to turn that demand into revenue and cash flow is getting larger.

What to watch

The 10-year yield. A settled range above 4.95% and a move toward 5% signals further multiple compression in AI, semis and software. A quick return below 4.9% is the first condition for a tech rebound.

Crude. Above $110, energy-driven inflation and the pressure on the Fed both build. Long rates will not stabilize until oil does.

Breadth in the AI complex. Does Oracle rally alone, or do Nvidia, TSMC, Broadcom, Dell and Supermicro move with it? The second case would mean the demand signal is starting to beat the macro pressure.

CPI. With PPI and expensive oil already in hand, the consumer print is the next test. If long-rate volatility stays high into the meeting, high-multiple names keep facing position-cutting pressure.

Megacap breadth. Watch whether only Apple, with its product event, holds up, or whether buying widens across big tech as rates settle.

FAQ

Does Oracle's quarter mean the AI trade is back? No. Oracle confirms the strength of demand, but a discount rate is applied to the stock at the same time. If long rates keep rising, even good results will show up only partially in the share price.

Was the semiconductor selloff a demand warning? It is too early to say that from this data. The entire supply chain fell at once, and on the same day Oracle's OCI growth and RPO confirmed strong AI demand. Multiple compression explains the tape better than demand destruction.

Why does the Russell 2000 matter here? Small and mid caps are more sensitive to borrowing costs and domestic financial conditions. When the Russell underperforms large caps, the market is worrying about financial conditions broadly, not one sector.

What would change the read? If oil rolls over quickly and the 10-year drops below 4.9% but the AI supply chain stays weak, the issue is no longer the discount rate. At that point, look again at earnings estimates, the quality of the order book, and whether the capex is earning its return.

AI demand is confirmed in contracts, but the price of those contracts is set by the 10-year yield.

Insight Times Editorial Desk

More by topic

Starting with this story's topics, then what readers are following now

Investor psychology, decision-making and books on investing

Data Centers

This story's topic99 storiesSee all →

A building that houses servers and networking gear and supplies them with powe…

Nvidia and Palantir Put AI Inside the Supply Chain - The Real Shift Is That It's Learning Judgment

A single Vera Rubin rack holds 1.3 million parts. The real breakthrough in Nvidia and Palantir's new supply chain AI isn't automating that complexity, it's capturing the judgment calls that used to live only in planners' heads.

Tech

Why the White House Swapped "AI" for "Super Intelligence"

Executive Order 14434 renames AI across the federal government without defining a new technology. The real story is about roughly $700 billion in capex, free cash flow and electricity.

Tech

US AI Data Centers Are Headed for 90GW. Gigawatts Now Matter More Than Dollars

Goldman Sachs expects US data center capacity to grow from 64GW at the end of 2026 to 90GW at the end of 2027. The AI race is moving from buying GPUs to building power plants and transmission lines alongside them.

Tech

2027 Investing Needs Alignment, Not Prediction

A new investing book argues the hard part was never picking the next winner. It's staying aligned with where value and bottlenecks are moving while keeping old human weaknesses in check.

Investor Mind

AMD Crossed $1 Trillion, and the Market Started Looking at CPUs Again

AMD's stock topped a $1 trillion market cap for the first time. The rally isn't just about being an Nvidia alternative. It reflects a reassessment of AMD as a full-stack AI infrastructure vendor, one that bundles CPUs, GPUs and networking, as AI shifts from chatbots to agents and reignites data center demand for CPUs.</deck> <parameter name="oneline">As AI moves from chatbots to agents, the market has started counting the CPU sitting next to the GPU again.

Tech

Why Nebius Is Keeping Some 2027 AI Capacity Off the Shelf

Nebius mixes long-term contracts, short-term premiums and auctions. Holding back capacity pays only if the servers stay busy, and it is not yet clear the pricing will last.

Tech

DeepSeek's $15 Billion Raise: Model Makers May Feel It Before Nvidia Does

China's DeepSeek is closing a round about twice its original target. For US investors, the question is less the size of the check than where the money goes and whose profits it could erode.

Tech

AAPL

This story's topic13 storiesSee all →

iPhone Duo's Three-Month Wait: Demand Surge or Supply Bottleneck?

Shipping dates slid to January 2027 within minutes of preorders opening. That is a strong start, but a sellout is not the same as a measure of demand.

Investing

Apple's $299 HomeView Is Unlikely to Move the Needle. The Services Math Might

Even 10 million units a year would add less than 1% to Apple's revenue. The real test is whether the smart display deepens iCloud+ and other recurring revenue.

Tech

Why the iPhone Fold's Crease Barely Shows in the Middle

Apple's foldable engineering makes sense once you think about bookshelves, matte wallpaper, and window screens. Apple didn't erase the crease. It tricked force, light, and the camera into hiding it.

Tech

AI's Next KPI Isn't Token Price. It's Cost Per Successful Task

Apple is cutting the cost of where inference happens, Anthropic is cutting the cost of running its models, and Snorkel AI shows money flowing into the data and evaluation layer that reduces failed attempts. All three point to one shift: AI competition is moving from bigger models to cheaper successful outcomes.

Tech

AI Was Supposed to Live in the Cloud. Apple Is Bringing It Back to the Desktop.

Four Mac Studios running a trillion-parameter model matters less than the economics behind it: heavy, repeated AI use can make owning compute cheaper than renting it by the token.

Tech

Apple's Real AI Bet Isn't a Chatbot. It's Siri Running Your Apps

Apple has stepped back from the race to build a smarter chatbot than ChatGPT. Instead it is building an "OS agent" that connects Mail, Photos, Calendar and hundreds of thousands of apps to actually finish tasks. 2026 is the first year that strategy gets tested as a product, not a keynote promise.

Tech

Why Great Stocks Like Apple, Amazon and Nvidia Fell 80% First

Long-term charts hide the fear that came before the gains. A big drawdown is no guarantee of future returns, and the test is whether the business case survives the fall.

Tech

10-Year Treasury Yield

This story's topic19 storiesSee all →

The interest the US government pays to borrow for ten years.

Gas Prices, Not Politics, Are Deciding This Midterm Market Story

Forecasts of a Republican defeat are not exaggerated. The House has tilted clearly toward Democrats, the Senate has moved from a toss-up to a slight Democratic edge, and Trump's net approval is the lowest of either term.

Macro

Oil at $110, 10-Year Yield at 5%: The Discount Rate on Growth Stocks Is Rising Again

Brent crude spiked to $109.97 intraday and the US 10-year Treasury yield tested the 5% threshold. What matters is not the numbers themselves but that oil-driven inflation fears are pushing bond yields higher across the globe at once.

Macro

Weekly Check: The AI Bull Market Isn't Over, It's Just Gotten Harder

A 5% 10-year yield, 470 gigawatts stacked up in Texas, Chinese DRAM, and whether data centers actually get switched on are starting to decide who wins the AI trade through 2027.

Tech

Why a Wobbly Yen Carry Trade Hits US AI Stocks First

It is not just dollar-yen at 160. Watch the US-Japan rate gap, yen direction, volatility, and US long-term rates together, because AI and high-valuation growth stocks get squeezed first when all four move at once.

Macro

The Question Markets Asked This Week: Who Controls the AI Bottleneck, Not Who Owns AI

The Fed hiked again and the 10-year topped 5 percent, but the center of the AI trade held. The market is no longer asking whether AI is growing, it is asking who controls memory, power and capital.

Tech

S&P 500 Slips 0.22%, but 73% of the Market Fell

Long-term yields above 5% weighed on small caps and semiconductors on Oct. 7. A strong 10-year Treasury auction and a few large tech names limited the index's losses.

Tech

10-Year Yield at 5.34%: The Problem Isn't a Missing Buyer, It's the Price

Washington and the AI industry are pulling in huge sums at once, and the bond market is demanding higher yields to absorb it. Equity investors now need to watch long-term rates, financing costs and AI payback alongside the Fed's next move.

Macro

Crude Oil Prices

This story's topic11 storiesSee all →

The price of crude.

It's Not Just Hormuz: Why the Middle East War Is Becoming a Fed Problem Again

The US-Iran ceasefire has already collapsed, and the risk no longer sits in the Gulf alone. With the Red Sea and Saudi Arabia's bypass pipeline now under threat too, an energy shock is spreading into prices, the Fed, and growth-stock valuations.

Macro

Tesla Semi Waited 9 Years. Now It's Rolling Off a Real Factory Line

The Tesla Semi, unveiled back in 2017, has finally reached full-scale production at a dedicated Nevada plant. The number investors should watch isn't the 50,000-unit annual capacity, though. It's what the truck actually saves per mile.

Tech

Why the Fed cannot cut: the triple lock of jobs, oil and AI

Inflation is not the only thing blocking a rate cut. A firm labour market, energy prices back on the rise, and an enormous AI investment cycle are each pushing up the floor under US interest rates by a different route.

Macro

Brent Hits $106, 10-Year Touches 5% as AI Buildout Pace Gets Questioned

The S&P 500 fell just 0.48% but the semiconductor index collapsed 5.9%, as oil, rates and a new debate over how fast AI capability should advance all hit the market on the same day.

Tech

Rate at 5%: How to Hold AI Stocks This Week - Oil and Cash Flow Are the Real Variables

The Fed raised rates for the first time in three years even as August core CPI cooled to 2.4%. The market's real question this week is not whether inflation has fallen, but whether an oil shock revives inflation expectations and long-term yields, and whether AI companies' profits can hold up under 5% rates.

Investing

Why AI Stocks Fall Whether Companies Spend More or Less

Tesla, Meta and Lam Research all fell on Oct. 22 despite solid results. The market may not be abandoning AI so much as asking whether the money comes back as cash.

Investing