Rate at 5%: How to Hold AI Stocks This Week - Oil and Cash Flow Are the Real Variables
The Fed raised rates for the first time in three years even as August core CPI cooled to 2.4%. The market's real question this week is not whether inflation has fallen, but whether an oil shock revives inflation expectations and long-term yields, and whether AI companies' profits can hold up under 5% rates.
What matters more than the index is what's happening underneath it
Last week brought the Fed's first rate hike in this cycle and the 10-year Treasury yield breaking above 5%, in the same week. And yet the S&P 500 finished the week nearly flat, the Nasdaq rose on a semiconductor rebound, and the Dow was weak. On the surface, that reads as "the market shrugged off the hike."
Underneath, it's more interesting. The market is not buying AI as a single trade anymore. Investors are starting to separate companies that sell the bottleneck, chips, memory, networking, from companies that have to fund massive data center buildouts. Inside the same AI cycle, the gap is widening between companies sitting on cash and companies that keep needing to raise more of it.
Why the Fed hiked while core inflation is falling
On September 16, the Fed unanimously raised its policy rate by 25 basis points to 3.75-4.00%, the first hike since July 2023. The more telling detail is the dot plot. Sixteen of eighteen officials saw at least one more hike this year as appropriate, and four of them penciled in two more.
The Fed's own projections carry a clear message. 2026 growth is put at 2.3%, unemployment at 4.1%. PCE inflation, meanwhile, was revised up to 3.7%, core PCE to 3.4%. In other words, the Fed is not hiking because of a downturn. Growth and investment are holding up; the hikes look aimed at stopping energy costs and inflation expectations from spreading further.
There's a distinction investors need to hold onto here. August core CPI at 2.4% is a real cooldown. Shelter costs slowed to 3.0% year over year. But energy rose 16.3%, gasoline 27.4%, heating oil 52.0%. The University of Michigan's one-year inflation expectations gauge climbed to 4.6%. For a central bank, that combination makes it hard to declare "core is down, we're done."
Key numbers:
- 2.4% - August core CPI, year over year. The body of inflation keeps cooling.
- 16.3% - August energy CPI, year over year. The question is whether this supply shock feeds back into inflation expectations.
- 4.6% - September preliminary one-year inflation expectations. Likely the number the Fed is least comfortable with.
This week, watch the 10-year and oil, not CPI
There's no CPI, jobs report or PCE release this week, none of the heavyweight macro data points. That means price discovery is more likely to come directly from the bond market and Middle East supply headlines than from scheduled economic data.
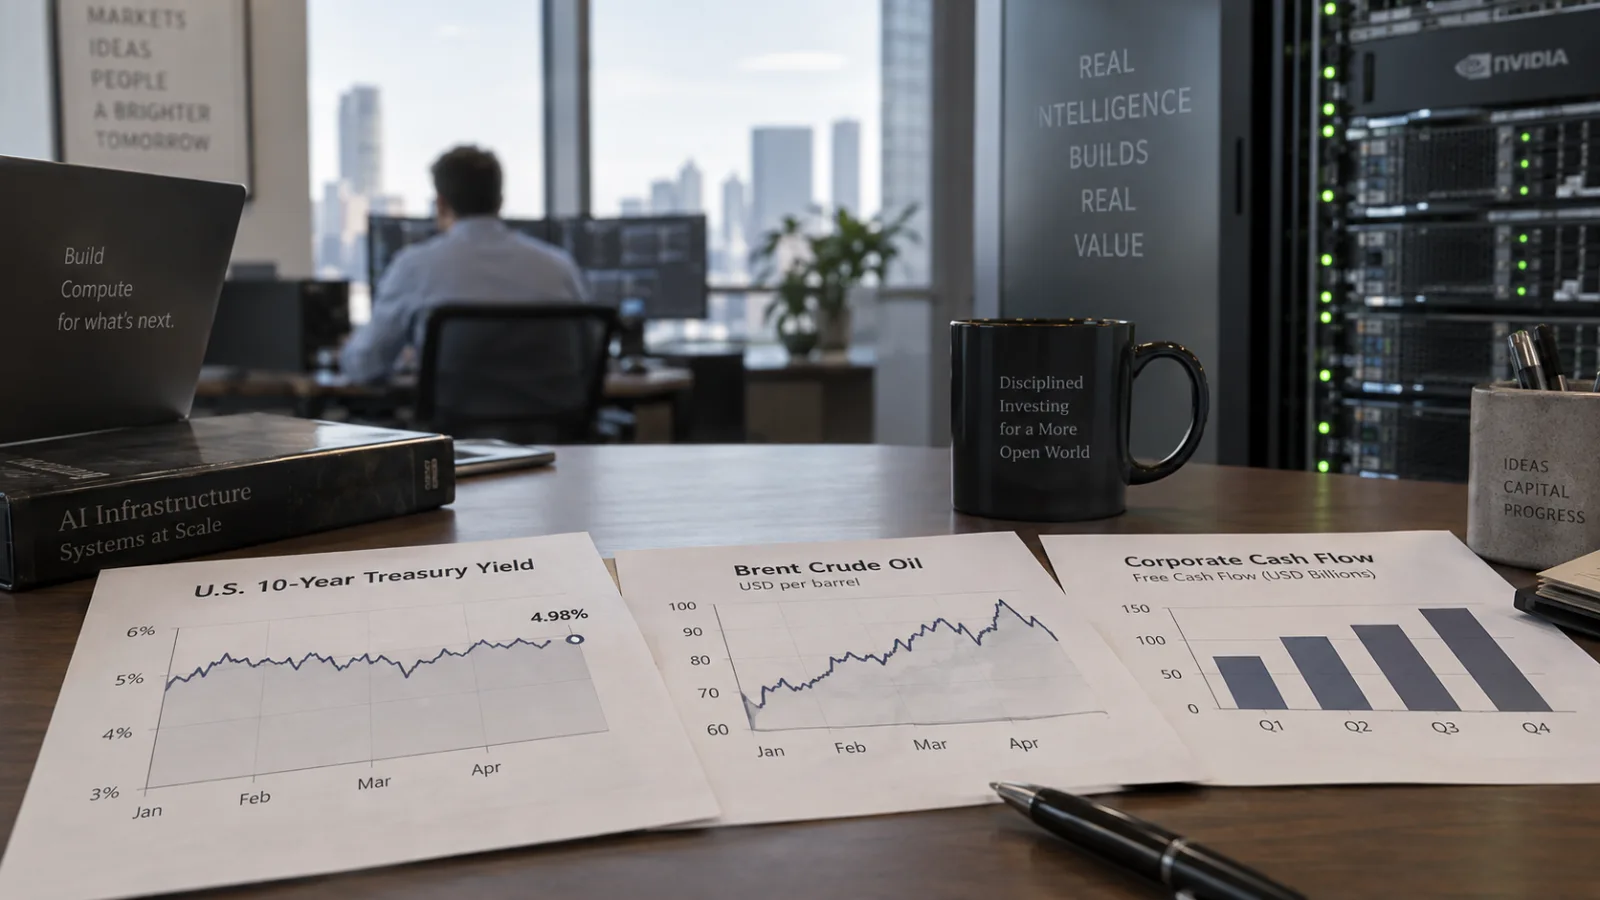
Oil matters here not because it directly saps chip demand. The transmission runs like this: higher oil prices, then higher inflation expectations, then expectations of more tightening, then a higher 10-year yield, then a higher discount rate for growth stocks. AI orders can stay intact and share prices can still fall.
So if a pullback hits this week, the first job is sorting out the cause. Are Nvidia, Micron and Broadcom orders and guidance actually weakening, or is the 10-year pushing back above 5% and compressing valuations on its own? Those are entirely different problems. If it's the former, earnings estimates need to come down. If it's the latter, the core assumptions behind the business haven't changed, only the price you're paying for it.
Thursday's Trump-Xi summit: chip investors only need to watch the wording
Donald Trump and Xi Jinping are set to meet in Washington on September 24. Reuters' reporting on the preliminary agenda covers a tariff truce extension, Chinese purchases of US farm goods and aircraft, rare earth flows, AI safety, fentanyl, and even Taiwan and Middle East issues.
For chip investors, the thing that matters most is whether export controls on advanced AI chips actually change. Based on what's public about the pre-negotiation scope so far, there isn't enough there to assume a full rollback of tech controls. Rather than trading pre-summit speculation, it's likely safer to wait for the official statement and check how it phrases the tariff truce timeline, rare earth export licenses, and advanced semiconductor rules.
For Nvidia, which needs China revenue, any easing of restrictions would add option value. But treating a China revenue recovery as a base case for current earnings still looks premature. In political events like this, the wording tends to matter more than the buildup, and actual license enforcement tends to matter more than the wording.
AI stocks have a new dividing line: financing, not chips
Oracle offered a good example last week. Even as AI cloud demand and its order backlog keep growing, the market is no longer only asking "how much can it sell." It's also asking how much debt is needed to build the data centers behind those orders.
Reuters reported that roughly $18 billion in loans tied to Oracle's Project Jupiter are trading at 89 to 91 cents on the dollar. Credit markets, not equity markets, are pricing in financing strain first.
That shift matters for AI broadly. When rates sit near 3%, pulling forward distant future cash flows carries little cost. Near a 5% 10-year yield, the math changes. Even with identical revenue growth, the cost of capital rises, and heavily leveraged companies see both capital spending and interest expense climb at once.
| Relatively favored at 5% rates | More vulnerable at 5% rates | |
|---|---|---|
| Financing | Built on operating cash flow and cash reserves | Depends on heavy borrowing and project financing |
| AI investment | High utilization and proven customer ROI already confirmed | Building ahead of distant, unproven future demand |
| Valuation | Current earnings and free cash flow support the multiple | Long-term growth expectations make up most of the value |
| Investment read | A rate-driven pullback may just be a price issue | Rates and credit spreads can shake the business model itself |
Memory is trading pre-earnings expectations this week, not earnings
Micron's fiscal fourth-quarter results land on September 30, not this week. So memory stock moves this week are likely to be driven more by positioning and shifting expectations than by actual numbers.
The core debate in memory stocks is simple. If AI server and HBM demand keeps outrunning new supply for longer, today's elevated profits can persist longer than expected. On the other hand, if Samsung Electronics, SK hynix and Micron's large capacity additions all land together in 2027-2028, and model efficiency improves faster than expected on top of that, today's profits could end up looking like a textbook cycle peak.
So the more important thing isn't that Micron's stock has run up a lot. It's which direction HBM pricing, DRAM blended gross margin, 2027 supply contracts, and capex growth move in the next earnings report. A high stock price by itself isn't a reason to sell. What matters is whether the evidence for the durability of these high profits is weakening.
This week's calendar: watch the direction of the smaller data, not the big numbers
| Date | Key event | Why it matters for markets |
|---|---|---|
| Wed, Sep 23 | S&P Global September flash PMI | Check whether energy costs are spreading into input and output prices |
| Thu, Sep 24 | Trump-Xi summit, new home sales, weekly jobless claims | Trade, rare earth and advanced-tech wording that could move the semiconductor risk premium |
| Fri, Sep 25 | August durable goods orders, final Michigan sentiment | A simultaneous check on business capex and inflation expectations |
| Wed, Sep 30 | Micron fiscal Q4 earnings | Not this week, next week. The key test event for the memory cycle |
Three paths for markets this week
Base case: 10-year hovers near 5%. If oil trades around $100 and the 10-year stays in a 4.8-5.1% range, stock-level differentiation is likely to keep dominating over the index level. This favors scaling into companies with strong cash flow and earnings visibility over chasing rallies.
Relief case: oil and inflation expectations fall. If Middle East supply worries ease and inflation expectations come down, pressure on long-term yields could ease too. In that scenario, semiconductors and growth stocks that have been held back by a high discount rate could see more upside momentum.
Stress case: oil spikes again and credit spreads widen. If oil surges again, the 10-year gets stuck above 5%, and spreads on AI infrastructure loans widen further, heavily leveraged AI infrastructure companies are likely to feel the pressure first. In that case, financing structure needs to be checked before revenue growth.
The one-line takeaway
This week doesn't decide whether AI survives. It decides who can protect their profits and who can invest without debt under a 5% discount rate on the 10-year.
Insight Times Editorial Desk