The Question Markets Asked This Week: Who Controls the AI Bottleneck, Not Who Owns AI
The Fed hiked again and the 10-year topped 5 percent, but the center of the AI trade held. The market is no longer asking whether AI is growing, it is asking who controls memory, power and capital.
The question this week's market rewrote
On September 16, the Federal Reserve raised its benchmark rate by 25 basis points to 3.75%-4.00%, its first hike in three years. The same day, the 10-year Treasury yield crossed 5% intraday. That combination is normally bad news for the valuations of long-duration growth stocks.
But the market did not fall apart. On September 18, the Nasdaq rose roughly 0.4% and closed the week in positive territory. Semiconductors held up especially well. The scene points to something important: this is no longer a market where rates push every growth stock in the same direction. It is a market that is starting to ask how much cash flow and supply constraints can offset the shock of a higher discount rate.
Fed funds target range after the September FOMC meeting: 3.75%-4.00%
10-year Treasury yield: crossed back above the psychological 5% line this week
Oil: Brent and WTI both sitting above $100, a variable that pressures rates and inflation at the same time
Bottleneck one: in HBM4, who can scale fastest matters more than who has the monopoly
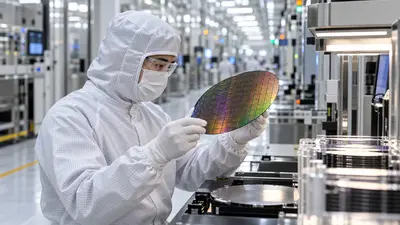
SK hynix has already begun mass production of HBM4, the primary memory for Nvidia's Vera Rubin platform, and the company confirmed in its second-quarter earnings call that large-scale HBM4 shipments have started. Attention is now shifting one layer up, to stacking technology.
SK hynix is leading mass shipments of 12-high HBM4, the workhorse SKU for Vera Rubin, while supply-chain trackers are also picking up early signals of initial-volume shipments of the next-generation, ultra-high-capacity 16-high 48GB HBM4, evidence of a lead in high-stacking technology. Full system-level mass supply of the 16-high part still needs official confirmation, including TSMC's advanced packaging yields and customer certification.
One point needs to be stated clearly: the HBM4 supply chain for Nvidia's Vera Rubin is an official three-way contest among SK hynix, Samsung and Micron. It is not a monopoly held by a single supplier. That said, supply-chain estimates and market research suggest SK hynix holds a strong position in initial core allocations, while Samsung is rapidly expanding its supply share on the back of HBM4 certification and yield improvements.
Some supply-chain estimates put SK hynix and Samsung together effectively controlling more than 80% of Vera Rubin's HBM4 supply. That figure has not been confirmed officially by Nvidia and should be treated as an estimate, not a disclosed share. What investors should watch more closely are the actual bit shipments, yields, average selling prices, and the mix between 12-high and 16-high product at each company.
The bigger picture is a supply shortage across memory as a whole. TrendForce has said DRAM supply growth is failing to keep pace with demand, and SK hynix management has warned that the shortage could become severe by 2027. As HBM absorbs wafer capacity and advanced packaging capacity, price pressure could spread to server DRAM, enterprise SSDs and commodity DRAM.
Bottleneck two: power may choke supply before GPUs do
Morgan Stanley has named "Politics of Energy" as a core theme for 2026. As data center power demand collides with electricity rates and local community costs, power has stopped being a technology problem and become a political, regulatory and permitting problem.
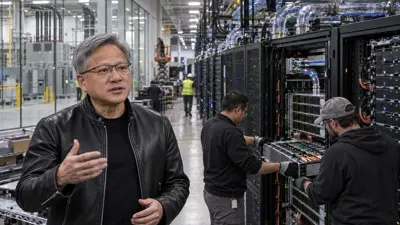
Morgan Stanley estimates that US data centers will need roughly 68 gigawatts of power from 2026 to 2028, while grid capacity under construction or contracted comes to only about 30 gigawatts. In some regions, grid interconnection could take five to seven years. That gap has pushed on-site generation, fuel cells, gas turbines and energy storage from "backup options" into "core infrastructure that buys time."
That is why Bloom Energy is drawing attention. The company says it can supply data center power from fuel cells in as little as 90 days, and it has worked with Oracle on a project targeting on-site power within that same window. That figure comes from Bloom's own claims and depends on project conditions. But what the market is really pricing is not the technology itself, it is time to power: how fast electricity can actually be connected.
Bottleneck three: capital itself is now expensive
A 10-year yield at 5% is not just a number on a chart. In businesses that require billions of dollars, like data centers, power equipment and semiconductor fabs, the cost of capital itself becomes a competitive edge.
In this environment, differences widen even among AI growth stocks that look similar on the surface. A hyperscaler that can fund capex out of massive operating cash flow and an unprofitable company that still needs external financing do not deserve the same valuation even if they post the same growth rate. As AI adoption spreads, not every AI-exposed company benefits. Companies where capital costs and depreciation grow faster than the revenue AI actually generates could come under pressure instead.
That is also why Morgan Stanley has emphasized "AI Technology Diffusion" this year. What matters going forward is less about model performance improving and more about how fast real companies adopt AI and turn it into productivity. The earnings gap between companies that use AI well and those that do not is likely to widen into a stock-price gap.
SpaceX and the trap of supply and demand
This week SpaceX offered a lesson in separating flows from fundamentals. Nasdaq-100 rebalancing was estimated to require roughly $15.5 billion to $22 billion in passive buying.
But that money does not arrive all at once on the morning of September 21. Ahead of the new weighting taking effect, most of that buying is typically executed at the September 18 closing rebalance. Even with large mechanical buying on one side, if selling on the other side is larger, the stock does not necessarily rise.
| This week's theme | The story on the surface | What actually matters |
|---|---|---|
| HBM4 | Who is the number one supplier | Certification, yield, ASP, stack height, actual shipment volume |
| AI power | Power demand is exploding | Time to power, grid interconnection, on-site power contracts, fuel costs |
| SpaceX | A large wave of passive inflows | Increase in float, lockup expirations, actual earnings and valuation |
| Big Tech | AI capex keeps rising | Free cash flow, depreciation, AI revenue conversion, cost of capital |
What individual investors should change
The riskiest move in a week like this is dumping every AI holding because rates went up, or the opposite, piling into semiconductors near highs simply because they held up.
A more practical approach is to split AI exposure inside a portfolio into three layers. The first is suppliers sitting closest to the actual bottleneck: Nvidia, Broadcom, TSMC and memory makers. The second is platforms that can fund AI capex from their own cash flow: Microsoft, Alphabet, Amazon and Meta. The third is infrastructure that becomes necessary as AI spending grows, such as power and networking.
By contrast, unprofitable growth names whose reliance on outside financing is growing faster than their revenue, and thematic stocks whose commercialization has not been proven yet, could face a bigger discount rate as rates rise further. Treating every AI ETF as interchangeable ignores that difference.
Insight Times Editorial Desk