This Week's Market Test: AI Growth Meets 5% Rates and $100 Oil
This week is not simply about whether AI stocks bounce back. With the Fed having just hiked again, the 10-year yield sitting near 5% and Brent crude holding near $100, the market is asking whether AI's growth can outrun this cost of capital, not how big that growth will be.
US Stock Market Weekly Brief
| Rates | 10-year yield at 5% | The key level squeezing both stock valuations and corporate funding costs at once |
| Oil | Brent near $100 | This week's line marking both inflation risk and Middle East risk premium |
| Politics | US-China summit | Rare earths, AI, the tariff truce and tech restrictions are the market's real focus |
1. The most important number this week is 5
The 10-year Treasury yield broke above 5% last week for the first time since 2023. Reuters pointed to high oil prices, strong growth, heavy Treasury issuance and corporate borrowing tied to AI investment as the forces pushing long-term rates higher.
Something important has shifted here. In the past, even when rates were high, hopes of an imminent rate cut kept growth-stock valuations propped up. Now it's the opposite. The Fed has actually raised rates, and another hike remains on the table. Chicago Fed President Austan Goolsbee has said that if strong demand keeps pushing prices up, the Fed needs to respond with higher rates.
So this week, the absolute level of the 10-year matters less than whether it settles above 5% or slides back below it. Stability under 5% would give room to breathe to the Nasdaq and to long-duration growth names in software, internet and names like Tesla. Staying above 5% for long likely caps how much multiples can expand, even if share prices rise.
2. Rates get easier only if oil comes down
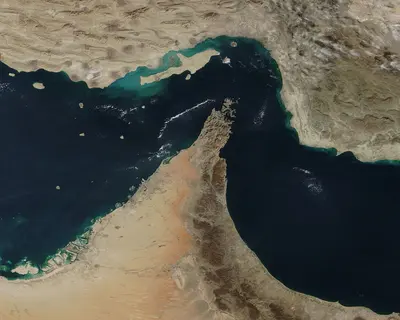
Brent crude has recently pulled back toward $100. Saudi crude flows have come in stronger than expected, and the possibility of US-Iran diplomacy is also lowering the supply-disruption premium. Still, it's hard to say Middle East supply chains have fully normalized. Shipping costs for routes avoiding the Strait of Hormuz and the Red Sea remain very high, and logistics remain unstable.
This week, oil matters for more than energy-sector earnings. The market is reading it through a chain: more inflation, then another Fed hike, then higher long-term rates.
That's why oil settling below $100 would be fairly favorable for stocks. If Brent snaps back quickly above $103-105, the same pressure on long rates seen last week could return.
3. Thursday's US-China summit: watch rare earths, not just tariffs
Chinese President Xi Jinping is set to visit the United States from September 23 to 25. A summit with President Trump is scheduled for Thursday. The two sides are expected to discuss trade, AI, the war in Iran and Taiwan.
Tariff headlines may grab the most attention in stocks, but the industrially significant issue is rare earths and AI export controls. China holds overwhelming influence over global rare earth mining, refining and magnet supply chains. Reuters has noted that this supply-chain dominance is one reason the US has taken a less aggressive negotiating posture toward China than before.
For semiconductor investors, specific language matters more than vague talk of "improved US-China relations." AI chip export licenses, rare earth access and whether the tariff truce gets extended are what actually connect to fundamentals.
4. AI can strengthen again, but this time it needs cash flow
AI-related stocks are drawing renewed hopes for expanded investment. But the market's question has changed from last year. Back then, the key question was "how big will AI investment get?" Now the more important question is "can this investment generate enough revenue and cash flow to outrun a 5% rate?"
That's why this week calls for watching the spread across the whole AI ecosystem rather than just Nvidia. Is the rally limited to chips, or are servers, networking, cloud, software and enterprise AI adoption services strengthening together?
If AI strength stays concentrated in a handful of chip stocks, it remains a narrow market. If AI infrastructure and software rise together, that's a signal the market is once again pricing the AI investment cycle on fundamentals.
5. This week, a "too strong" US economy is also a risk
Flash PMI data is due out this week. Normally, strong economic data is good news. Right now it's a bit different. With the Fed already back in tightening mode, data that comes in too hot could become grounds for "the Fed can hike further."
So the best combination for markets this week isn't a recession, it's growth holding up while price and demand pressure ease. If PMI comes in very strong and oil bounces back too, the 10-year could climb back above 5%.
| This week's variable | Favorable direction for stocks | Direction to watch |
|---|---|---|
| US 10-year yield | Stabilizes below 5% | Stays above 5% for an extended period |
| Brent crude | Settles below $100 | Snaps back above $103-105 |
| US-China summit | Tariff truce extended, rare earth/AI tension eases | Export controls tighten, rare earth conflict reignites |
| AI stocks | Spread from chips to software | Gains concentrated in a few megacaps |
| US economic data | Growth holds, inflation pressure eases | Overheating signals lift expectations for more tightening |
What to Watch
FAQ
Insight Times Editorial Desk