AI Competition Shifts From Chatbot Share to the 'Action Layer'
ChatGPT isn't collapsing. But as Gemini, Claude and Copilot grow through their own distribution channels, the real contest is moving from standalone chatbots to an action layer wired into search, operating systems, workplace tools, ads and payments.
01 · ChatGPT is still growing Comscore found that in June 2026, ChatGPT reached about 69% of unique visitors in the AI assistant category.
02 · Google's weapon isn't just the model, it's distribution The Gemini app has surpassed 1 billion monthly active users, and Google AI Overviews is used by more than 2.5 billion people a month.
03 · The next contest is about action, not just questions As AI takes over booking, purchasing, writing, coding and customer support, deployment, permissions, payments, reliability and cost structure all start to matter more.
Market share isn't the point. The market is going multi-platform.
Framing the AI market as "ChatGPT versus Gemini" only shows half the picture. What Comscore's public data actually shows is not that ChatGPT usage is shrinking, but that rival services are growing fast at the same time.
In March 2026, ChatGPT's desktop conversation volume rose 55% year over year. Over the same period, Claude's desktop conversation volume jumped 1,858% from October 2025, reaching 22 million. Users aren't abandoning one AI for another. They're running several in parallel depending on the task.
69% — ChatGPT's share of unique visitors in the AI assistant category, per Comscore, June 2026
1 billion+ — Gemini app monthly active users, disclosed by Google in August 2026
2.5 billion+ — Google AI Overviews monthly active users
These figures come from different methodologies and time frames, so they can't be compared directly as market share. But the direction is clear. AI isn't heading toward a winner-take-all market. It's heading toward a market where one person uses several different AI tools depending on the job.
That means the metric to watch can no longer be a single "prompt share" number. Weekly and monthly active users, time spent, paid conversion, enterprise seat counts, API revenue, agent execution volume, and actual task-completion rates all need to be tracked together.
Distribution is beating the model
Once model performance flattens out past a certain point, the center of competition shifts to distribution. Google has Search, Android, Chrome, Gmail, YouTube, Maps, Docs and Drive. Users don't need to seek out the Gemini app; they run into AI inside Google products they already use.
Microsoft is similar. It has Windows, Microsoft 365, Teams, Outlook, GitHub, Azure, and enterprise security and management systems.
According to figures Microsoft disclosed for its fiscal 2026 fourth quarter, GitHub Copilot has reached 50 million users. Copilot revenue grew more than 60% from the prior quarter, and the number of enterprise customers deploying Copilot to a majority of their information workers rose about 75% quarter over quarter. AI is turning from software people buy separately into an intelligence layer added on top of software they already use.
AI looks less like a search substitute and more like a new internet interface
The old default path on the internet was: type a search query, pick a link, compare several pages, decide, then act. AI compresses that into ask, compare, recommend, decide, act.
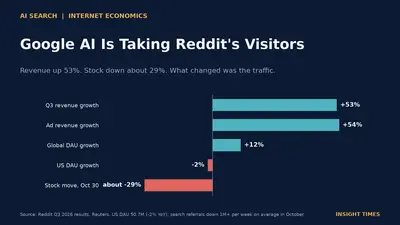
What matters isn't just that website clicks are declining. It's that user decisions are increasingly being made inside the AI itself. Google says AI Overviews now has more than 2.5 billion monthly active users, and AI Mode has passed 1 billion.
So the metrics publishers and brands need to watch are changing too. It's no longer enough to check search ranking. Brands need to track which questions the AI mentions them for, whether it cites them as a source, whether it includes them in a shortlist against competitors, and whether purchases, sign-ups or inquiries follow a recommendation.
SEO isn't disappearing. AEO and GEO are being layered on top of it.
Content value now splits into three layers
| Layer | Key question | Business meaning |
|---|---|---|
| Information source | Does AI reference our content and data? | Expertise and data assets |
| Citation and link exposure | Does the brand name, source or link show up in the answer? | Awareness and potential traffic |
| Conversion impact | Does an AI recommendation lead to a purchase, sign-up or inquiry? | Actual revenue and customer acquisition |
Comscore has also started separately measuring which content AI references, whether that leads to actual site visits, and how AI exposure affects downstream consumer behavior.
In this environment, content that merely reorganizes what other sites already said may lose economic value. By contrast, proprietary data, original research, quantitative comparisons, real usage experience, original interviews and verified expertise could become more valuable.
The goal is content that AI can summarize, but whose credibility drops noticeably once you strip out the source — content that's worth citing, not just worth quoting.
Advertising is moving from above the link into the answer itself
As AI becomes the gateway for search and recommendations, advertising follows it in. Comscore analyzed ChatGPT prompts related to hotels where a source link could be identified, and found the share containing sponsored ads rose from 6% in March 2026 to 14% in April and 24% in May.
OpenAI said in August 2026 that ChatGPT Ads had reached $1 billion in annualized revenue. Google, too, runs Search and Shopping ads inside AI Overviews.
The old competition was buying the keyword "running shoes." In the AI era, businesses need to land inside the shortlist for a query like: "Recommend running shoes under $150 for wide feet, for someone running 5K three times a week with low knee stress."
Structured information such as price, inventory, shipping, return policy, reviews and location now matters more. Spending heavily on ads isn't enough on its own. A company has to become the kind of business AI wants to recommend.
Big tech investors need to watch who owns the action layer
| Company | Structural strength | What investors should watch |
|---|---|---|
| OpenAI | ChatGPT brand, consumer habits, API, agents | Whether ads, subscriptions, enterprise and commerce revenue outpace inference costs |
| Alphabet | Search, Android, Chrome, Workspace, YouTube, ads | Whether AI grows search usage and ad revenue together |
| Microsoft | Windows, Microsoft 365, GitHub, Azure | Whether Copilot seats convert into actual usage and cloud revenue |
| Anthropic | Coding, long-form analysis, enterprise knowledge work | How far enterprise deployment and API economics can scale |
| Meta | WhatsApp, Instagram, Facebook | Whether social AI connects to advertising, messaging and commerce |
The most important shift here is that having lots of AI users and making good money from AI are two different problems. Even if AI usage explodes, if inference costs, GPUs, data centers and power costs grow even faster, that becomes a drag on valuation.
In the end, investors need to watch user growth, usage growth, monetization and per-unit inference cost all at once, not any single one of them in isolation.
Insight Times Editorial Desk