Every Time You Trade, Borrow or Sit in Cash, Someone Else Gets Paid

Retail investors don't just lose to bad information. Much of the financial industry earns more from trading, borrowing, cash balances and attention than from investor returns themselves.
The market earns more easily from your activity than from your returns

It takes time for a company to grow earnings, build cash flow, and let shareholders collect the fruits of compounding. Financial infrastructure works differently. It can generate revenue the moment an order hits the market, today. A $0 trading commission does not mean the economic cost is zero. Revenue comes in layers: the spread and price improvement embedded in order execution, options trading revenue, what the firm earns on customer cash, advisory fees, and interest on margin loans.

Financial platform revenue base ≈ trading activity + customer cash and assets in custody + loan balances + advisory fees + order flow and execution-related income

None of this makes the structure inherently unfair. Brokers and market makers provide liquidity, execution, custody and credit. The problem is that the behavior that maximizes a firm's revenue does not always match the behavior that maximizes an individual's long-term compounding.

A financial firm can make money without knowing what you'll buy today. A retail investor has to get right what to buy, at what price, and how long to hold it.

Even in the age of "free trading," an order is never free

Payment for order flow, or PFOF, is the practice where a broker routes customer orders to a specific market maker in exchange for payment. Describing this simply as "selling retail order data" is inaccurate. The SEC has stated that PFOF, cash sweep programs, and various fees and sales incentives can create conflicts of interest. At the same time, brokers carry a best-execution obligation.

The important question isn't whether a broker is cheating you. The more useful question is how much invisible, compounding cost builds up as you trade more often, and how much that erodes your investment results. In the classic study by Barber and Odean, among 66,465 households, the group that traded most actively earned an annualized return of 11.4%, well below the 17.9% market return over the same period. The sample and the era are dated, but the finding remains a leading piece of evidence on the cost of overtrading.

11.4% — annualized return of the most active-trading households 17.9% — market return over the same study period 75% — average annual portfolio turnover for the typical household

The real danger of trading on margin isn't the loss percentage, it's losing time

The math of margin is simple. Put up $100,000 of your own capital, borrow another $100,000, and invest $200,000 total. If the stock drops 30%, the position falls to $140,000. The $100,000 loan is unchanged, so your equity falls to $40,000, a 60% decline. Interest and trading costs come on top of that.

With 2x leverage, a -30% stock move becomes roughly -60% equity, before interest and costs

The bigger issue is path dependency. A cash investor can sit through a 30% drawdown and wait for a recovery. A margin investor who breaches a maintenance requirement doesn't get that option. The SEC notes that a broker can sell securities to meet a margin shortfall without consulting the customer first, and can raise maintenance margin requirements without advance notice.

Borrow $100,000 at 8% annual interest and you owe $8,000 a year just in interest. If the stock goes sideways, the asset price hasn't moved, but the investor's break-even point keeps drifting further away. The biggest cost of leverage sits on the opposite side of "amplified returns": the possibility of forced liquidation.

Broker earnings make the structure clearer

Charles Schwab, one of the largest US brokerages, reported net revenue of $23.921 billion in 2025. Net interest revenue made up $11.750 billion of that, roughly 49% of the total. Trading revenue came to $3.921 billion, of which $1.930 billion was tied to order flow. Schwab discloses that the asset base behind its net interest revenue includes customer cash, margin loans, bank loans and bonds.

Schwab 2025AmountShare of net revenue
Total net revenue$23.921B100%
Net interest revenue$11.750B~49%
Trading revenue$3.921B~16%
Order flow revenue$1.930B~8%

These numbers don't mean a broker profits from customer losses. They point to something more important: brokers have a structure that can generate recurring revenue from the customer relationship, independent of whether the customer's market bets pay off. What an individual investor needs is not to treat this structure as an enemy, but to control the unnecessary costs within their own reach.

Media needs a new story every day. A portfolio does not need to change every day

Financial media and investment content carry their own structural tension. Advertising and subscription businesses depend on sustained attention. Since markets move every day, there's always a new interpretation to produce. But a company's long-term cash flow and competitive position usually doesn't change on a daily basis.

That argues for changing how you use news. Don't treat a headline as a trading signal. Treat it as a tool for testing your investment thesis. Better questions to ask first: Will this still matter in three years? Does it actually damage the company's long-term cash flow? Is this new fact one that breaks my original investment case?

Content has to be made every day. Your portfolio does not have to move every day.

The advantage of dollar-cost averaging isn't the highest return, it's turning behavior into a system

Dollar-cost averaging is not a strategy that guarantees higher returns than investing a lump sum all at once. If markets trend upward over the long run, there are plenty of stretches where deploying cash you already have, quickly, works out better. DCA's real strength lies elsewhere: it's a behavioral rule that lets you invest a recurring cash flow, like a paycheck, on a regular schedule, without letting fear or greed dictate the timing of each purchase.

For long-term investors, three things matter more than the doctrinal fight over DCA versus lump sum: avoiding leverage you cannot handle, keeping turnover low, and building a capital structure that lets you stay in the market as long as your investment thesis remains intact.
Sungdong KimAuthor of the Korean book “The US Stock ETF Investing That Never Fails”. A long-term investor in U.S. stocks since 2019.

More by topic

Starting with this story's topics, then what readers are following now

Investor psychology, decision-making and books on investing

A building that houses servers and networking gear and supplies them with powe…

Nvidia and Palantir Put AI Inside the Supply Chain - The Real Shift Is That It's Learning Judgment

A single Vera Rubin rack holds 1.3 million parts. The real breakthrough in Nvidia and Palantir's new supply chain AI isn't automating that complexity, it's capturing the judgment calls that used to live only in planners' heads.

Tech

AI ran out of memory before it ran out of GPUs

The HBM bottleneck is spreading into DRAM prices, server costs and the price of the next laptop or phone.

Tech

Is Space Cooler for AI? Why Musk Wants Data Centers in Orbit

The next limit on AI may be power and cooling, not GPUs. Elon Musk is looking to Earth orbit for an answer, but the test is cost per hour of compute.

Tech

Musk Sees the Next Phase of AI Infrastructure: Who Can Switch GPUs On, Fast

If neoclouds struggle under financial pressure, AI demand may not shrink. It may simply favor the few operators with the capital and execution to serve it, a shift that could matter for SpaceX and Tesla.

Tech

White House Swaps AI for "SI." The Real Investment Signal Is Infrastructure, Not the Name

An executive order renames artificial intelligence "Super Intelligence" and six frontier labs sign a voluntary safety accord. What investors should watch is the data center, power, nuclear and chip policy now gathered under one national-competitiveness frame.

Tech

The Cheaper Tokens Get, the Bigger Your AI Bill Gets

As AI shifts from training to inference, the token is becoming an industrial commodity. Falling prices are not cutting demand, because agents and automation consume tokens at a scale no human chat session ever did.

Investing

Marvell's $115 Billion Lumentum Deal: Is AI's Next Bottleneck Light, Not Chips?

Marvell's purchase of Lumentum points to a contest beyond GPU speed, in data transfer and power efficiency. Whether the price is right is not yet confirmed.

Tech

NVDA

98 storiesSee all →

Who Hits $1 Trillion Next: Reading AMD and ASML by Different Rules

One company is chasing Nvidia's GPU empire. The other sells the machine that draws the chips for every advanced chipmaker, including Nvidia. Both get floated as 2028 trillion-dollar candidates, but the numbers investors need to watch are entirely different.
Investing

China's AI Labs Went Open Source Because They Had to, Not Because They Wanted To

A GPU shortfall pushed Chinese AI labs toward efficiency and open weights, and that constraint is now reshaping the global competition over who controls AI's basic infrastructure.

Tech

Box Shows AI Its Manuals, and the AI Starts Redesigning the Workflow

Box Architect, built with NVIDIA, moves AI from reading documents to designing how work gets done. It has not yet reached beta, so the real-world payoff remains to be seen.

Tech

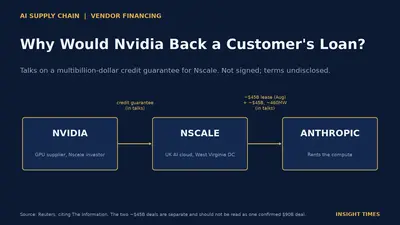
Dark navy cover. Flow diagram: Nvidia to Nscale (credit guarantee, in talks) to Anthropic (~$45B compute lease signed in August plus a separate ~$45B, ~460MW deal in talks). Title: Why Would Nvidia Back a Customer's Loan?

Why Would Nvidia Guarantee Its Customers' Data Center Loans?

Nvidia is reportedly in talks to back financing for Nscale's West Virginia data center. Nothing is signed, and the terms are not public.

Tech

Before Robots Sell, Chips Sell First: Following the Money in the Humanoid Race

Billions of dollars are moving before humanoid robots reach mass sales. Compute suppliers may see revenue first, but that does not guarantee stock returns.

Tech

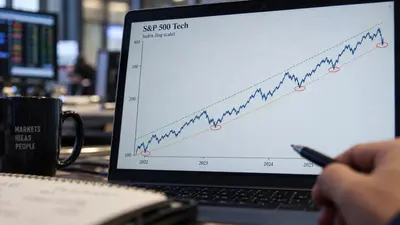
Tech Selloff: Is the Bull Market Over? Wall Street's Four-Year Chart Says Not Yet

The uptrend has survived five double-digit pullbacks in four years. This time, AI companies' debt and cash flow are the new variables.

Investing

The AI Bubble Question Has Changed: By Late 2026, It's ROIC Over GPUs

There is no sign yet that AI investment is slowing. If anything, hyperscaler spending forecasts keep climbing. But as the scale of that capital has grown, the market's question has shifted from "is AI growing" to "when, and how much, does this capital come back as cash."

Tech

HBM

77 storiesSee all →

Memory stacked next to the GPU.

Memory Is Still Short, but Less Short: Checking for the Peak This Week

Citi trimmed its 2027 DRAM and NAND shortage forecasts together. Server pricing remains strong, while consumer markets show weakness. This week's numbers show where the memory boom may peak.

Investing

The Real ASML Number Isn't the 3% Pop, It's the 30% Capacity Hike

ASML's rally isn't just an AI trade. Customers are already locking in 2027 tool slots, and ASML is raising Low-NA EUV capacity by roughly 30% to keep up.

Investing

A 3x P/E is not a discount. It is a verdict on how long memory profits last

Nomura's buy case on Samsung Electronics and SK Hynix does not stop at higher memory prices. It argues that if AI has turned memory from a cyclical component into strategic infrastructure, the formula the market uses to value both companies has to change too.

Investing

2027 Isn't the End: Citi's Case for a Memory Supercycle Running to 2031

Citi says the memory shortage timeline is stretching again. If AI shifts from "train once" models to continual learning, HBM, server DRAM and enterprise SSDs could all fall short at the same time.

Tech

Has Memory Peaked? Prices Are Cooling, but the Shortage Looks Set to Run to 2028

Price growth has slowed and consumer demand is already breaking. Server and HBM supply remains short, and Micron says more than 75% of its 2027 volume is already committed to customers.

Tech

AI Chips Haven't Peaked. The Real Risk Sits in 2028 Supply

HBM and server DRAM shortages are now spreading into enterprise SSDs. The question isn't today's strength, it's how much new capacity these prices are pulling in and when it lands.

Investing

AI Chip Peak Check: Demand Still Rising, Risk Building in 2027-2029 Supply and Funding

DRAM and NAND contract prices are still climbing and HBM suppliers hold the edge. Power shortages, AI financing costs and simultaneous memory expansion are the risks for later years.

Investing

GPU

70 storiesSee all →

A chip built to draw graphics, whose ability to run thousands of identical cal…

The Next AI Chip Race Is About How Chips Connect

Applied Materials will lift its stake in Dutch equipment maker BESI from about 9% to 20%. The bet is less about control than about a new way to link chips.

Tech

Musk Borrowed $40 Billion for GPUs. He Also Warned AI Cloud Firms Could Go Bust

SpaceX's giant financing shows a new dividing line in AI: who borrows matters as much as how much is spent. Firms with other revenue may outlast those that rent out GPUs alone.

Tech

US AI Data Centers Are Headed for 90GW. Gigawatts Now Matter More Than Dollars

Goldman Sachs expects US data center capacity to grow from 64GW at the end of 2026 to 90GW at the end of 2027. The AI race is moving from buying GPUs to building power plants and transmission lines alongside them.

Tech

2027 Investing Needs Alignment, Not Prediction

A new investing book argues the hard part was never picking the next winner. It's staying aligned with where value and bottlenecks are moving while keeping old human weaknesses in check.

Investor Mind

Why Nebius Is Keeping Some 2027 AI Capacity Off the Shelf

Nebius mixes long-term contracts, short-term premiums and auctions. Holding back capacity pays only if the servers stay busy, and it is not yet clear the pricing will last.

Tech

Two Companies Drive 34% of S&P 500 Earnings Growth as AI Pays Sellers First

Nvidia and Micron generate a third of expected earnings growth in US large caps. Apollo says the financial effect of AI is not yet visible in the S&P 493.

Investing

Amazon Goes After Nvidia's Strongest Moat, and It Is Software, Not GPUs

Amazon's open-source TorchNeuron aims to let existing AI code run on its Trainium chips. The contest comes down to the total cost of AI compute and the return on Amazon's $220 billion in annual capital spending.

Tech