Who Buys the T-Bill Behind Your $1 Stablecoin

Stablecoins aren't a crypto asset class so much as new plumbing for moving dollars online, and every new dollar that flows in gets tied to short-term Treasuries.
Behind every $1 coin sits a $1 asset

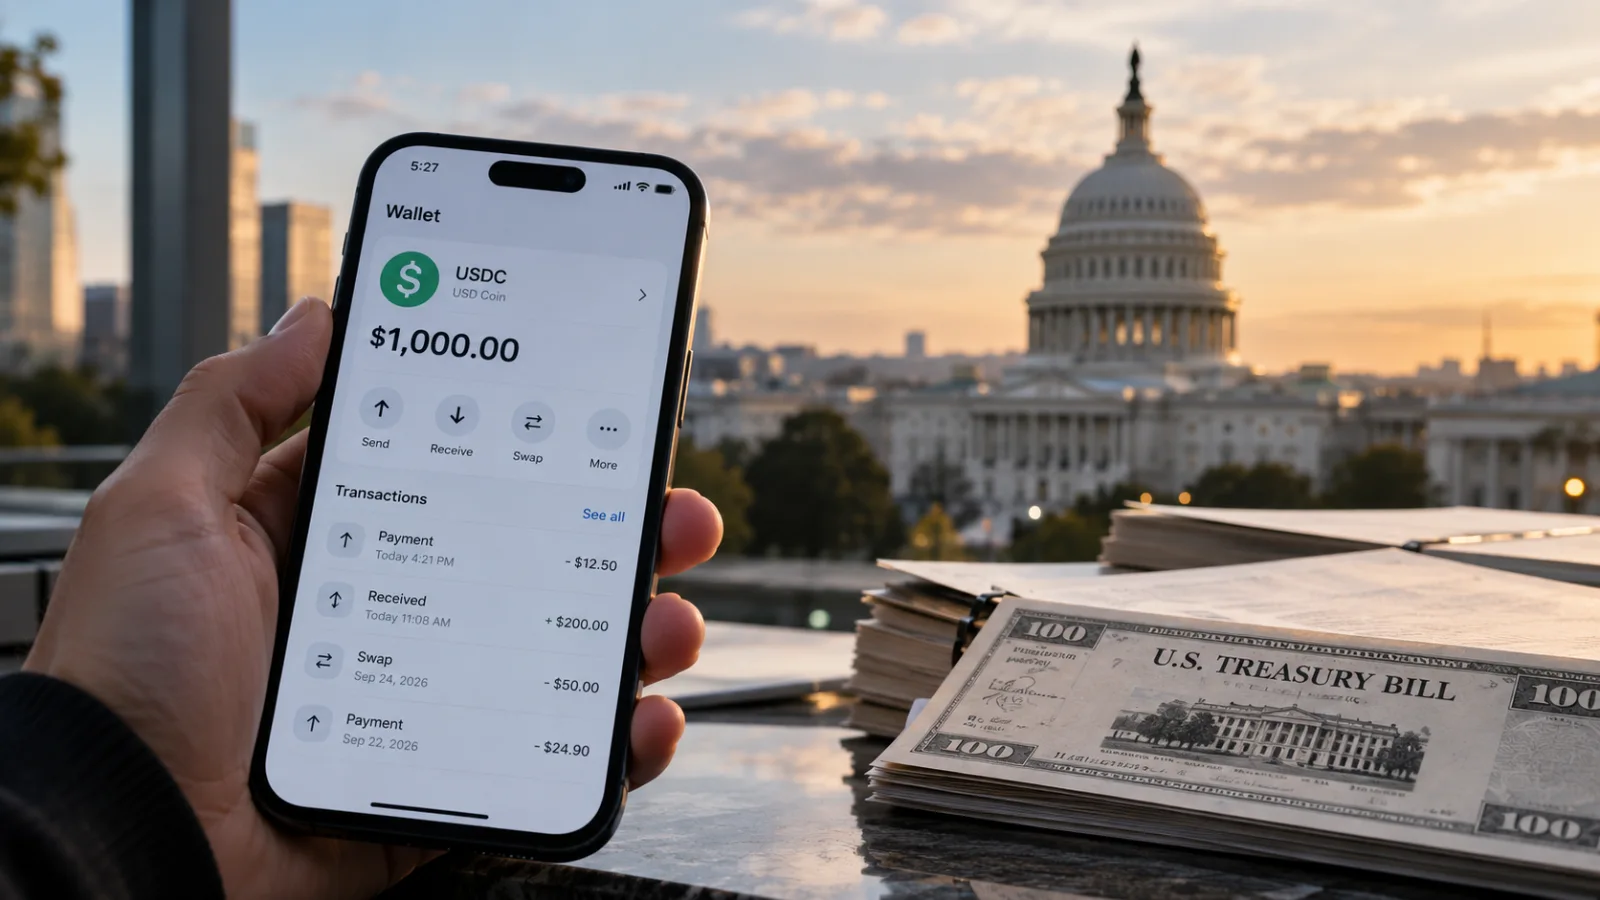
The $1 stablecoin sitting in a phone wallet looks like digital cash. On the issuer's balance sheet, it's a liability. When a user deposits $1, the issuer hands over a $1 coin and holds the incoming cash in cash-equivalents or short-term Treasury bills.

The GENIUS Act requires licensed payment-stablecoin issuers to hold at least a 1:1 reserve, and it limits eligible reserve assets to cash, demand deposits, Treasury bills with 93 days or less remaining to maturity, and short-term repo backed by those bills. Issuers must disclose reserve composition every month, and the law bars them from paying interest or yield directly to coin holders just for holding the token.

Users get the convenience of a digital dollar, issuers earn the yield on their reserves, and the United States gets a new base of demand for short-term Treasuries.

One distinction matters here. If an already-issued $1 coin changes hands 100 times in a day, reserves don't grow. What actually drives new Treasury demand isn't transaction volume, it's net new issuance of stablecoins.

What the US gets is bigger than just T-bill demand

Short-term Treasury demand. As newly deposited dollars pile up as reserves, they create structural demand for T-bills and other short-dated collateral.

A dollar distribution network. Anyone with an internet wallet can hold and move dollar-denominated value without a US bank account.

Regulatory reach. Reserve, redemption, anti-money-laundering and sanctions-compliance rules become the operating standard for on-chain dollars.

It's a stretch to call this classic monetary seigniorage, since the government isn't issuing the coins itself. But private issuers are creating near-zero-interest dollar liabilities and parking the reserves in Treasuries, which effectively lets the US extend the dollar's reach through a private network.

It doesn't solve America's debt problem

Stablecoin reserves cluster overwhelmingly in short-dated assets. Even the Treasuries the GENIUS Act permits are capped at 93 days or less to maturity. So even rapid stablecoin growth doesn't automatically fix the supply-demand picture for 10-year and 30-year bonds.

Research from the Bank for International Settlements confirms the split with data. Stablecoin inflows push down 3-month Treasury yields, but the pass-through to longer maturities is limited. The more striking finding runs the other way: when stablecoins see outflows, the resulting rise in yields is two to three times larger than the drop that inflows produce. Under normal conditions, issuers buy T-bills gradually. In a crisis, they have to sell fast to meet redemptions.

Stablecoins aren't a fix for US debt. They're financial infrastructure that reinforces short-term Treasury demand while also opening a new channel for a digital bank run.

Tokenization isn't a lab experiment anymore

US equity markets shortened most securities settlement to T+1 back in May 2024. So pitching tokenization's value as "shrinking two days to a few seconds" is already behind the times. The bigger shift is wallet-based access, programmable collateral, and the possibility of settling an asset and its cash leg simultaneously.

In January 2026, the SEC laid out how rights can differ depending on whether a tokenized security is issuer-direct or built through a third-party structure. On September 17, it also approved a temporary "Innovation Exemption" letting certain on-chain venues trade tokenized NMS stocks under limited conditions. Tokenization is starting to move inside US securities market infrastructure rather than sitting as an unregulated shadow market.

Today's US stocksWhat changes with tokenized securities
Brokerage-account accessWallet-based access becomes more viable
Mostly T+1 settlementFaster transfer and delivery-versus-payment designs become technically possible
Rights structure fairly standardizedLegal rights can differ between issuer-direct and third-party structures
Broker and clearinghouse-centeredCustodians, token issuers, blockchains and oracles all matter more

The key question isn't whether trading runs 24 hours a day. It's whether the token actually represents one real share, how dividends and voting rights get passed through, and what claim investors have if the issuer goes bankrupt.

Where the money actually flows

Home currency → exchange or payment processor → dollar stablecoin → tokenized asset or settlement → issuer reserves → short-term US Treasuries

The number investors should watch in this chain isn't on-chain transaction volume. It's how much total stablecoin supply has grown, what reserve assets it's shifted into, and how much net redemption is happening.

Banks don't disappear, their role changes

If bank deposits migrate into stablecoins, banks could lose a cheap source of funding. But the Federal Reserve doesn't see this as a one-for-one effect, since issuers often park reserves back in bank deposits or Treasury purchases, and that money can recirculate through the financial system.

In the Fed's 2025 bank survey, a good number of large banks said they were exploring tokenized deposits, stablecoin-reserve custody and digital-asset wallet services as new business lines. Banks aren't so much being displaced by blockchain as shifting from the front end of payments toward the back-end infrastructure of custody, regulation and liquidity management.

Everything changes once AI starts spending money

The biggest long-run variable for stablecoins may not be crypto investors at all, it may be AI agents. In an economy where software automatically buys a single piece of data, one API call, or a few seconds of compute, a programmable wallet fits more naturally than a credit card.

Rules like "never spend more than $1 at a time," "$20 daily limit," "pay only approved vendors," or "send payment only after verifying output" can be written directly into code. In that world, a stablecoin balance stops being idle cash waiting for a trade and becomes working capital for a machine economy.

That said, AI doesn't necessarily have to run on coins. Corporate accounts and card APIs can be automated too. The outcome will likely turn on cost, speed, programmability, refund and dispute handling, and regulatory compliance, not ideology.

Insight Times Editorial Desk
More by topic

Starting with this story's topics, then what readers are following now

Investor psychology, decision-making and books on investing

AI Agents

This story's topic43 storiesSee all →

AI that takes one instruction and works through the steps on its own — calling…

Nvidia and Palantir Put AI Inside the Supply Chain - The Real Shift Is That It's Learning Judgment

A single Vera Rubin rack holds 1.3 million parts. The real breakthrough in Nvidia and Palantir's new supply chain AI isn't automating that complexity, it's capturing the judgment calls that used to live only in planners' heads.

Tech

Google Catches Up, and Rivals Run Ahead Again

The real test for Gemini 4 Argon is not AI performance. It is whether Google can win customers and keep them.

Tech

The Cheaper Tokens Get, the Bigger Your AI Bill Gets

As AI shifts from training to inference, the token is becoming an industrial commodity. Falling prices are not cutting demand, because agents and automation consume tokens at a scale no human chat session ever did.

Investing

Box Shows AI Its Manuals, and the AI Starts Redesigning the Workflow

Box Architect, built with NVIDIA, moves AI from reading documents to designing how work gets done. It has not yet reached beta, so the real-world payoff remains to be seen.

Tech

The Number That Matters More Than How Smart AI Gets

This week's AI models got stronger and cheaper at the same time. The chart long-term investors should watch isn't the weekly benchmark leader, it's the falling cost of finishing a task successfully.

Tech

Nvidia Moves From GPUs to CPUs as AI Agents Reshape a $200 Billion Chip Market

A customer's early test found Nvidia's Vera CPU handled about twice the AI agent workload of its existing chips. The bigger story is where the money in semiconductors is heading as AI shifts from answering questions to doing work.

Tech

Nvidia's Next Target After GPUs: Controlling What AI Agents Are Allowed to Do

OpenShell and Sentry are not about policing what an AI says. They are about controlling, at the server infrastructure level, which files and APIs an AI can touch, what it can execute, and who can actually pull the plug when something goes wrong.

Tech

Fed

This story's topic24 storiesSee all →

The central bank of the United States, carrying a dual mandate — stable prices…

Gas Prices, Not Politics, Are Deciding This Midterm Market Story

Forecasts of a Republican defeat are not exaggerated. The House has tilted clearly toward Democrats, the Senate has moved from a toss-up to a slight Democratic edge, and Trump's net approval is the lowest of either term.

Macro

Why a Wobbly Yen Carry Trade Hits US AI Stocks First

It is not just dollar-yen at 160. Watch the US-Japan rate gap, yen direction, volatility, and US long-term rates together, because AI and high-valuation growth stocks get squeezed first when all four move at once.

Macro

It's Not Just Hormuz: Why the Middle East War Is Becoming a Fed Problem Again

The US-Iran ceasefire has already collapsed, and the risk no longer sits in the Gulf alone. With the Red Sea and Saudi Arabia's bypass pipeline now under threat too, an energy shock is spreading into prices, the Fed, and growth-stock valuations.

Macro

Weekly Check: The AI Bull Market Isn't Over, It's Just Gotten Harder

A 5% 10-year yield, 470 gigawatts stacked up in Texas, Chinese DRAM, and whether data centers actually get switched on are starting to decide who wins the AI trade through 2027.

Tech

Rates Hit 5% Again, But AI Held - Now Wall Street Wants Cash Flow, Not Just GPUs

The Fed raised rates and the 10-year yield broke back above 5%, yet the Nasdaq did not crack. This week's real story is not the end of the AI rally but a change in what the market is grading.

Investing

The AI Supercycle Now Favors Companies That Earn Money, Not Just Spend It

The S&P 500 is up 14.1% this year even with the 10-year Treasury yield near 5.24%. What happens next may depend on how much of the AI spending comes back as profit and cash.

Investing

Is Bitcoin Coming Back? A Recovery That Still Has to Prove Itself

Bitcoin has slipped from above $126,000 to around $83,000 while AI stocks hog the spotlight. It is up more than 40% from its summer low, but it is too early to call a new bull market.

Investing

Regulation and Antitrust

This story's topic8 storiesSee all →

SaaS

This story's topic14 storiesSee all →

Renting software by subscription instead of buying and installing it.

AI Needs to Find $1 Trillion a Year From Somewhere to Pay Back Its Capex

Saying AI capex is big is no longer the point. The harder question is what end users have to pay for the buildout to pencil out, and Goldman Sachs puts that number at roughly $1 trillion a year.

Tech

OpenAI Leaves the Chatbot Behind: DevDay 2026 and the Fight Over Digital Labor

The new model mattered less than Dots, ChatGPT Space, plugins and the Marketplace. OpenAI wants to run agents that keep doing work people hand off, and to control distribution, payment and security around them.

Tech

Why Microsoft Rebuilt Copilot: AI Billing Shifts From Seats to Workload

The redesign is less about new features than about Microsoft expanding its enterprise AI revenue model beyond the per-seat subscription into task delegation and agent execution.

Tech

Grok 4.7's Real Weapon Isn't Performance, It's Cost Per Finished Task

At $2 per million input tokens and $6 per million output tokens, SpaceXAI is pitching Grok 4.7 as an agent model for long coding and knowledge work. The number investors should watch is not the benchmark leaderboard but the total cost of finishing a job and how widely it gets adopted.

Tech

AI's Second Act: Where the Money Goes After GPUs

Morgan Stanley's 24 "AI Adopter" stocks share one trait: not heavy AI usage, but the ability to convert AI into revenue, margin and cash flow.

Investing

Who Becomes the Windows of the Self-Driving Era?

Hyundai just pushed back its own autonomous driving timeline and turned to Nvidia first. The real story is not the delay, it is Nvidia's bid to become a common platform across the entire auto industry, not just a chip supplier.

Tech

ChatGPT Space Turns the Chat Window Into a Workroom

If you think of ChatGPT as a tool where you ask and it answers, Space changes that. Documents, sources and results now stay in one place, and people and AI can keep editing them for days.

Tech