The AI Asset That Outlasts the GPU May Be the Power Line
Capital markets are starting to judge AI infrastructure less by how many chips a company bought and more by how many megawatts it can actually keep energized.
The asset's clock matters more than the 38GW headline
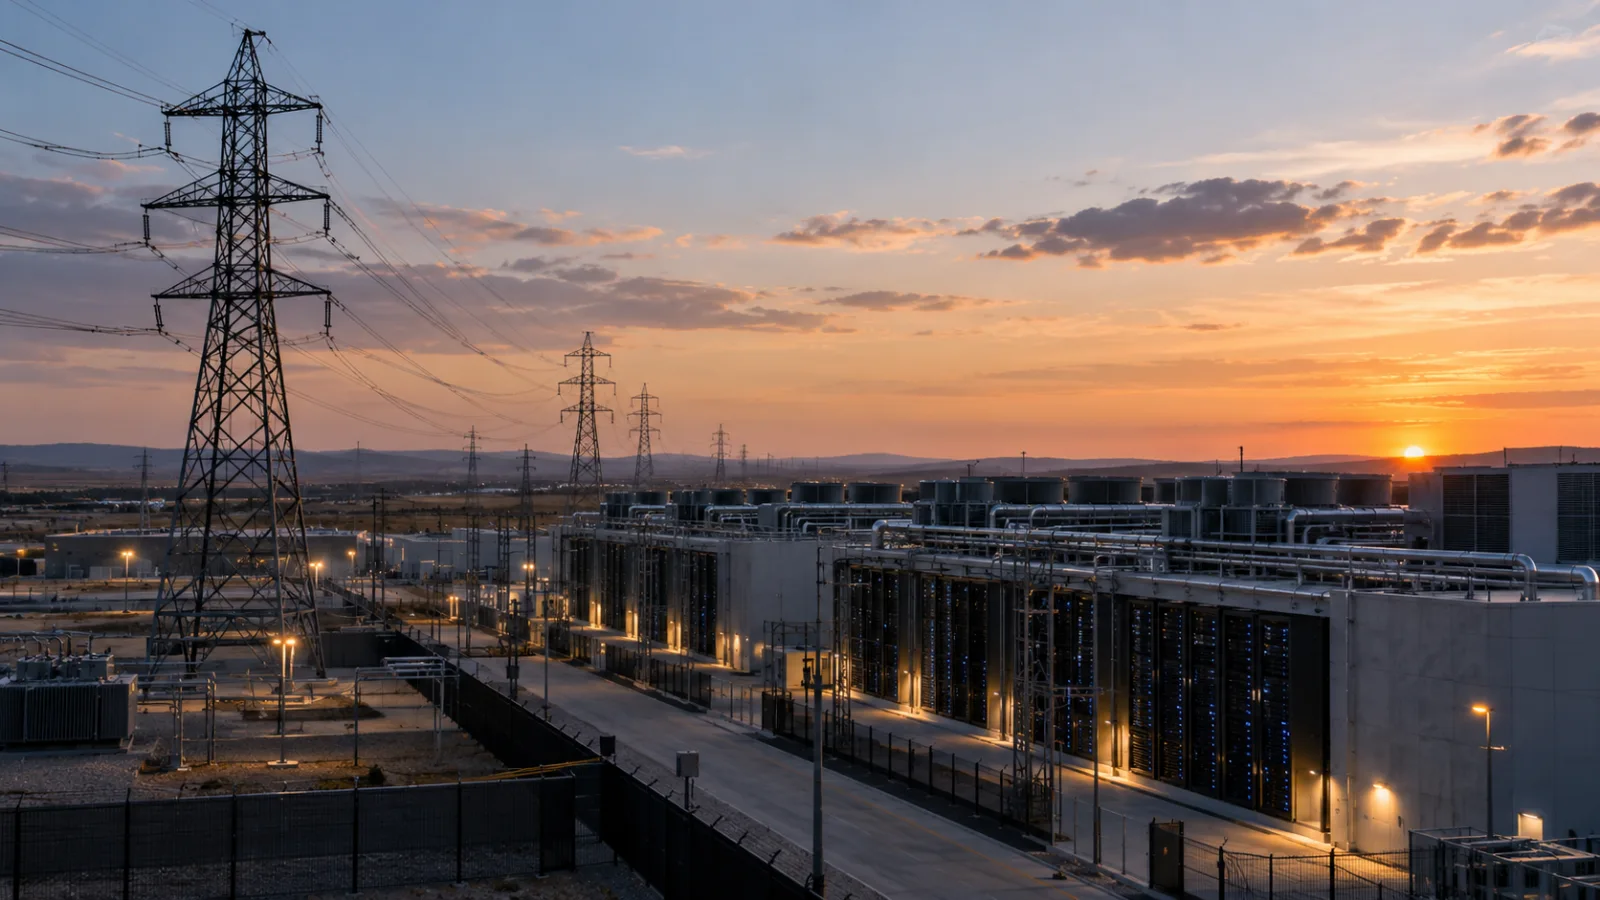
An AI data center's balance sheet holds assets that age at very different speeds. The latest GPUs can generate huge revenue, but they cycle through technology generations fast. Land, substations, cooling infrastructure and grid interconnection, the physical right to actually draw power, can be reused when the next generation of GPUs arrives.
That gap widens as power scarcity gets worse. Reuters Breakingviews cited Morgan Stanley's earlier estimate of 68GW of demand against a 38GW supply gap. A more recent Morgan Stanley update, published September 21, raised the projected incremental US data center power demand for 2026 through 2028 to 97GW. Strip out capacity already under construction and grid power that can realistically be secured, and a primary gap of roughly 57GW remains. Even after accounting for workarounds such as gas generation, fuel cells, siting near nuclear plants and converted Bitcoin mining facilities, about 33GW of shortfall is left, by this calculation.
The numbers have shifted, but the direction is clearer than before. AI's bottleneck is no longer just chip supply. It is shifting to a time-to-power problem: when can electricity actually be delivered.
Key numbers on the power bottleneck
- Prior model: 68GW — projected US data center power demand, 2026-2028
- Prior model: 38GW — potential power gap versus expected supply
- Latest model: 33GW — estimated net shortfall from 97GW of demand, after accounting for workaround power sources
Why Bitcoin miners became AI's power landlords
Bitcoin mining was always an industry that hunted for cheap electricity, large tracts of land, big power intake capacity, substations and grid connections. When the AI boom hit, the power infrastructure miners had stacked up around their machines turned out to be worth more than the mining rigs themselves. Bernstein estimates that miners now hold or have planned roughly 14GW of power capacity.
Two strategies have emerged. Companies including Hut 8, Cipher Digital, and TeraWulf are moving toward a "powered shell" model, providing land, buildings, power connections and basic cooling infrastructure while customers supply their own GPUs. IREN instead chose a neocloud model, buying the GPUs itself and selling computing power directly to customers.
By revenue alone, the neocloud model looks bigger. Figures cited by Reuters show powered-shell annual revenue can reach up to roughly $2 million per megawatt, while neocloud contracts can approach roughly $10 million per megawatt. Yet enterprise value multiples against projected 2028 revenue tell a different story: about 15x for Hut 8, about 12x for Cipher Digital, and about 7.7x for TeraWulf, versus about 2x for IREN. The market appears to be pricing not just the size of revenue, but who absorbs the risk of technology depreciation to generate it.
| Model | Powered shell | Neocloud |
|---|---|---|
| Core asset | Land, buildings, power connection, cooling | Power infrastructure + GPUs + operating stack |
| GPU depreciation | Mostly borne by customer | Borne by the operator |
| Revenue potential (per Reuters) | Up to about $2M/MW per year | Up to about $10M/MW possible |
| Key to economics | Long-term lease rates and asset reusability | Utilization, compute pricing, GPU residual value |
Buying the GPUs yourself boosts revenue, but you keep the residual-value risk too
IREN's contract with Microsoft puts numbers on that difference. According to Reuters Breakingviews, the deal is worth $9.7 billion, including a 20% upfront payment. IREN must spend roughly $5.8 billion on AI chips and about $3 billion on other costs.
In Breakingviews' calculation, the project's internal rate of return comes out to about 12%, assuming the GPUs retain 25% of their initial value and the data center itself holds its value. If GPU residual value falls to 5%, that return drops to about 7%. If the data center's value per megawatt also declines sharply, it could fall to about 3%.
None of this means IREN made a bad bet. If GPU utilization and pricing stay high, an operator that runs its own chips can capture far more revenue and margin than a landlord collecting lease payments. But taking the upside also means taking on technology-cycle risk, utilization risk, financing risk and used-equipment value risk all at once.
A new real estate economics for AI infrastructure
This points to an important investing framework. In a fast-moving technology industry, the flashiest piece of equipment is not necessarily the scarcest asset over time. The asset that equipment absolutely requires, but that takes far longer to expand, can stay scarce much longer.
GPU supply can shift within a few years as Nvidia, AMD, TSMC and HBM makers add capacity and push through technical breakthroughs. Large transmission lines, substations, gas pipelines, generation, environmental permits, local community approval and grid interconnection take years to build. A site that can already reliably draw hundreds of megawatts is likely to stay useful through two or three more GPU generations.
That is why, when evaluating an AI data center, investors may want to look one step earlier than "how many GPUs did they order." What matters more is how many megawatts are under contract, how many of those are actually energized, what the power price and contract length look like, whether the tenant's credit is solid, and who carries the GPU capex and residual-value risk.
Insight Times Editorial Desk