Chips Are Sold Out, Stocks Were Dumped: The Week AI's Bill Arrived
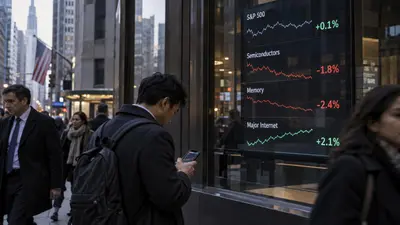
Last week's selloff appears to have questioned not AI demand but who pays for the buildout and who keeps the profit. Meta, Tesla and Lam Research report this week.
US stock market weekly outlook | October 19-23
1. What broke last week was market confidence, not AI demand
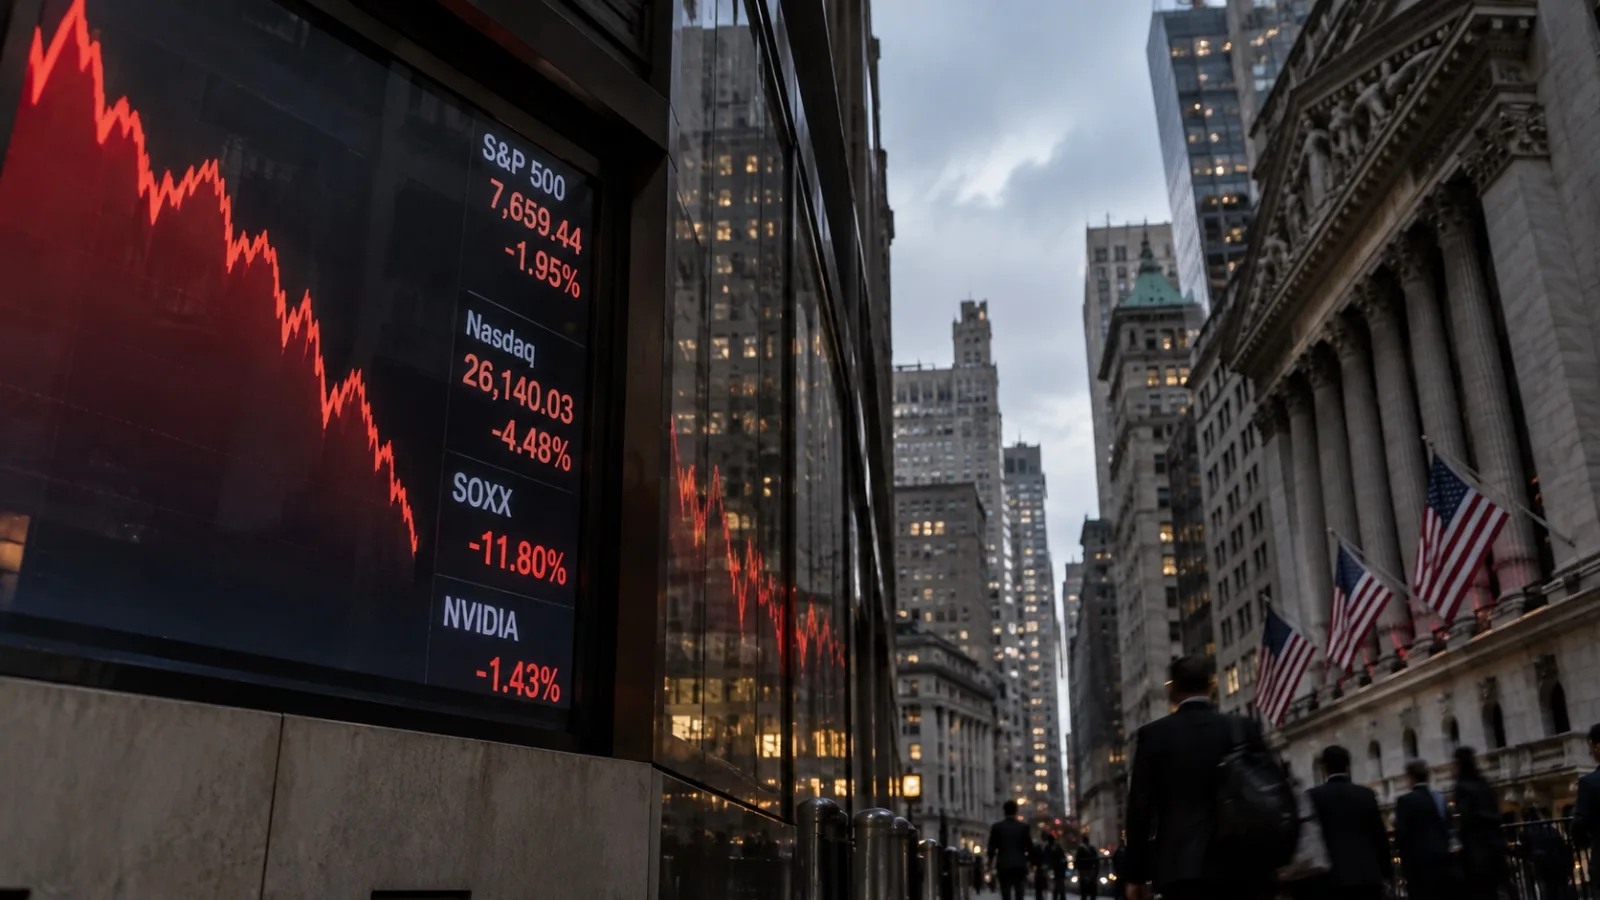
The S&P 500 closed at 7,659.44 on Friday, Oct. 16, and the Nasdaq at 26,140.03. For the week, they fell about 1.9% and 4.5%. The Dow rose about 0.7%.
| Index | Close | Week |
|---|---|---|
| S&P 500 | 7,659.44 | about -1.9% |
| Nasdaq | 26,140.03 | about -4.5% |
| Dow | n/a | +0.7% |
Selling centered on tech, but not every US company fell alike. The semiconductor ETF SOXX posted a double-digit weekly decline. Money moved toward sectors with less exposure to AI spending.
The earnings on the other side are the interesting part.
TSMC's third-quarter revenue was $46.72 billion, above the company's guidance. It forecasts fourth-quarter revenue of $52.3 billion to $54.3 billion. ASML also reported third-quarter revenue of 11.7 billion euros.
Results at the companies that make AI chips and the ones that supply the equipment remain solid. Yet the stock market has started to discount the future value of related companies.
That offers a clue to last week's drop.
Ample demand for AI is not the same as every company investing in AI earning enough profit.
2. CoreWeave's stress: who pays to build AI data centers
CoreWeave's five-year credit default swap (CDS) spread rose above 1,100 basis points last week. A CDS works like insurance against default. The higher the price, the greater the credit risk the market sees.
At one point, the yield on CoreWeave's bonds due 2031 climbed to 16%. For a company already paying high interest, that signals a tougher time raising new money or refinancing existing debt.
Funded by own cash flow: AI capex paid for with cash from existing businesses. Key risks: lower returns on investment and shrinking free cash flow.
Funded by borrowing: GPUs and data centers secured with outside debt, repaid later from usage fees. Key risks: interest burden, refinancing, utilization and customer concentration.
It is too early to read CoreWeave's credit stress as distress across the AI industry. A large backlog and Nvidia's support are important grounds for the business to continue. But a backlog does not turn into cash right away.
In AI infrastructure, two companies with the same demand may be valued very differently depending on how they are financed and what their contracts say.
3. Chinese memory, oil and rates added to the pressure
Progress by China's CXMT in server memory has prompted a fresh look at the long-term competitiveness of incumbent memory makers.
Still, intensifying competition in commodity DDR5 is not the same as the supply race in high-bandwidth memory (HBM) for AI. Each involves different hurdles: technical qualification, yields, advanced packaging and customer adoption.
China's catch-up is a medium- to long-term risk. Last week's price drop alone is not enough to say the HBM competitive picture has already changed.
On top of that came September US consumer price inflation of 3.7%, a 10-year Treasury yield above 5% and Brent crude near $110 a barrel. The 10-year yield was about 5.09% on Friday.
Higher yields raise borrowing costs. They also weigh on growth stocks, whose value rests on distant earnings.
Even if AI companies are really growing, the setting may lower what the market is willing to pay for that growth.
4. This week, Meta, Tesla and Lam Research have to answer
| Company / data | Timing (ET) | What to watch |
|---|---|---|
| Netflix, SpaceX | Tuesday, Oct. 20, after the close | Consumer demand; cash flow from space and communications |
| Meta | Wednesday, Oct. 21 | Ad revenue growth and AI capex efficiency |
| Tesla | Wednesday, Oct. 21 | Auto margins, FCF, energy business |
| Lam Research | Wednesday, Oct. 21 | Memory investment and equipment order outlook |
| Texas Instruments, IBM | Wednesday, Oct. 21 | Industrial chip recovery, enterprise IT demand |
| US October flash PMI | Friday, Oct. 23 | Manufacturing and services activity |
SpaceX separately announced it will report results after the US close on Oct. 20.
Meta is a test of the return on AI investment
The market is not checking the size of the capex itself. It wants to know how far recommendation algorithms, ad automation and enterprise AI translate into ad revenue and operating profit. If spending comes in larger than expected but the earnings case is clear, the assessment could change.
For Tesla, the earnings strength of the auto business matters
Third-quarter deliveries of 486,532 vehicles beat expectations but fell about 2.1% from a year earlier. Energy storage deployments were 13.7 GWh. With volumes confirmed, attention turns to pricing, costs, automotive gross margin and free cash flow.
The Roadster, robots and self-driving could affect long-term value. Technical possibility should be kept separate from profit that shows up in the accounts now.
Lam Research could show how durable the chip investment cycle is
After ASML's strong results, steady equipment orders and a held next-quarter revenue outlook could support the view that demand across the supply chain is solid. Weaker order guidance would add one more reason for caution.
5. What to watch
- Meta's revenue and capex outlook: whether AI spending keeps growing faster than profit.
- Lam Research's guidance: whether demand for memory and advanced chip equipment holds next quarter.
- CoreWeave's bond yields and CDS: whether credit stress eases or spreads to other AI infrastructure companies.
- The 10-year yield and oil: how much a prolonged 5%-plus yield and high oil weigh on earnings forecasts.
- Regular-session closes after earnings: whether real buying persists, rather than a brief after-hours reaction.
The Federal Open Market Committee meets Oct. 27-28. If this week's earnings test how efficiently individual companies invest, next week's Fed meeting is likely to gauge the financial conditions that investment will face.
Good technology can build a good industry. But not every company in a good industry is a good investment.
This week the US market is likely to revisit one question.
Not how big AI will get, but who takes the profit from that growth and who bears the cost.
Insight Times Editorial Desk