Micron's 87% Margin, 6x P/E: Memory's Re-Rating Will Be Decided in the Next Downturn
Record earnings alone will not erase the market's doubts. If memory has truly become contract-backed AI infrastructure, the proof will show up in the earnings trough of the next correction, not at the peak.
Earnings have gone well beyond "super boom"
Micron's fiscal fourth-quarter 2026 revenue was $54.229 billion, about 4.8 times the $11.315 billion a year earlier. GAAP net income was $37.70 billion and non-GAAP net income was $38.40 billion. Non-GAAP gross margin reached 87.0% and operating margin 82.3%.
| Metric | Figure | Note |
|---|---|---|
| FQ4 2026 revenue | $54.23B | +379% year over year |
| Non-GAAP gross margin | 87.0% | Far above the usual range for hardware manufacturing |
| FQ1 2027 revenue guidance | $61.5B | Above Wall Street's estimate of about $57.0B |
Cash flow is strong too. Adjusted free cash flow for fiscal 2026 was $62.31 billion. Year-end cash, marketable investments and restricted cash totaled $73.48 billion. Profit is not just rising on paper. Cash is actually piling up.
So why a P/E of 6?
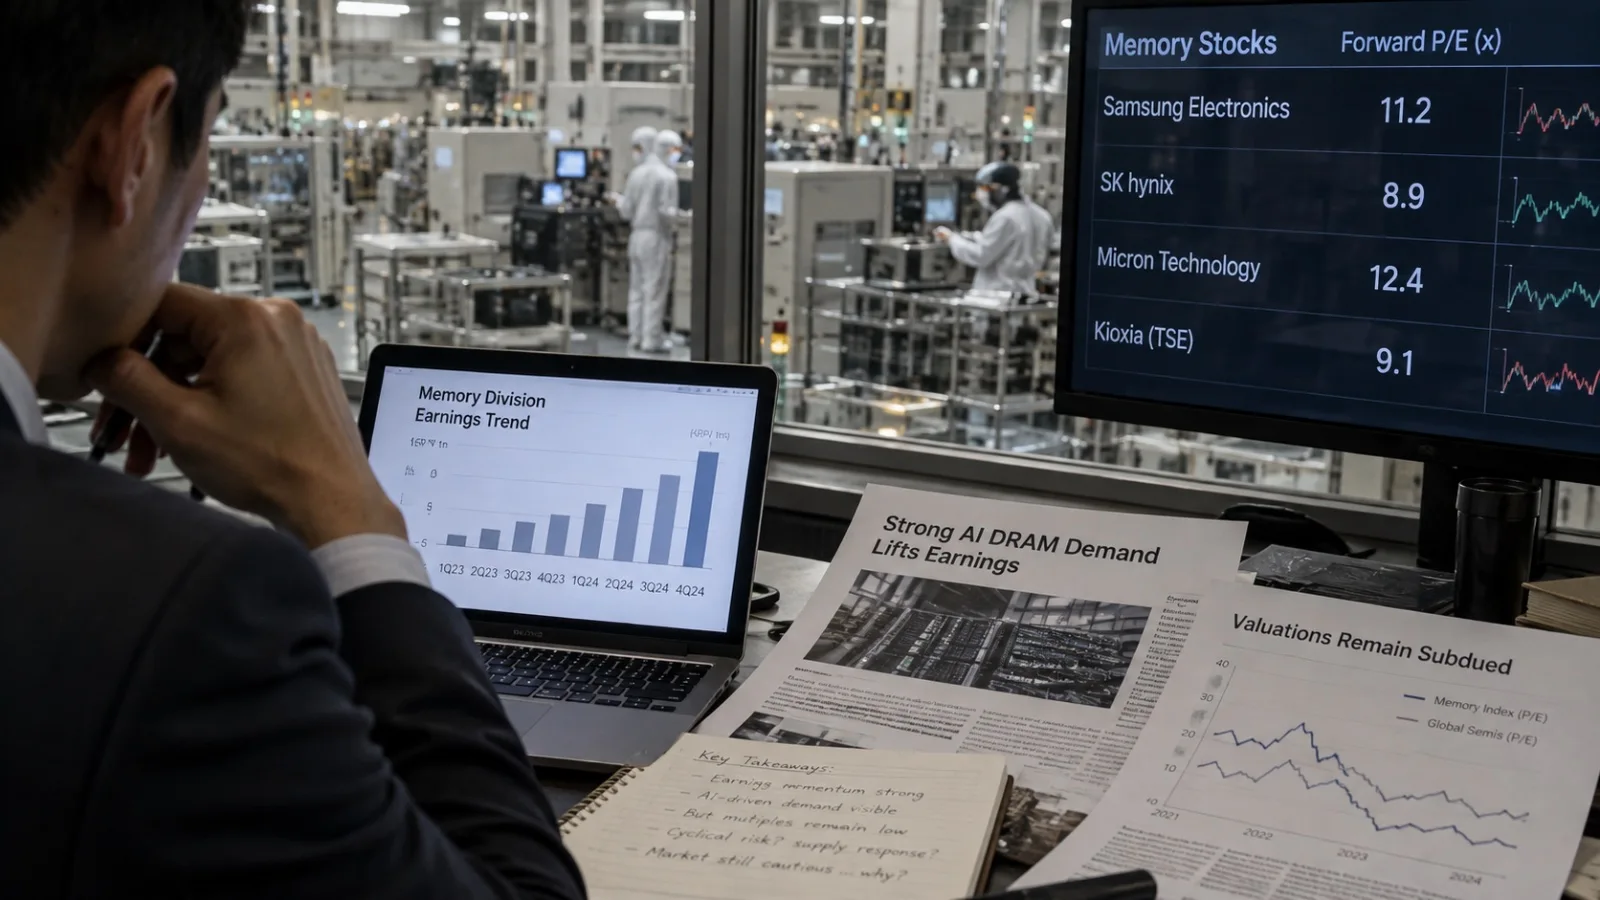
The short answer: the market does not yet believe an 87% gross margin will last. Based on public data, Micron's forward P/E is about 6.1. That looks cheap, but for cyclical stocks the P/E is often lowest when earnings peak.
The memory has a basis. In fiscal 2023, Micron posted a GAAP gross margin of -17.8% in the third quarter and -10.8% in the fourth. Adjusted free cash flow for fiscal 2023 was -$5.45 billion. Not long ago, memory was an industry where high fixed costs turned straight into losses once prices fell.
The second discount is AI infrastructure spending. Hyperscaler AI-related capital spending has grown to hundreds of billions of dollars in 2026, but the market is checking whether that spending turns into enough AI revenue and free cash flow. If end-customer returns fall short, new server and chip orders could be among the first items cut.
The third is supply. Micron plans about $25 billion of capex in the first half of fiscal 2027 alone, and new wafer capacity is due to come online gradually from mid-2027. It is hard to justify a high multiple on the assumption that today's shortage lasts forever.
Still, this cycle differs from the past
Skepticism can be reasonable without the industry structure being unchanged. The most important shift is long-term contracts. Micron's strategic customer agreements (SCAs) rose from 16 in the third quarter to 26 in the fourth, and cover more than 35% of expected revenue through 2030. Related customer cash deposits and financing commitments grew from $22 billion to $32 billion, and remaining performance obligations expanded from $100 billion to $150 billion.
The disclosed contract structure also differs from the past. Many contracts include multiyear purchase commitments and price floors. As of the third quarter, the company said the price floors in major SCAs were designed to support solid gross margins above the best quarterly margins of prior cycles. If that works in a real downturn, the way the memory sector is valued could change.
| Item | Memory in the past | AI memory today | What investors should read from it |
|---|---|---|---|
| Demand | PC and smartphone driven | AI data centers and growing high-bandwidth memory | More memory per unit |
| Contracts | Heavy on quarterly and spot deals | Multiyear SCAs, more price floors and purchase commitments | Revenue and margin visibility may improve |
| Supply | Fast ramps in commodity products | Bottlenecks in advanced process, stacking and packaging | Slower supply response |
| Risk | Channel inventory and price collapses | AI capex, ROI and new capacity | Risk has not vanished; it has changed shape |
Re-rating needs four proofs, not a 15x P/E
First, a margin floor in the next downturn. The 87% need not hold. What matters is whether gross margin again collapses below zero, or whether Micron keeps a structurally high positive margin.
Second, whether the SCAs actually bind. Investors need to see whether price floors and purchase commitments protect average selling prices and utilization when demand slows. More important than the contract text is the income statement in the first real downturn.
Third, capex discipline and free cash flow. If the shortage sparks another round of overheated investment, the re-rating case weakens. If revenue grows while expansion stays controlled and free cash flow holds, the old discount for an industry that burns cash in good times could shrink.
Fourth, broader AI demand. High-capacity memory demand must spread beyond training GPU clusters to inference, agents, autos and edge devices. That would reduce reliance on any one hyperscaler's capex cycle.
Bottom line: Micron is likely cheap because of the market's memory of the next downturn, more than because of today's earnings.
Insight Times Editorial Desk