You Only Need to Win 54% of the Points to Beat the Market
A good investor is not the one who calls every move correctly. It is the one who survives the days they get it wrong, long enough to keep playing a game tilted in their favor.
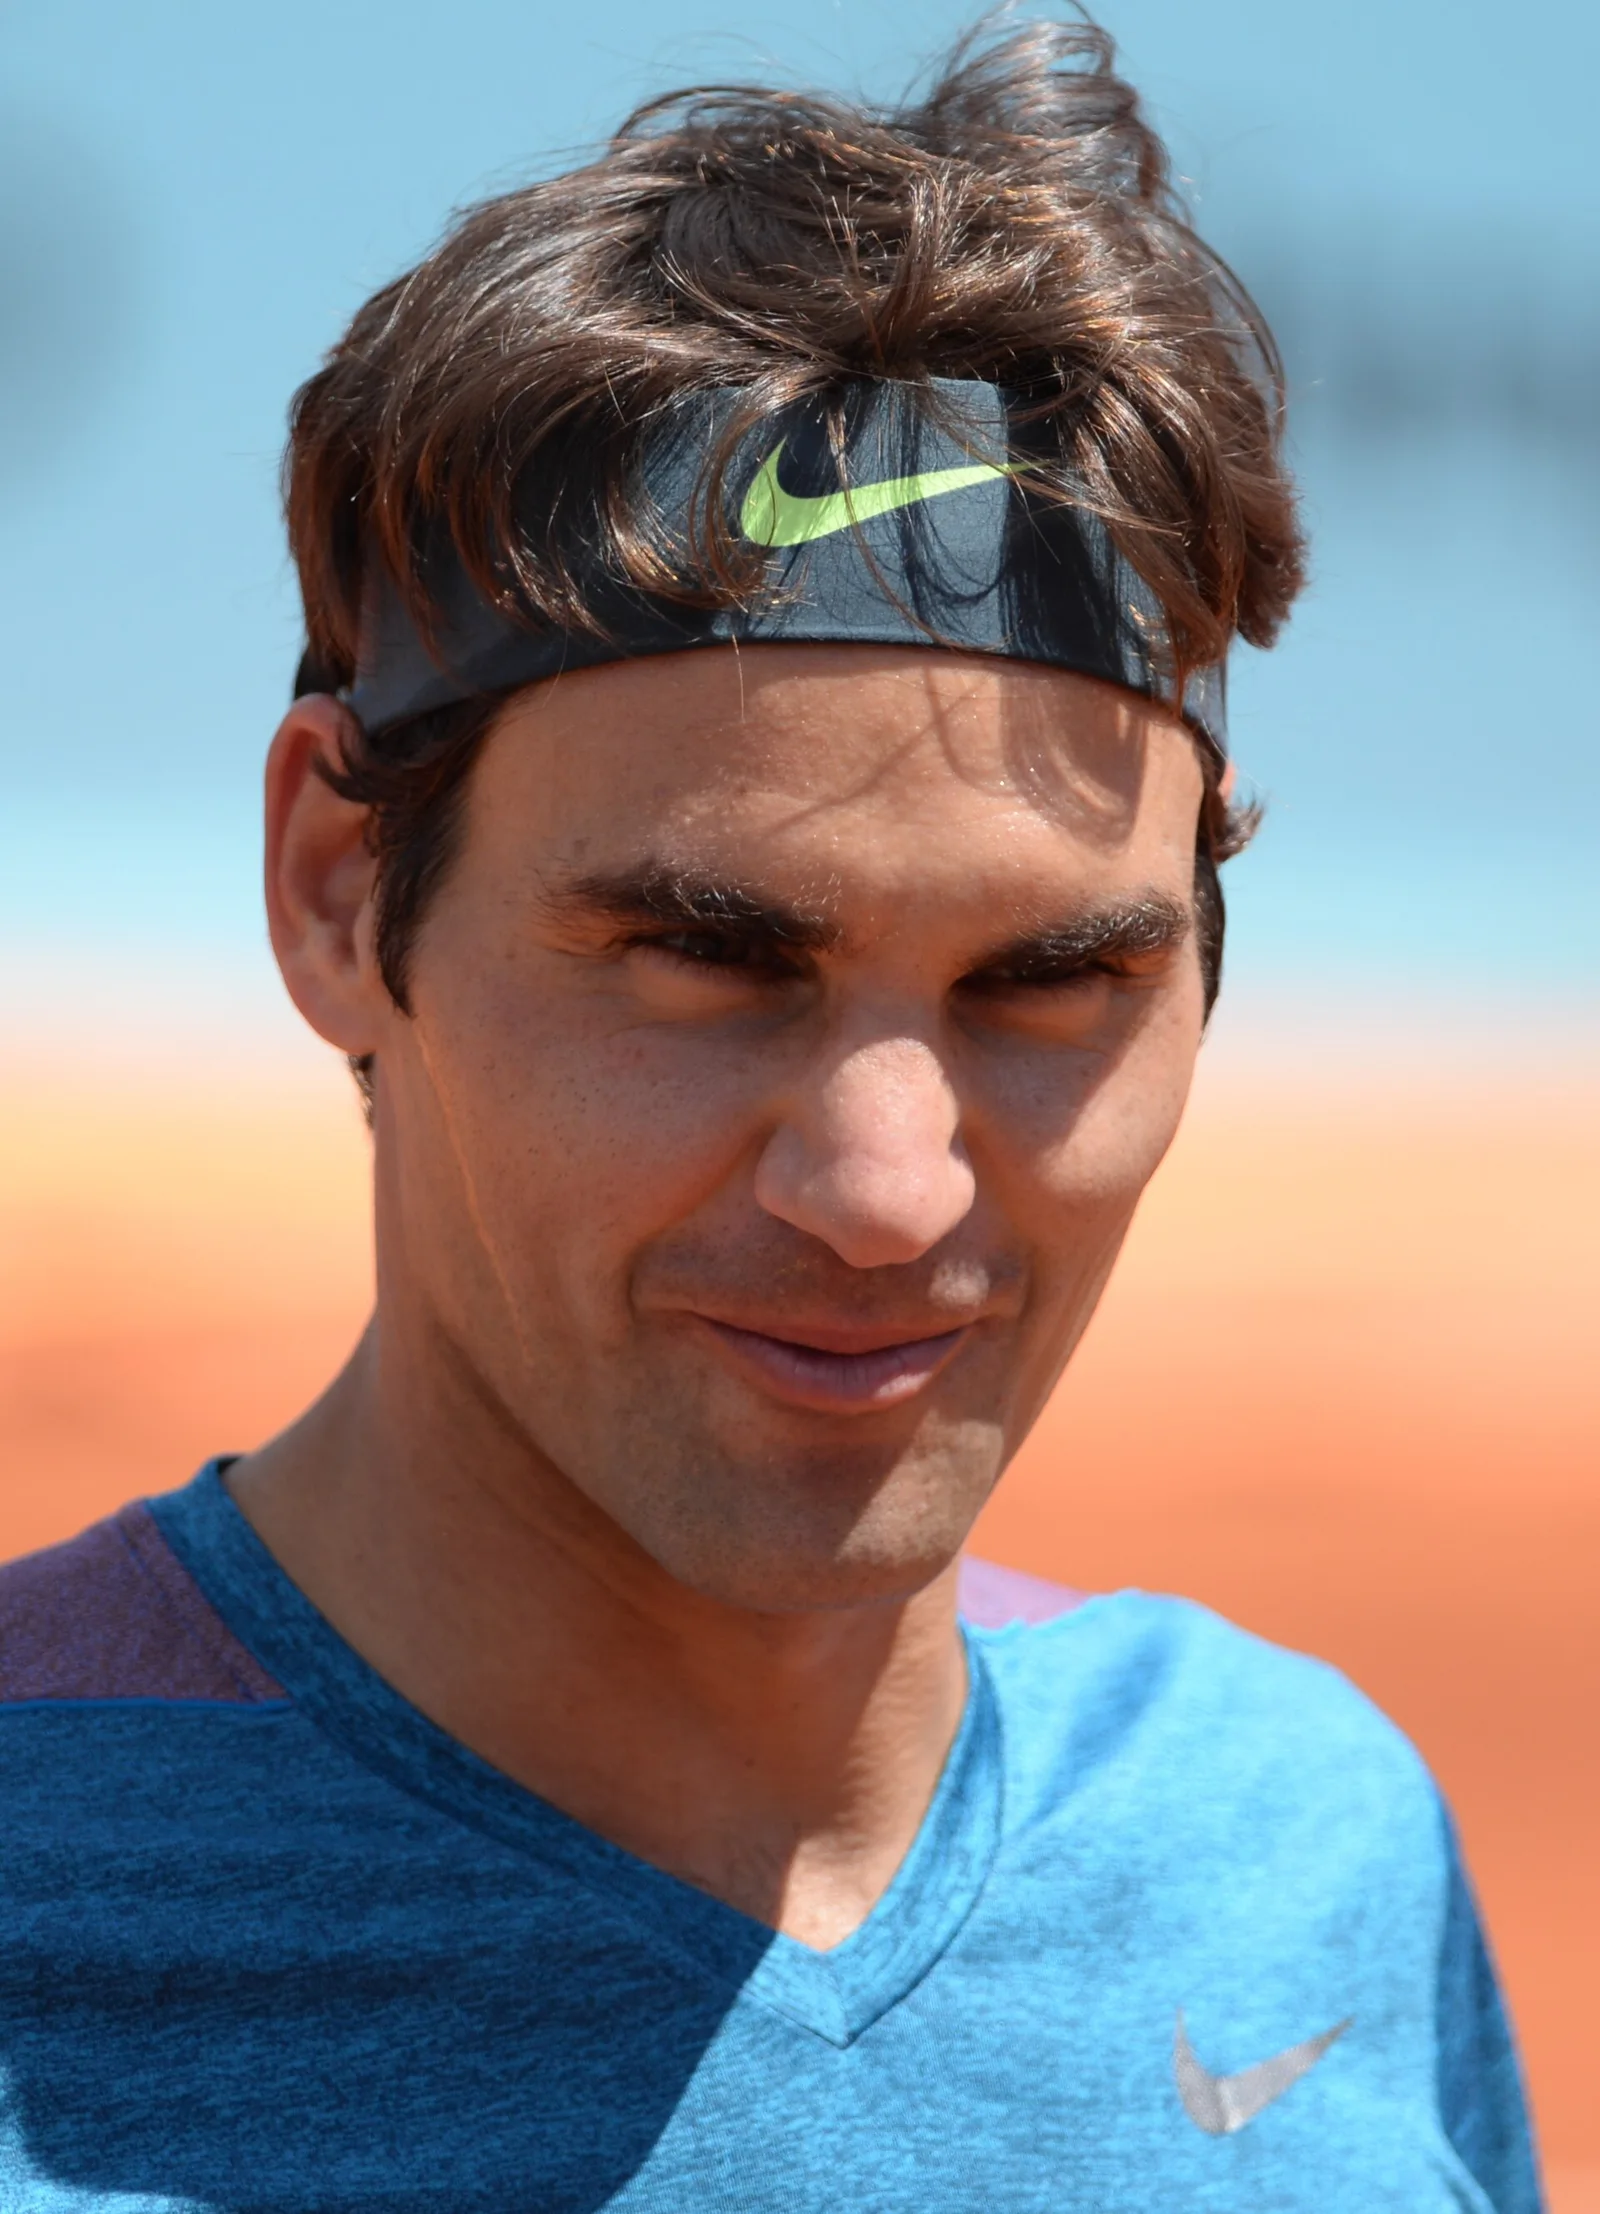
Federer Lost 46% of His Points and Still Became One of the Greatest
At Dartmouth's 2024 commencement, Roger Federer shared an odd number. Across his 1,526 professional matches, he won nearly 80% of them. But when you count individual points, he won only 54%.
That number describes the mindset of a long-term investor better than most finance textbooks.
Even the greatest players lose almost half their points. What matters is not winning every point. It is refusing to carry one bad point into the next. In Federer's words, a lost point is "just a point."
Investing works the same way. A stock can fall the day after you buy it. You can misread an earnings report. You can pay too much for a good company. The entire market can drop 20%, 30%, or more.
The problem is never the loss itself. It is the moment an investor throws out an entire strategy because of one bad stretch.
What Markets Reward Is Not Certainty. It Is an Edge
No investor knows the future for certain. Nobody does. What an investor can have instead of certainty is a probabilistic edge.
Looked at day by day, the US stock market moves more often than people assume. Over long stretches of history, the share of up days is only a bit above half. Taken one day at a time, this is not an overwhelming game.
Stretch the timeline out, though, and the picture changes. Companies earn profits, raise productivity, pay dividends, buy back shares, and successful firms grow into a larger share of the index while weaker firms get dropped from it. The long-term upward drift of America's benchmark indexes reflects both corporate earnings growth and this self-cleaning mechanism built into the index itself.
So the question that matters for a long-term investor is not "will it go up tomorrow?"
Once an investor can answer yes for an asset, the skill that matters most shifts from forecasting to repetition.
What Twenty Years of Data Says, and What It Does Not
Looking at the history of US large-cap stocks, the longer the holding period, the smaller the share of periods that end in a loss. Hartford Funds compiled long-run data through the end of 2025 and found that every 20-year rolling return for US stocks in its sample came in positive.
That statistic is powerful. But it needs to be stated carefully.
It is not a law that says "hold for 20 years and you can never lose." It is an observed result from a specific stretch of US market history. Wars, policy shifts, valuations, taxes, inflation, and the monetary system are not guaranteed to repeat in exactly the same way going forward.
Even so, the message for investors is clear. The longer the time horizon, the less likely it is that one day's headline, one recession, or one rate shock ends up dominating a portfolio's final outcome.
Time is not a magic trick that erases risk. But for an investor holding good assets, it is one of the strongest tools available for diluting short-term noise.
The Real Value of Dollar-Cost Averaging Is Not a Lower Average Price. It Is Discipline
Dollar-cost averaging, or DCA, means investing a fixed amount at regular intervals. It buys fewer shares when prices are high and more shares when prices are low.
Mathematically, investing the same dollar amount repeatedly produces an average cost that behaves like a harmonic mean of the prices at each point in time. That comes out lower than a simple arithmetic average of those prices. This part of the math is straightforward.
But one distinction matters here. A lower average purchase price does not automatically guarantee a higher final return.
For someone who already holds a lump sum, investing it all at once has historically won more often than spreading it out. Research from Vanguard found that lump-sum investing beat dollar-cost averaging in roughly two-thirds of the periods studied. Because markets spend more time rising than falling over the long run, sitting in cash while waiting to invest carries its own opportunity cost.
So why does DCA still matter?
Most people never receive a lump sum to invest in the first place. They get a paycheck, earn business income, and find leftover cash each month. And, more importantly, people are bad at handling losses.
When the market is down 30%, deciding "I'll buy the same amount again this month" is harder than it sounds. DCA automates that decision in advance. Its biggest value is not predicting prices. It is making an investor's own behavior predictable.
A Bear Market Is Where an Investment Philosophy Gets Tested
Talking about long-term investing is easy in a bull market. When an account hits a new high every month, everyone is a long-term investor.
The real test starts in a bear market.
Can an investor stick to their own system when a good company's stock seems to fall for no reason, when the economic headlines get worse every day, when everyone around them says cash is king, and when years of gains disappear in a matter of months?
What is needed here is not optimism. The belief that "it always goes up eventually" is closer to faith than to an investment philosophy.
What is needed is a checkable set of principles. Has the company's long-term earning power actually been damaged? Is the index's structural growth engine still intact? Are living expenses and an emergency fund secured? Is there a risk of forced selling from leverage?
If those conditions hold, a downturn can be a time of fear and, at the same time, a chance to buy the seeds of future returns at a lower price.
Four Lines for a Long-Term Investor to Remember
<div class="grid"> <div class="metric"><strong>1</strong><span>You do not need to win every point.</span></div> <div class="metric"><strong>2</strong><span>Repeat a small probabilistic edge on good assets, for a long time.</span></div> <div class="metric"><strong>3</strong><span>DCA is not a return-boosting trick. It is behavioral discipline.</span></div> <div class="metric"><strong>4</strong><span>The most important input into compounding is time.</span></div> </div>
An investor does not need to be right every single day. In fact, the desire to be right every day is often exactly what ruins long-term returns.
A day the market crashes is just one point. A day you miss a new high is just one point. A day you bought too early is just one point.
What matters is staying on the court long enough to play the next one.
Pick good assets, invest at a size you can actually handle, add capital on a regular schedule, avoid extreme leverage, and give the whole thing enough time.
Seen that way, long-term investing looks less like a game of prediction and more like a game of survival.
You only need to win 54% of the points. The catch is you have to be able to repeat that 54% for decades.