Why 6% Is the Line to Watch as Wall Street Splits Between Index Gains and Real Pain

The S&P 500 is near its record high, but the average stock is much weaker. The 10-year yield has climbed to 5.17%. The real risk now is not the yield level alone, but whether narrowing breadth and stress in credit markets start moving together.
The index looks strong. Your portfolio might not

Right now, the US stock market is less a story of broad corporate strength and more a story of investors paying up for a small group of mega-cap, high-growth companies that can withstand higher rates.

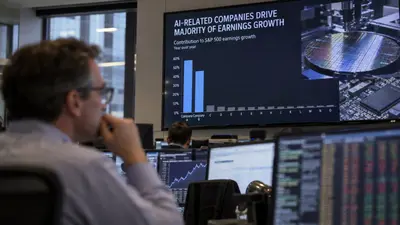
On September 21, the S&P 500 came within 0.4% of a record close. But RSP, the ETF that holds the same 500 stocks at equal weight, sat 4.6% below its own all-time high. The Russell 2000, a proxy for smaller companies, was 6.6% away from its prior peak on the same day. Separately, more than half of the S&P 500's constituents were down more than 20% from their individual record highs.

Market breadth chart

<div class="metrics"> <div class="metric"><div class="big">5.17%</div><div class="label">10-year Treasury yield, closing level on September 25</div></div> <div class="metric"><div class="big">4.6%</div><div class="label">Equal-weight S&P 500 ETF's distance from its all-time high, September 21</div></div> <div class="metric"><div class="big">2.73%</div><div class="label">US high-yield OAS on September 23, still below its long-term average</div></div> </div>

This gap is not a statistical curiosity. In a cap-weighted index, moves in giants like Microsoft, Apple and Nvidia carry far more weight. An equal-weight index instead shows how the "average" S&P 500 company is really doing. That difference explains why the headline index and an investor's actual portfolio can feel like they belong to two different markets.

What a 5.17% 10-year yield really reprices is the cost of money, not just stock prices

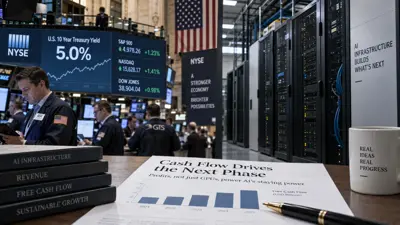
The 10-year Treasury yield closed at 5.17% on September 25. Intraday, it touched roughly 5.20%, a 19-year high. The 30-year yield rose to around 5.51% intraday. Strong corporate capital spending and resilient economic data have fed worries that rates could climb further.

Long-term yields serve as the discount rate for stocks and as the funding benchmark for the entire economy. When yields rise, distant future cash flows get discounted more heavily, and at the same time refinancing costs climb for mortgages, corporate bonds, private credit and commercial real estate.

$100 in cash flow five years from now is worth about $68 at an 8% discount rate, but only about $62 at 10%. Even if earnings forecasts stay the same, the price investors are willing to pay for them falls.

That is why the first hit usually lands not on cash-rich mega-caps but on debt-dependent companies and rate-sensitive sectors. Once credit spreads start to widen, the nature of the problem changes. Higher rates stop being just a valuation headache and start raising actual default risk and funding risk.

6% is not a collapse line. It's a stress test

Ed Yardeni has read the 10-year yield near 5% as a signal of confidence in a strong economy, while saying he would grow more concerned if yields moved quickly toward 6%. The number 6.00% itself is not the point.

As of September 23, the ICE BofA US High Yield Option-Adjusted Spread (OAS) stood at 2.73%, well below its long-term average of 5.16%. In other words, Treasury yields have jumped, but so far the corporate bond market has not priced in a broad credit crisis.

That distinction matters for how investors should read the market. Weakness in high-yield ETF prices alone should not be taken as proof that credit risk is spreading. When Treasury yields rise, the base rate underlying corporate bonds rises too, which can push bond prices down on its own. To actually gauge credit stress, investors need to watch the OAS, the extra compensation over Treasuries, rather than the price of an ETF like HYG alone.

Observed combinationInterpretationThe more important question
Treasury yields rise + OAS stableMay reflect strong growth, inflation, or higher real ratesAre corporate earnings offsetting the higher discount rate?
Treasury yields rise + OAS widensSignals funding pressure spilling into credit riskIs default risk building among companies with refinancing needs?
Yields rise + breadth deterioratesGrowing reliance on mega-capsCould an earnings miss from a few leaders shake the whole index?
Yields rise + OAS widens + breadth deterioratesThe combination to watch most closelyIs a price correction turning into a credit event?

For the bull case to hold, earnings growth has to outrun rates

Higher rates alone do not mean a bear market. If nominal growth stays strong and corporate earnings grow fast enough, that can offset a higher discount rate. The same logic applies to AI infrastructure spending. The size of capital expenditure is not the risk by itself, what matters is how quickly that spending turns into cloud, advertising, software and semiconductor revenue, and ultimately into free cash flow.

The bull case for this market can be compressed into two conditions. The US economy needs to be strong enough to absorb a long-term yield near 5%, and AI leaders need to keep growing earnings fast enough to justify their valuations. If either one breaks, today's narrow market breadth turns from a curiosity into a real vulnerability.

US stocks are not near a crash, but a shrinking group of mega-cap winners is now carrying a market where most other stocks have lost momentum.

Insight Times Editorial Desk

More by topic

Starting with this story's topics, then what readers are following now

Investor psychology, decision-making and books on investing

Fed

This story's topic24 storiesSee all →

The central bank of the United States, carrying a dual mandate — stable prices…

Gas Prices, Not Politics, Are Deciding This Midterm Market Story

Forecasts of a Republican defeat are not exaggerated. The House has tilted clearly toward Democrats, the Senate has moved from a toss-up to a slight Democratic edge, and Trump's net approval is the lowest of either term.

Macro

Why a Wobbly Yen Carry Trade Hits US AI Stocks First

It is not just dollar-yen at 160. Watch the US-Japan rate gap, yen direction, volatility, and US long-term rates together, because AI and high-valuation growth stocks get squeezed first when all four move at once.

Macro

Who Buys the T-Bill Behind Your $1 Stablecoin

Stablecoins aren't a crypto asset class so much as new plumbing for moving dollars online, and every new dollar that flows in gets tied to short-term Treasuries.

Macro

It's Not Just Hormuz: Why the Middle East War Is Becoming a Fed Problem Again

The US-Iran ceasefire has already collapsed, and the risk no longer sits in the Gulf alone. With the Red Sea and Saudi Arabia's bypass pipeline now under threat too, an energy shock is spreading into prices, the Fed, and growth-stock valuations.
Macro

Weekly Check: The AI Bull Market Isn't Over, It's Just Gotten Harder

A 5% 10-year yield, 470 gigawatts stacked up in Texas, Chinese DRAM, and whether data centers actually get switched on are starting to decide who wins the AI trade through 2027.

Tech

Rates Hit 5% Again, But AI Held - Now Wall Street Wants Cash Flow, Not Just GPUs

The Fed raised rates and the 10-year yield broke back above 5%, yet the Nasdaq did not crack. This week's real story is not the end of the AI rally but a change in what the market is grading.

Investing

The AI Supercycle Now Favors Companies That Earn Money, Not Just Spend It

The S&P 500 is up 14.1% this year even with the 10-year Treasury yield near 5.24%. What happens next may depend on how much of the AI spending comes back as profit and cash.

Investing

HBM

77 storiesSee all →

Memory stacked next to the GPU.

Memory Is Still Short, but Less Short: Checking for the Peak This Week

Citi trimmed its 2027 DRAM and NAND shortage forecasts together. Server pricing remains strong, while consumer markets show weakness. This week's numbers show where the memory boom may peak.

Investing

The Real ASML Number Isn't the 3% Pop, It's the 30% Capacity Hike

ASML's rally isn't just an AI trade. Customers are already locking in 2027 tool slots, and ASML is raising Low-NA EUV capacity by roughly 30% to keep up.

Investing

A 3x P/E is not a discount. It is a verdict on how long memory profits last

Nomura's buy case on Samsung Electronics and SK Hynix does not stop at higher memory prices. It argues that if AI has turned memory from a cyclical component into strategic infrastructure, the formula the market uses to value both companies has to change too.

Investing

2027 Isn't the End: Citi's Case for a Memory Supercycle Running to 2031

Citi says the memory shortage timeline is stretching again. If AI shifts from "train once" models to continual learning, HBM, server DRAM and enterprise SSDs could all fall short at the same time.

Tech

AI ran out of memory before it ran out of GPUs

The HBM bottleneck is spreading into DRAM prices, server costs and the price of the next laptop or phone.

Tech

Has Memory Peaked? Prices Are Cooling, but the Shortage Looks Set to Run to 2028

Price growth has slowed and consumer demand is already breaking. Server and HBM supply remains short, and Micron says more than 75% of its 2027 volume is already committed to customers.

Tech

AI Chip Peak Check: Demand Still Rising, Risk Building in 2027-2029 Supply and Funding

DRAM and NAND contract prices are still climbing and HBM suppliers hold the edge. Power shortages, AI financing costs and simultaneous memory expansion are the risks for later years.

Investing

A building that houses servers and networking gear and supplies them with powe…

Nvidia and Palantir Put AI Inside the Supply Chain - The Real Shift Is That It's Learning Judgment

A single Vera Rubin rack holds 1.3 million parts. The real breakthrough in Nvidia and Palantir's new supply chain AI isn't automating that complexity, it's capturing the judgment calls that used to live only in planners' heads.

Tech

Is Space Cooler for AI? Why Musk Wants Data Centers in Orbit

The next limit on AI may be power and cooling, not GPUs. Elon Musk is looking to Earth orbit for an answer, but the test is cost per hour of compute.

Tech

Musk Sees the Next Phase of AI Infrastructure: Who Can Switch GPUs On, Fast

If neoclouds struggle under financial pressure, AI demand may not shrink. It may simply favor the few operators with the capital and execution to serve it, a shift that could matter for SpaceX and Tesla.

Tech

White House Swaps AI for "SI." The Real Investment Signal Is Infrastructure, Not the Name

An executive order renames artificial intelligence "Super Intelligence" and six frontier labs sign a voluntary safety accord. What investors should watch is the data center, power, nuclear and chip policy now gathered under one national-competitiveness frame.

Tech

The Cheaper Tokens Get, the Bigger Your AI Bill Gets

As AI shifts from training to inference, the token is becoming an industrial commodity. Falling prices are not cutting demand, because agents and automation consume tokens at a scale no human chat session ever did.

Investing

Marvell's $115 Billion Lumentum Deal: Is AI's Next Bottleneck Light, Not Chips?

Marvell's purchase of Lumentum points to a contest beyond GPU speed, in data transfer and power efficiency. Whether the price is right is not yet confirmed.

Tech

Workers in hard hats beside a communications equipment cabin, with a Starship rocket on its launch tower at dusk in the background

SpaceX Forecast at About $730 Billion in 2028 Revenue: The Bigger Opportunity Musk Sees

Sequoia Capital made a bold forecast, and Elon Musk replied, "I think we can do better." The future SpaceX is looking at is far bigger than the rocket launch business. The plan is to link satellite communications, AI data centers and orbital computing into one giant business.

TechEXPLAIN

NVDA

96 storiesSee all →

Who Hits $1 Trillion Next: Reading AMD and ASML by Different Rules

One company is chasing Nvidia's GPU empire. The other sells the machine that draws the chips for every advanced chipmaker, including Nvidia. Both get floated as 2028 trillion-dollar candidates, but the numbers investors need to watch are entirely different.

Investing