TSMC Proved the AI Chip Boom Again. So Why Did the Stock Fall?
Third-quarter results beat expectations and fourth-quarter growth is guided higher. Investors should separate the substance of the AI investment cycle from market anxiety.
The numbers say boom. The stock says worry.
TSMC's third-quarter report on Oct. 15 held the evidence AI chip investors had been waiting for.
Revenue beat market expectations. It also beat the company's own target. The outlook for the next quarter was stronger still. Yet TSMC shares fell about 2% in Taiwan.
So which signal should investors believe?
Start with the results.
| Metric | Result |
|---|---|
| Revenue (USD) | $46.72 billion |
| Revenue growth (USD) | +41.2% YoY, +16.2% QoQ |
| Net income | NT$763.06 billion |
| Net income growth | +68.7% YoY |
| US ADR earnings per share | $4.60 |
| Gross margin | 66.4% |
| Operating margin | 58.7% |
| Q4 revenue guidance | $52.3 billion to $54.3 billion |
| 2026 USD revenue growth outlook | About +44% |
| 2026 capital spending plan | $60 billion to $64 billion |
The key point: revenue of $46.72 billion came in about 2% above the top of the company's own guidance range of $44.6 billion to $45.8 billion.
Beating consensus is good. But demand running ahead of a company's internal production and revenue plans matters more.
The midpoint of Q4 guidance is $53.3 billion, roughly 14.1% above the third quarter. Demand is not cooling into year-end. The picture is one more step up.
One caution: USD revenue growth is 41.2%, while growth in Taiwan dollars is 50.9%. Exchange rates explain the gap, and growth rates in different currencies should not be mixed.
The strongest line on the earnings call
CEO C.C. Wei said there are no signs of an AI demand slowdown.
TSMC has previously guided to a compound annual growth rate for AI accelerator revenue in the mid-to-high 50s percent range for 2024 to 2029. This time it suggested growth could run higher.
That is a meaningful shift.
Growth of 55% a year for five years means a market about 9 times larger. At 60%, it is about 10.5 times. Small differences in growth rates compound into large differences in market size.
Still, the CEO did not formally raise the official growth forecast. The more accurate reading is that he is quite optimistic about future demand.
The hidden story: AI chip growth is not only about GPUs
The most interesting part of the call was how the AI market is defined.
The AI accelerator revenue TSMC uses in its growth forecast centers on GPUs and AI ASICs. CPUs used in AI servers are not included. The reason is simple: TSMC cannot reliably tell whether the same CPU ends up in a general-purpose server or an AI server.
The problem is that the way AI is used is changing.
As AI moves from chatbots answering one question at a time to agentic AI handling many tasks in sequence, data movement between CPUs and the network matters as much as the GPU.
That matters for Nvidia, but also for AMD, Broadcom, and Google and Amazon, which design their own AI chips. As the AI market grows, competitiveness depends not only on a single chip but on compute efficiency across the whole data center.
None of this means every chip company's profits will rise at the same rate. Competition, pricing and in-house design will decide who benefits.
- GPU / AI ASIC: AI compute and inference
- CPU: task control and execution
- Networking: large-scale data movement
- Advanced packaging: high-speed connection of multiple chips
The range of real AI-related chip demand is wider than what TSMC's AI accelerator growth rate captures.
Customers are already planning for 2027 and beyond
TSMC's 2-nanometer process, N2, made up 8% of total wafer revenue in the third quarter, up quickly from 3% the previous quarter.
Investors should read more than a simple process transition into this.
Leading-edge chips take a long time to go from design to volume production. When a large customer commits to a next-generation process, it already has products in mind that will launch years from now.
TSMC plans to more than double annual N2-family capacity in 2027. The following node, A14, is being prepared for trial production in 2027 and volume production in 2028.
Another bottleneck is advanced packaging, including CoWoS. AI chips must connect HBM and make many chips work as a single system, not just provide compute.
TSMC said it is producing packages at 5 times the reticle size in volume while developing 9 times and 14 times versions.
In short, customers want bigger AI chips, and TSMC is investing in the process and packaging needed to build and connect them.
Is the margin decline a bad sign?
Third-quarter gross margin was 66.4%, down 1.3 percentage points from 67.7% in the prior quarter.
On its face, that looks like weaker profitability. But the main cause is early N2 production cost. New processes run at low volume and high initial cost, which squeezes profitability.
Overseas fab expansion is another drag. TSMC said overseas production could dilute gross margin by 3 to 4 percentage points over time.
So it is a stretch to read the current margin decline as weaker demand.
The opposite assumption is also risky: that heavy capital spending is automatically good. If this year's $60 billion to $64 billion in capex is not recovered through future revenue and cash flow, a heavy depreciation burden remains.
What investors need to check is not capacity growth itself but whether the added capacity earns enough profit.
Why did the market sell anyway?
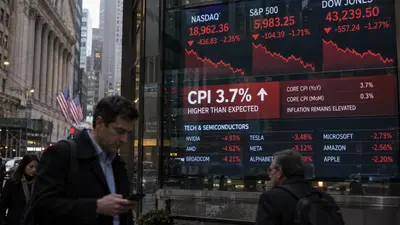
September CPI, released in the US on Oct. 14, rose 3.7% from a year earlier, above the 3.6% forecast. Bond yields rose, and selling pressure built across AI and tech stocks.
The CPI shock came before TSMC's Oct. 15 report. One data point therefore cannot fully explain the weakness after the results, but it was an important backdrop weighing on sentiment.
Stock prices are not set by earnings alone. How much investors pay for future earnings, the valuation, also matters.
When rates rise, the present value of future cash flows falls. Stocks with a lot of long-term growth priced in feel that most.
Layered on top are worries about hyperscalers' returns on AI spending, data center power shortages and borrowing costs.
TSMC showed that demand for AI chips is strong. It did not prove that every company buying those chips will earn an adequate return on the investment.
Four things to watch
- Q4 revenue of $53.3 billion: Check whether actual revenue reaches the guidance midpoint. A further beat would be evidence of strong order flow.
- Gross margin of 65% to 67%: This is the Q4 guidance range, reflecting N2 ramp-up and overseas fab costs. Sustained readings below it would call for revisiting profitability assumptions.
- N2 and CoWoS shipment growth: Check whether announced expansion plans turn into actual shipments and revenue.
- Hyperscaler capex and cash flow: Check whether large cloud companies keep raising AI investment, and whether that spending erodes operating cash flow too much.
What TSMC showed is not proof that the AI future will necessarily succeed. It is evidence that, at least on the chipmaking floor, orders and investment to prepare for that future remain strong.
Investors should not confuse the two.
The market's fear should not be ignored. But one day's share drop is not a reason to discard the evidence of long-term growth.
Insight Times Editorial Desk