Anthropic Posts a Profit, but Investors Are Uneasy About the $2 Trillion Question
Reported third-quarter revenue of $16.8 billion and an adjusted profit show AI can make money. Slowing growth and $518 billion in long-term commitments are the open questions.
20-second briefing
- Evidence that AI can make money. Third-quarter revenue was $16.8 billion, up about 45% from the prior quarter. Reports also cite a second straight quarter of adjusted profit and $1.70 of revenue for every $1 of compute cost.
- Growth has not stopped. Expectations were simply very high. Quarterly growth slowed from about 145% to 45%. Large customers moving to their own models and price competition are weighing on results.
- The real risk is $518 billion in long-term commitments. Reports put AI infrastructure commitments over the next 10 years at about $518 billion. Roughly 80% is said to be hard to cancel or to carry payment obligations regardless of usage.
Anthropic is profitable. Why is a $2 trillion valuation wobbling?
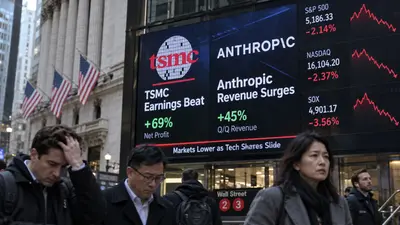
Anthropic has handed investors an impressive report card. Third-quarter revenue was $16.8 billion, according to figures reported from a private investor briefing on Oct. 14, 2026. That is about 3.7 times the company's full-year 2025 revenue of $4.6 billion, earned in just three months.
The bigger change is profitability. Revenue per dollar of compute cost reportedly improved from about $0.63 in 2025 to $1.70. The same compute spending now generates roughly 2.7 times as much revenue.
Adjusted operating margin for the first three quarters of 2026 was reported at 11%. That is not the third-quarter margin alone. Still, it suggests an AI model developer can expand revenue and reach an adjusted profit at the same time.
Investor reaction is not purely positive, though. Some observers say expectations for an IPO valuation of $2 trillion are drifting toward about $1.5 trillion. The bar for AI companies has changed.
1. Revenue of $16.8 billion is strong, but the pace of growth is the issue
Quarterly revenue, $ billions
| Quarter | Revenue | QoQ |
|---|---|---|
| Q1 2026 | 4.8 | n/a |
| Q2 2026 | 11.6 | +141.7% |
| Q3 2026 | 16.8 | +44.8% |
Figures come from reports on the private-company investor briefing and are distinct from audited financial statements.
Revenue keeps rising, but the rate of increase has dropped sharply. Several factors appear to be at work: large customers shifting to their own AI models, a block on improper API use that helped train competitors' models, and falling prices per token.
According to some reports, demand used for model distillation made up 5% to 7% of past revenue. Restricting it may have weighed on near-term sales. Even so, 45% growth is still high. The key question is whether this is a temporary change in the customer mix or a structural change driven by price competition.
2. $1.70 of revenue per compute dollar: is the money real?
Revenue per $1 of compute cost
- 2025: $0.63
- Latest reported: $1.70
Revenue efficiency improved about 2.7 times. This does not measure overall company margin or return on invested capital.
The number invites a fresh look at Anthropic's business model. It can be read as the result of optimizing the inference costs incurred when customers call AI through the API, and of earning more revenue from the same compute.
The enterprise API business matters most. When customers wire Claude into real work, usage can grow. If performance and price stay competitive, recurring revenue is a reasonable expectation.
But adjusted profit is not the same as cash returned to shareholders. Adjusted operating income can exclude significant costs such as stock-based compensation. Once the cost of training new models and long-term infrastructure spending are included, true economic profitability may look different. It is too early to say that sustained free cash flow has been demonstrated.
3. $518 billion in commitments: a growth engine and a risk
Compute and infrastructure commitments over 10 years: $518 billion
Reports say about 80% is non-cancelable or carries payment obligations regardless of usage. Terms by contract and the timing of cash outlays need separate verification.
Long-term compute commitments secure supply ahead of demand growth. They also become a heavy burden if future demand falls short. If customers move to their own models and usage drops while contracted costs must still be paid, the hit to profit could be far larger than the hit to revenue.
For infrastructure companies such as Amazon, Google, Broadcom and Microsoft, long-term contracts improve visibility into future revenue. But a contract does not remove the risk of data center construction delays, power shortages or a customer's weak finances.
It also matters that $518 billion is the total of commitments over a long period. It is not annual spending or cash already paid out.
4. A $2 trillion IPO valuation: does it price in future success?
| Valuation scenario | Multiple of annualized Q3 revenue |
|---|---|
| $965 billion | 14.4x |
| $1.5 trillion | 22.3x |
| $2 trillion | 29.8x |
Q3 revenue of $16.8 billion x 4 = $67.2 billion. This is a simple enterprise value to annualized revenue comparison, not a precise valuation adjusted for net cash and diluted shares.
Anthropic was reportedly valued at $965 billion in its May 2026 funding round. The $2 trillion figure floated for the IPO is more than double that.
Justifying $2 trillion would take more than sustained high growth. It would also require high margins, steady cash generation and a balance sheet able to carry the long-term infrastructure commitments. Calling a company central to the AI industry is one thing. Deciding at what price an investment makes sense is a separate question.
Anthropic has shown that AI can move beyond generating revenue to generating profit. What it has not yet proven is whether that profit can last while carrying hundreds of billions of dollars in long-term commitments.
Figures for the private company are based on reports of a private investor briefing and should be distinguished from audited quarterly financial statements.
Insight Times Editorial Desk