Is the AI Chip Bull Market Over? Stocks Slide as Companies Post Record Results
TSMC's net income jumped 69% and Anthropic's revenue rose 45% in a quarter. The question is whether the market is losing AI demand or the excess expectations and prices attached to it.
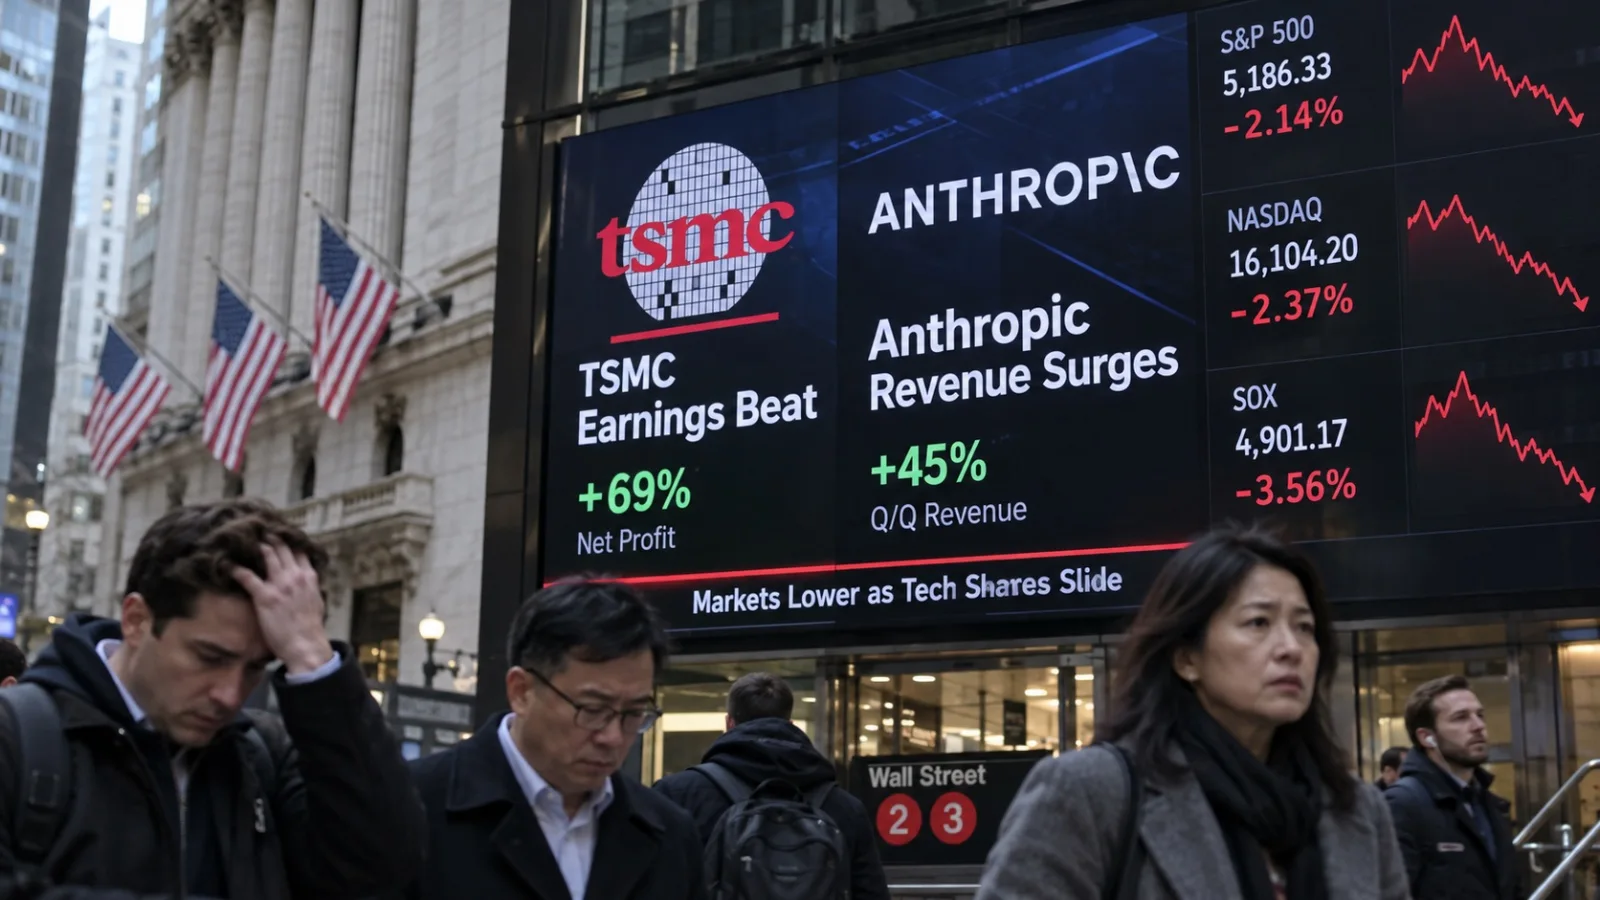
US stocks sold off yesterday, and Asian markets followed today. Korea's KOSPI fell 7.57%. For investors who have held AI and chip stocks for the long term, it has been a painful two days. They bought on the belief that earnings would improve. Prices are now moving as if the industry itself were collapsing.
Yet the numbers released today point the other way.
TSMC, the world's largest contract chipmaker, reported record net income. Anthropic's quarterly revenue also surged. The companies that make AI chips and the companies that sell AI services are growing at the same time.
In Korea, Samsung Electronics fell 9.48% and SK hynix fell 11.06%.
Earnings are growing while portfolios shrink. Making sense of this market starts with resolving that contradiction.
1. What TSMC's results ask: the chip industry is supposedly finished, so what are these numbers?
| Metric | Figure | Note |
|---|---|---|
| Q3 revenue growth, year over year | +50.9% | New Taiwan dollar basis |
| Q3 net income growth, year over year | +68.7% | TIFRS consolidated basis |
| Gross margin | 66.4% | Q3 actual |
| Q4 revenue outlook | $52.3 billion to $54.3 billion | Company guidance |
TSMC's third-quarter revenue was NT$1.4942 trillion and net income was NT$763.1 billion. That is a net margin of 51.1%. More than half of revenue was left as profit.
The next-quarter outlook matters more. TSMC guided fourth-quarter revenue to $52.3 billion to $54.3 billion. At the midpoint, that is about 14% above the third quarter. It also raised its full-year dollar revenue growth forecast to 44%.
This is evidence that AI demand is turning into real chip orders and manufacturer profit. The 2-nanometer process, still in early volume production, already accounted for 8% of wafer revenue. Advanced nodes as a whole reached 79%.
One caveat applies. TSMC's results include demand for Apple's mobile processors as well as AI. Total revenue growth should not be read as the AI growth rate.
Still, it is hard to find a sign that demand has abruptly collapsed at a core supplier of the world's most advanced chips.
2. Anthropic showed AI can make money, but the proof is not finished
The biggest doubt about AI spending has been this: companies are spending hundreds of billions of dollars on GPUs, but can they earn that back by selling AI services? Anthropic offered an important clue.
Anthropic quarterly revenue, 2026 ($100 millions)
- Q1: 47
- Q2: 116
- Q3: 168
Based on accounts from attendees of an investor briefing.
According to Reuters, Anthropic's third-quarter revenue was $16.8 billion, up about 45% from the prior quarter. Compared with $4.7 billion in the first quarter, that is roughly 3.6 times in just two quarters. The company also described an adjusted profit.
The figures matter because they suggest AI is not only an industry that buys chips. It is becoming one that sells real services to end customers.
It is too early to relax, though. Anthropic's numbers come from a private investor briefing, not audited financial statements from a listed company. It is also unclear which costs were excluded from the adjusted profit.
In addition, infrastructure commitments of about $518 billion over the next decade have been reported. Apart from revenue growth, the future cash burden remains large.
3. So why are stocks falling? Prices ran ahead of earnings
It is easy to assume that good earnings should lift a stock. But a share price reflects more than current profit. It reflects expectations for profit over the coming years and the interest rate used to discount that future profit to today's value.
September US consumer price inflation rose to 3.7%, renewing worries that rates will stay high for longer. AI companies need vast capital for capex and power. When rates rise, the price of that capital rises too.
Market reports today said the US 10-year Treasury yield eased to around 5.09%. That alone does not remove the risk. If yields are falling because of growth fears and a flight to safety, stocks can fall alongside them.
Rising earnings and rising share prices are not the same thing. Suppose a company's expected earnings per share next year grow 20%. If the price-to-earnings multiple investors will pay drops from 40 to 25, the share price could in theory fall 25%.
How a stock can fall while earnings grow (hypothetical company)
| Before adjustment | Earnings +20%, multiple compresses | |
|---|---|---|
| EPS | $10 | $12 |
| P/E | 40x | 25x |
| Share price | $400 | $300 |
Profit rises 20% while the price falls 25%. This is a hypothetical example for illustration, not the actual valuation of any stock.
Much of what is happening in the market today can be explained by this mechanism.
Still, not every decline should be pinned on valuation. The memory market faces growing competition from China's CXMT, plus the possibility of future capacity additions and oversupply. A report that SK hynix's Solidigm is linking the import of equipment to its Dalian NAND plant with investment in a US factory shows that expanding memory supply and policy uncertainty exist at once. The company was reported to have disputed the reading that it is pushing to expand Dalian capacity.
That is why it is risky to lump Nvidia, TSMC, memory makers and debt-funded AI data center companies together as one AI trade.
4. A temporary correction, or the end of the bull market?
It is too early to say the AI industry's growth cycle has ended. But there is also too little basis to say the valuation adjustment in AI-related stocks is over.
Three different paths are conceivable.
| Scenario | Signals to watch | Investment reading |
|---|---|---|
| Rebound after a temporary shock | Stable Treasury yields, chip stocks hold their lows, earnings outlooks intact | Staged buying in high-quality names could make sense |
| Prolonged price correction | Earnings rise but multiples keep shrinking | Rebounds and renewed declines may repeat |
| Industry profit cycle worsens | Slowing AI orders, falling memory prices, reduced investment | The investment thesis itself needs review |
The TSMC results and Anthropic revenue so far lend more weight to the first and second scenarios than the third.
But TSMC's strong results do not guarantee results at every company. Customers' capacity to invest and how the stock market sets prices are separate matters.
5. What to watch next
| Indicator | Bullish case strengthens if | Warning sign |
|---|---|---|
| US 10-year yield | Stabilizes as price pressure eases | Inflation re-accelerates and high rates become entrenched |
| SOX, NVDA, TSM | Lows hold and more stocks rise | New lows keep recurring despite strong earnings |
| TSMC revenue and margins | Q4 guidance is met | Weaker orders, lower margin outlook |
| HBM and commodity memory prices | Prices stabilize, production plans hold | Rising inventory, falling selling prices |
| AI company cash flow | Cash generation improves relative to service revenue | Costs and borrowing grow faster than revenue |
The bottom line
Declaring the end of the AI bull market on the basis of today's trading would be premature.
The profit TSMC reported and Anthropic's revenue are real growth. Ignoring that and calling all AI investment a bubble is hard to justify.
But it is also true that the market has begun to demand a much stricter price for high interest rates and enormous capital spending.
The AI industry surviving and every AI stock price today being justified are separate questions.
Investors should not confuse the two. There is no need to abandon good companies out of fear, but no reason either to accept risky prices and leverage because of faith in a good company.
This is not a time to be more optimistic or more pessimistic. It is a time to be more precise.
Insight Times Editorial Desk