AI Can Lift More Than Stocks: It May Push Long-Term Yields Higher Too
The AI boom can grow the numerator of corporate earnings while also growing the denominator of the discount rate. Investors watching long-term Treasury yields now need to add "AI capital demand" to the Fed, inflation and the deficit.
AI adds a fourth variable for long-term rates
Rising long-term US yields are usually explained with three words: the Fed, inflation and the fiscal deficit. A fourth now belongs on the list: AI capital demand.
On Oct. 5, Bank of Japan Deputy Governor Shinichi Uchida described the spread of AI as a "strong positive demand shock" that puts upward pressure on the economy and prices. When AI lifts asset prices, financial conditions ease. But when AI-related companies issue large volumes of corporate bonds to fund investment, the added bond supply can push long-term yields up.
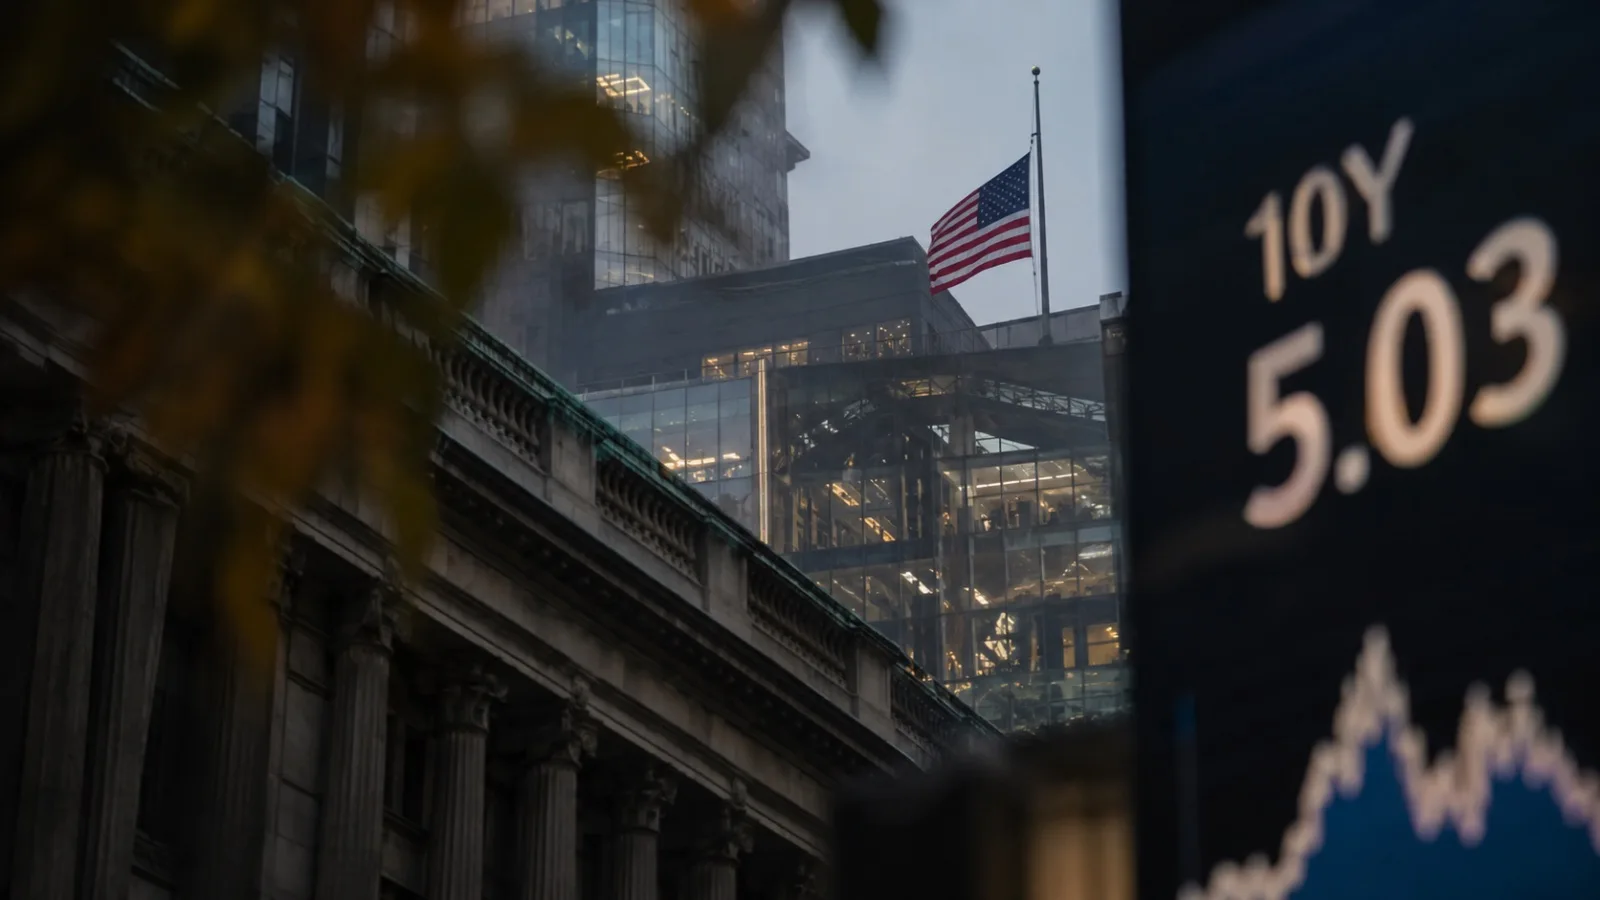
The issue is not limited to Japan. Reuters noted on Sept. 14, when the US 10-year Treasury yield rose above 5%, that heavy corporate bond issuance to fund record AI spending helped drive yields higher. The government deficit and the AI investment boom are both asking the same capital markets for money at the same time.
What sets AI apart from software: physical capital
AI is economically different from the software growth stocks of the 2010s. Software could scale globally with relatively few physical assets. AI does not end with GPUs and HBM memory. It also needs data centers, substations, power generation, cooling equipment, fiber and land.
According to a BOJ analysis in August, annual US IT-related capital investment totals about $1.7 trillion. Expected 2026 capex at five companies alone, Amazon, Microsoft, Alphabet, Meta and Oracle, is about $800 billion. The BOJ treated a substantial share of that as AI-related.
Internal cash flow cannot cover all of it. Funding also comes from corporate bonds, bank loans, private credit, project finance, leases and equity issuance. The Treasury and AI infrastructure companies, with entirely different purposes, can end up competing for the same long-term capital.
If AI succeeds, the neutral rate may rise too
Productivity is the more important piece. The argument that technological progress raises productivity and so lowers prices over time may be only half right.
If AI raises companies' expected returns, they have a reason to keep investing at higher rates than before. If capital accumulation speeds up and investment demand grows structurally, r-star, the real rate that neither overheats nor cools the economy, could itself move higher. Uchida also said AI could affect the neutral rate through productivity and capital accumulation, but he drew a line: the direction and size are still hard to judge.
So "higher AI productivity means lower rates" does not hold automatically. Two forces operate at once: expanding supply capacity from productivity gains, and rising funding demand and aggregate demand from the investment boom. Which is stronger can change over time.
In equities, the numerator and denominator move together
A stock's value is the discounted value of future cash flows. AI touches both sides of that equation.
It can be a plus for earnings, productivity and revenue growth. But if long-term yields and the cost of capital rise, it can be a minus for valuation multiples. The core formula of the AI era is therefore less "AI is good, so tech stocks rise" and closer to AI return > cost of capital.
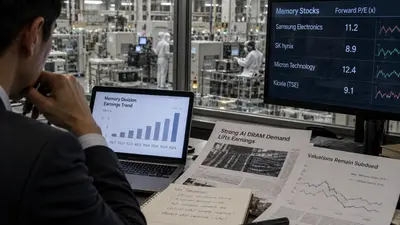
This framing helps explain why some AI chip and infrastructure companies stay strong despite high long-term yields. The market is not buying every growth stock alike. It is picking companies whose earnings and cash flow can grow fast enough to more than offset a higher discount rate.
The problem changes if AI spending surges while revenue, free cash flow and return on invested capital fail to keep up. As Uchida warned, if expected returns do not turn into actual profits, an asset-price correction and a retightening of financial conditions could arrive together.
| Driver | Question | |
|---|---|---|
| Numerator | AI productivity | How much does it lift revenue, earnings, FCF and ROIC? |
| Denominator | Long-term rates | How much does it raise the discount rate and cost of capital? |
Insight Times Editorial Desk