Why the Fed cannot cut: the triple lock of jobs, oil and AI
Inflation is not the only thing blocking a rate cut. A firm labour market, energy prices back on the rise, and an enormous AI investment cycle are each pushing up the floor under US interest rates by a different route.
The case for cutting is still thin
US core CPI slowed to 0.2% on the month and 2.5% on the year in July. On the headline numbers, inflation looks largely beaten. The problem is core PCE, the gauge the Federal Reserve weights more heavily. July core PCE came in at 0.2% on the month and 3.3% on the year. That is still some distance from the 2% target.
Then August payrolls came in far stronger than expected. Non-farm employment rose by 162,000, well above the 56,000 the market had penciled in. The unemployment rate held at 4.1%. Wage growth is cooling, but hiring itself has not cracked.
That combination is awkward for the Fed. Inflation sits above target while the labour market holds. Cutting pre-emptively into that mix risks reheating demand the Fed has only just managed to cool. So the live question is less "when does the cut come" and more "why cut at all right now".
The Taylor rule does not vote for low rates either
The Taylor rule is a policy guideline that calculates an appropriate policy rate from how far inflation sits above target and how far the economy is running above potential. The important point is that it is not one number. Change the rule and you change the answer.
In the simple policy rules published by the Cleveland Fed for the third quarter of 2026, the Taylor (1993) rule points to a federal funds rate of 5.69%, and the Taylor (1999) rule, which uses core inflation, points to 5.06%. Both sit above the current policy rate of 3.50 to 3.75%.
None of that has to be taken as a prescription. The Fed does not fly the Taylor rule as an autopilot. But the message is clear enough. The US economy right now is nowhere near the state that would demand rapid cuts to fight a recession.
A 4.8% 10-year may be a new equilibrium, not an accident
This is where the policy rate and the 10-year Treasury yield have to be separated. The Taylor rule speaks to the short-term policy rate. The 10-year also carries long-run growth, inflation expectations, the fiscal deficit, Treasury supply and the term premium.
On 8 September the US 10-year yield pushed up to around 4.8%. Federal debt has passed 40 trillion dollars, and the deficit is running at roughly 6% of GDP even outside a crisis. On top of that, the AI infrastructure boom is lifting private demand for capital as well.
So reading a 4.5 to 5% 10-year purely as a fear premium may be the wrong call. The 1 to 3% long yields of the post-financial-crisis years look more like the exception, and in an environment of higher nominal growth and higher inflation, the high 4s may well be the new normal range.
Lock one: employment
The August jobs report showed something more important than "the economy is strong". It showed that the Fed's need to cut has shrunk.
The 162,000 gain in non-farm payrolls was the largest in five months. Labour force participation rose too. Average hourly earnings growth slowed to 3.1% on the year, which eases the worry about wage-driven inflation, but it also weakens the recession signal at the same time.
That is why, heading into the September FOMC, the market is pricing somewhere between a hold and a hike rather than a cut. Strong employment is good news, but in this market good news does not translate into lower rates.
Lock two: oil
The riskiest variable this year is not the level of crude but how long it stays there.
Brent reached the 97 dollar a barrel range on 8 September. The World Bank forecasts energy prices rising 24% year on year in 2026, with Brent averaging 86 dollars for the year. That is about 25% above the 2025 average of 69 dollars.
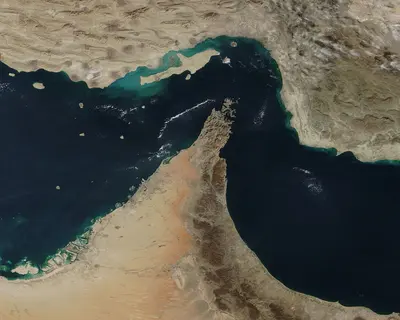
An oil shock first lifts headline inflation through petrol and freight costs. But if the shock persists, logistics, insurance and raw material costs seep into unit production costs. Research from the Dallas Fed estimates that the rise in shipping costs from a disruption at the Strait of Hormuz alone could add roughly 0.1 percentage point to core PCE by the end of 2026.
What the Fed fears most is not a one-day spike in crude. It is high energy prices holding for months, long enough to work their way into corporate pricing decisions and consumer inflation expectations.
Lock three: AI
Over the long run, AI may be a disinflationary technology. If productivity rises and the same labour and capital produce more output, unit costs fall.
But AI in 2026 still looks more like a capital spending phase than a productivity harvest. Data centres, GPUs, memory, transmission grids, generation capacity, cooling, construction labour, land and long-term financing are all needed at once. Reuters reports that AI-related corporate bond issuance will reach roughly 500 billion dollars in 2026, about a fifth of all US investment-grade corporate issuance.
The effect of AI on economy-wide productivity is also still a work in progress. US non-farm productivity rose 2.2% year on year in the second quarter, but that cannot be pinned on AI alone. Companies have to embed AI in actual work processes and organisational structures before productivity gains show up properly in the statistics.
In other words, AI may push prices down over time, but right now it also does the opposite: it swells investment demand and demand for power and capital, and lifts the floor under interest rates.
What September's FOMC really turns on
Federal funds futures currently put the odds of a 25bp hike in September at around 60%. Only days ago, when Governor Christopher Waller said he could support a hold if inflation kept cooling, those odds fell to near 50%. Then the strong August jobs report landed and the market tilted back toward a hike.
Which means the inflation data due before the 15 to 16 September meeting matters more than the meeting itself. Put it in Waller's terms: if inflation keeps cooling, the case for holding strengthens; if it heats up again, the case for hiking comes back to life.
That is also why the market changes direction day by day. The question of which is the greater danger, recession or inflation, has not yet been settled.
FAQ
Insight Times Editorial Desk