Waiting for rate cuts is how you miss the market

Since 2022 US equities have repeatedly broken the textbook link between high rates and falling stocks. The explanation is not the policy rate. It is the Treasury's checking account, T-bills, the RRP window and the capital expenditure bills coming out of data centers.
Photo Federalreserve · Public domain · Wikimedia Commons

Rates went up. Why didn't the market break?

From 2022 the Federal Reserve raised its policy rate sharply and shrank its balance sheet at the same time. By the textbook, that is a hostile environment for equities, and especially for growth stocks, which are valued by discounting distant future profits back to the present.

The outcome was more complicated. US equities absorbed the tightening shock, and megacap technology moved to the center of a new investment cycle built around AI.

If you file that away as "stocks were strong despite high rates," you will make the same mistake in the next cycle. There is a better question than the level of rates. While the Fed was withdrawing money, where did the market's cash actually leave from, and where did it go?

The second hand on the money supply: the US Treasury

The US government keeps a huge operating account at the Fed called the Treasury General Account, or TGA. Tax receipts and the proceeds of debt issuance flow in. Government spending flows out.

When the TGA balance rises, cash moves out of the private financial system and into the government's account, which drains reserves. When the government spends TGA money, that cash returns to the private sector. The Fed sets the policy rate, but the timing of when cash leaves the financial system and when it comes back is also shaped by the Treasury's cash management.

Then there was the overnight reverse repo facility, the ON RRP. It is the window where eligible institutions such as money market funds park spare cash at the Fed overnight. In early 2023 roughly 2 trillion dollars was sitting there. As the Treasury then issued short-term bills on a large scale, money market cash drained out of the RRP and moved into T-bills, which paid more.

The important detail is that this money did not go straight into stocks. The primary destination of the falling RRP balance was mostly short-term Treasury paper. But because RRP cash absorbed that supply, the Treasury's borrowing did not suck bank reserves out all at once. That is one reason the liquidity squeeze the market felt during quantitative tightening was milder than the raw balance sheet numbers suggested.

The 2023 cushion is almost gone

This is the part that matters most right now. On 8 September 2026 the ON RRP balance stood at roughly 626 million dollars. It is effectively empty. The TGA, by contrast, averaged about 967.9 billion dollars in the week to 2 September.

So the argument that "there are still trillions in the RRP, so QT can keep being absorbed" no longer holds. The plumbing of liquidity in 2023 and the plumbing today are not the same.

That is not a prediction of a liquidity crisis. The point is simpler. From here, the effect of Treasury cash building and debt issuance on private bank reserves has to be watched more directly than before. Even an identical rise in the TGA hits the market differently depending on which investors the cash came from and what maturities the funding was raised in.

Washington would rather grow the denominator than pay down the debt

The core problem in US public finance is not the absolute size of the debt but the debt relative to the size of the economy. The CBO projects federal debt held by the public will reach about 101% of GDP by the end of 2026. The deficit runs at roughly 1.9 trillion dollars, or 5.8% of GDP.

Cutting the debt quickly would require tax increases or large spending cuts. Neither is politically easy. Inflating away the real value of the debt is another route, but it pushes up long-term rates and the cost of living.

That leaves the least painful option: growing the denominator, meaning productivity and nominal GDP. This is why the United States treats AI as national growth infrastructure. If AI does more than move technology share prices, and actually improves labour productivity and corporate cost structures, then the same debt can be carried by a larger economy.

But that is still a hypothesis, not a result. Claiming AI has already lifted economy-wide productivity ignores how much real friction remains in data integration, security, redesigning workflows, and power and network capacity.

AI spending looks less like an app subscription and more like building a factory

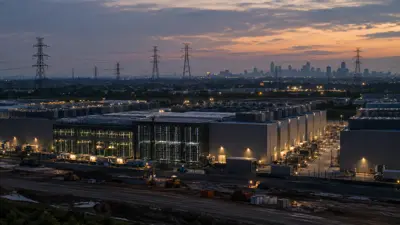
The defining feature of this AI cycle is that it is a software boom whose money pours into physical assets. GPUs, CPUs, HBM, servers, network gear, data center buildings, substations and generation capacity are all needed at once.

Microsoft recorded 41 billion dollars of capital expenditure in the fourth quarter of its 2026 fiscal year alone, and said about two thirds of it went into relatively short-lived assets such as GPUs and CPUs. The company guided to roughly 190 billion dollars of capex for the 2026 calendar year as a whole.

Those numbers mean AI is no longer a research line item at a handful of software companies. It is a large industrial equipment cycle. And the real contest starts now. That equipment has to prove how much it lifts revenue in Azure, advertising, search, Copilot and enterprise AI, and how much it cuts labour costs and working hours.

Having built a data center is not productivity. The compute inside the building becomes productivity only when it earns customers money or removes their costs.

Watch the reason rates moved, not the rate

Long-term yields cause the same error. Judging whether stocks live or die by a single number does not work. A 10-year yield of 4.8% tells you very little on its own. The reason matters.

If it reflects better expectations for growth and productivity, and therefore a stronger nominal growth outlook, high rates can coexist with strong earnings growth. If it is rising because of fiscal deficits, the burden of Treasury supply and an inflation risk premium, that is far worse for equity valuations and for corporate funding costs.

Which is why the two-line formula, rates up equals stocks down and rate cuts equal stocks up, is nearly useless for investing. Rates are not only a cause. They are also the result of several forces working inside the economy.

What to Watch

First, the TGA balance. If the government accumulates cash quickly, it can work in the direction of draining private reserves. Read it alongside the maturity structure of debt issuance rather than as a single number.

Second, bank reserves and money market rates. With the RRP cushion all but gone, the question is whether falling reserves show up as stress in short-term rates such as SOFR.

Third, the reason the 10-year yield is rising. Separate growth expectations from an inflation and fiscal premium.

Fourth, hyperscaler capex against AI revenue growth. Check whether Microsoft, Alphabet, Amazon and Meta are growing AI-related revenue and cash flow faster than they are growing investment.

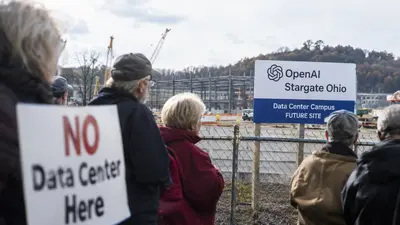
Fifth, data center power and financing structures. The more you see grid connection delays, long-term PPAs, project finance and equipment-backed lending, the greater the chance technology risk turns into financial risk.

The key to the next phase is not the Fed's rate table but the balance in the Treasury's account and the invoices piling up at data centers.

Insight Times Editorial Desk

More by topic

Starting with this story's topics, then what readers are following now

Investor psychology, decision-making and books on investing

Fed

This story's topic24 storiesSee all →

The central bank of the United States, carrying a dual mandate — stable prices…

Gas Prices, Not Politics, Are Deciding This Midterm Market Story

Forecasts of a Republican defeat are not exaggerated. The House has tilted clearly toward Democrats, the Senate has moved from a toss-up to a slight Democratic edge, and Trump's net approval is the lowest of either term.

Macro

It's Not Just Hormuz: Why the Middle East War Is Becoming a Fed Problem Again

The US-Iran ceasefire has already collapsed, and the risk no longer sits in the Gulf alone. With the Red Sea and Saudi Arabia's bypass pipeline now under threat too, an energy shock is spreading into prices, the Fed, and growth-stock valuations.

Macro

Is Bitcoin Coming Back? A Recovery That Still Has to Prove Itself

Bitcoin has slipped from above $126,000 to around $83,000 while AI stocks hog the spotlight. It is up more than 40% from its summer low, but it is too early to call a new bull market.

Investing

Weekly Check: The AI Bull Market Isn't Over, It's Just Gotten Harder

A 5% 10-year yield, 470 gigawatts stacked up in Texas, Chinese DRAM, and whether data centers actually get switched on are starting to decide who wins the AI trade through 2027.

Tech

Why a Wobbly Yen Carry Trade Hits US AI Stocks First

It is not just dollar-yen at 160. Watch the US-Japan rate gap, yen direction, volatility, and US long-term rates together, because AI and high-valuation growth stocks get squeezed first when all four move at once.

Macro

Who Buys the T-Bill Behind Your $1 Stablecoin

Stablecoins aren't a crypto asset class so much as new plumbing for moving dollars online, and every new dollar that flows in gets tied to short-term Treasuries.

Macro

S&P 500 Slips 0.22%, but 73% of the Market Fell

Long-term yields above 5% weighed on small caps and semiconductors on Oct. 7. A strong 10-year Treasury auction and a few large tech names limited the index's losses.

Tech

MSFT

This story's topic22 storiesSee all →

The Cheaper Tokens Get, the Bigger Your AI Bill Gets

As AI shifts from training to inference, the token is becoming an industrial commodity. Falling prices are not cutting demand, because agents and automation consume tokens at a scale no human chat session ever did.

Investing

Tesla Semi Waited 9 Years. Now It's Rolling Off a Real Factory Line

The Tesla Semi, unveiled back in 2017, has finally reached full-scale production at a dedicated Nevada plant. The number investors should watch isn't the 50,000-unit annual capacity, though. It's what the truck actually saves per mile.

Tech

Why Microsoft Rebuilt Copilot: AI Billing Shifts From Seats to Workload

The redesign is less about new features than about Microsoft expanding its enterprise AI revenue model beyond the per-seat subscription into task delegation and agent execution.

Tech

AI Was Supposed to Live in the Cloud. Apple Is Bringing It Back to the Desktop.

Four Mac Studios running a trillion-parameter model matters less than the economics behind it: heavy, repeated AI use can make owning compute cheaper than renting it by the token.

Tech

The industry wins, the shareholder loses: AI's most awkward scenario

The biggest risk in AI is not that the technology fails. It is that AI works, spreads through the economy, and still destroys returns because too much capacity gets built. The internet succeeded. Plenty of dot-com investors did not.

Investing

Trust the Model, Never Fully: Nadella's Rule for the Superintelligence Era

The next AI contest is not only about how smart models are. It is about what permissions they get, how they are monitored and when they can be stopped.

Tech

Burry's AI Bubble Warning Moves From Prices to the Balance Sheet

Michael Burry's case has shifted from expensive stocks to debt, long-term commitments and private credit. New BIS data supports part of it. Microsoft's results complicate the rest.

Investing

HBM

75 storiesSee all →

Memory stacked next to the GPU.

AI Chip Peak Check: Demand Still Rising, Risk Building in 2027-2029 Supply and Funding

DRAM and NAND contract prices are still climbing and HBM suppliers hold the edge. Power shortages, AI financing costs and simultaneous memory expansion are the risks for later years.

Investing

Has Memory Peaked? Prices Are Cooling, but the Shortage Looks Set to Run to 2028

Price growth has slowed and consumer demand is already breaking. Server and HBM supply remains short, and Micron says more than 75% of its 2027 volume is already committed to customers.

Tech

The Real ASML Number Isn't the 3% Pop, It's the 30% Capacity Hike

ASML's rally isn't just an AI trade. Customers are already locking in 2027 tool slots, and ASML is raising Low-NA EUV capacity by roughly 30% to keep up.

Investing

2027 Isn't the End: Citi's Case for a Memory Supercycle Running to 2031

Citi says the memory shortage timeline is stretching again. If AI shifts from "train once" models to continual learning, HBM, server DRAM and enterprise SSDs could all fall short at the same time.

Tech

AI Chips Haven't Peaked. The Real Risk Sits in 2028 Supply

HBM and server DRAM shortages are now spreading into enterprise SSDs. The question isn't today's strength, it's how much new capacity these prices are pulling in and when it lands.

Investing

The Next AI Chip Race Is About How Chips Connect

Applied Materials will lift its stake in Dutch equipment maker BESI from about 9% to 20%. The bet is less about control than about a new way to link chips.

Tech

US AI Data Centers Are Headed for 90GW. Gigawatts Now Matter More Than Dollars

Goldman Sachs expects US data center capacity to grow from 64GW at the end of 2026 to 90GW at the end of 2027. The AI race is moving from buying GPUs to building power plants and transmission lines alongside them.

Tech

A building that houses servers and networking gear and supplies them with powe…

Nvidia and Palantir Put AI Inside the Supply Chain - The Real Shift Is That It's Learning Judgment

A single Vera Rubin rack holds 1.3 million parts. The real breakthrough in Nvidia and Palantir's new supply chain AI isn't automating that complexity, it's capturing the judgment calls that used to live only in planners' heads.

Tech

Why the White House Swapped "AI" for "Super Intelligence"

Executive Order 14434 renames AI across the federal government without defining a new technology. The real story is about roughly $700 billion in capex, free cash flow and electricity.

Tech

2027 Investing Needs Alignment, Not Prediction

A new investing book argues the hard part was never picking the next winner. It's staying aligned with where value and bottlenecks are moving while keeping old human weaknesses in check.

Investor Mind

AMD Crossed $1 Trillion, and the Market Started Looking at CPUs Again

AMD's stock topped a $1 trillion market cap for the first time. The rally isn't just about being an Nvidia alternative. It reflects a reassessment of AMD as a full-stack AI infrastructure vendor, one that bundles CPUs, GPUs and networking, as AI shifts from chatbots to agents and reignites data center demand for CPUs.</deck> <parameter name="oneline">As AI moves from chatbots to agents, the market has started counting the CPU sitting next to the GPU again.

Tech

Why Nebius Is Keeping Some 2027 AI Capacity Off the Shelf

Nebius mixes long-term contracts, short-term premiums and auctions. Holding back capacity pays only if the servers stay busy, and it is not yet clear the pricing will last.

Tech

DeepSeek's $15 Billion Raise: Model Makers May Feel It Before Nvidia Does

China's DeepSeek is closing a round about twice its original target. For US investors, the question is less the size of the check than where the money goes and whose profits it could erode.

Tech

AI Data Centers Are Rewriting Contracts While They Wait for Power

Oracle's Project Jupiter shows that the AI power shortage is no longer a "2030 forecast." The mere possibility of a delayed power hookup has already triggered a force majeure clause, and it is starting to shake billions in loans and lease-income timelines.

Tech