Higher Rates Don't Break Big Tech's Business. They Reprice Its Future.

Microsoft, Alphabet, Apple and Nvidia are sitting on more cash than debt. What rates actually change is the discount rate applied to cash flows a decade out, and whether a cut is a soft landing or a recession signal.
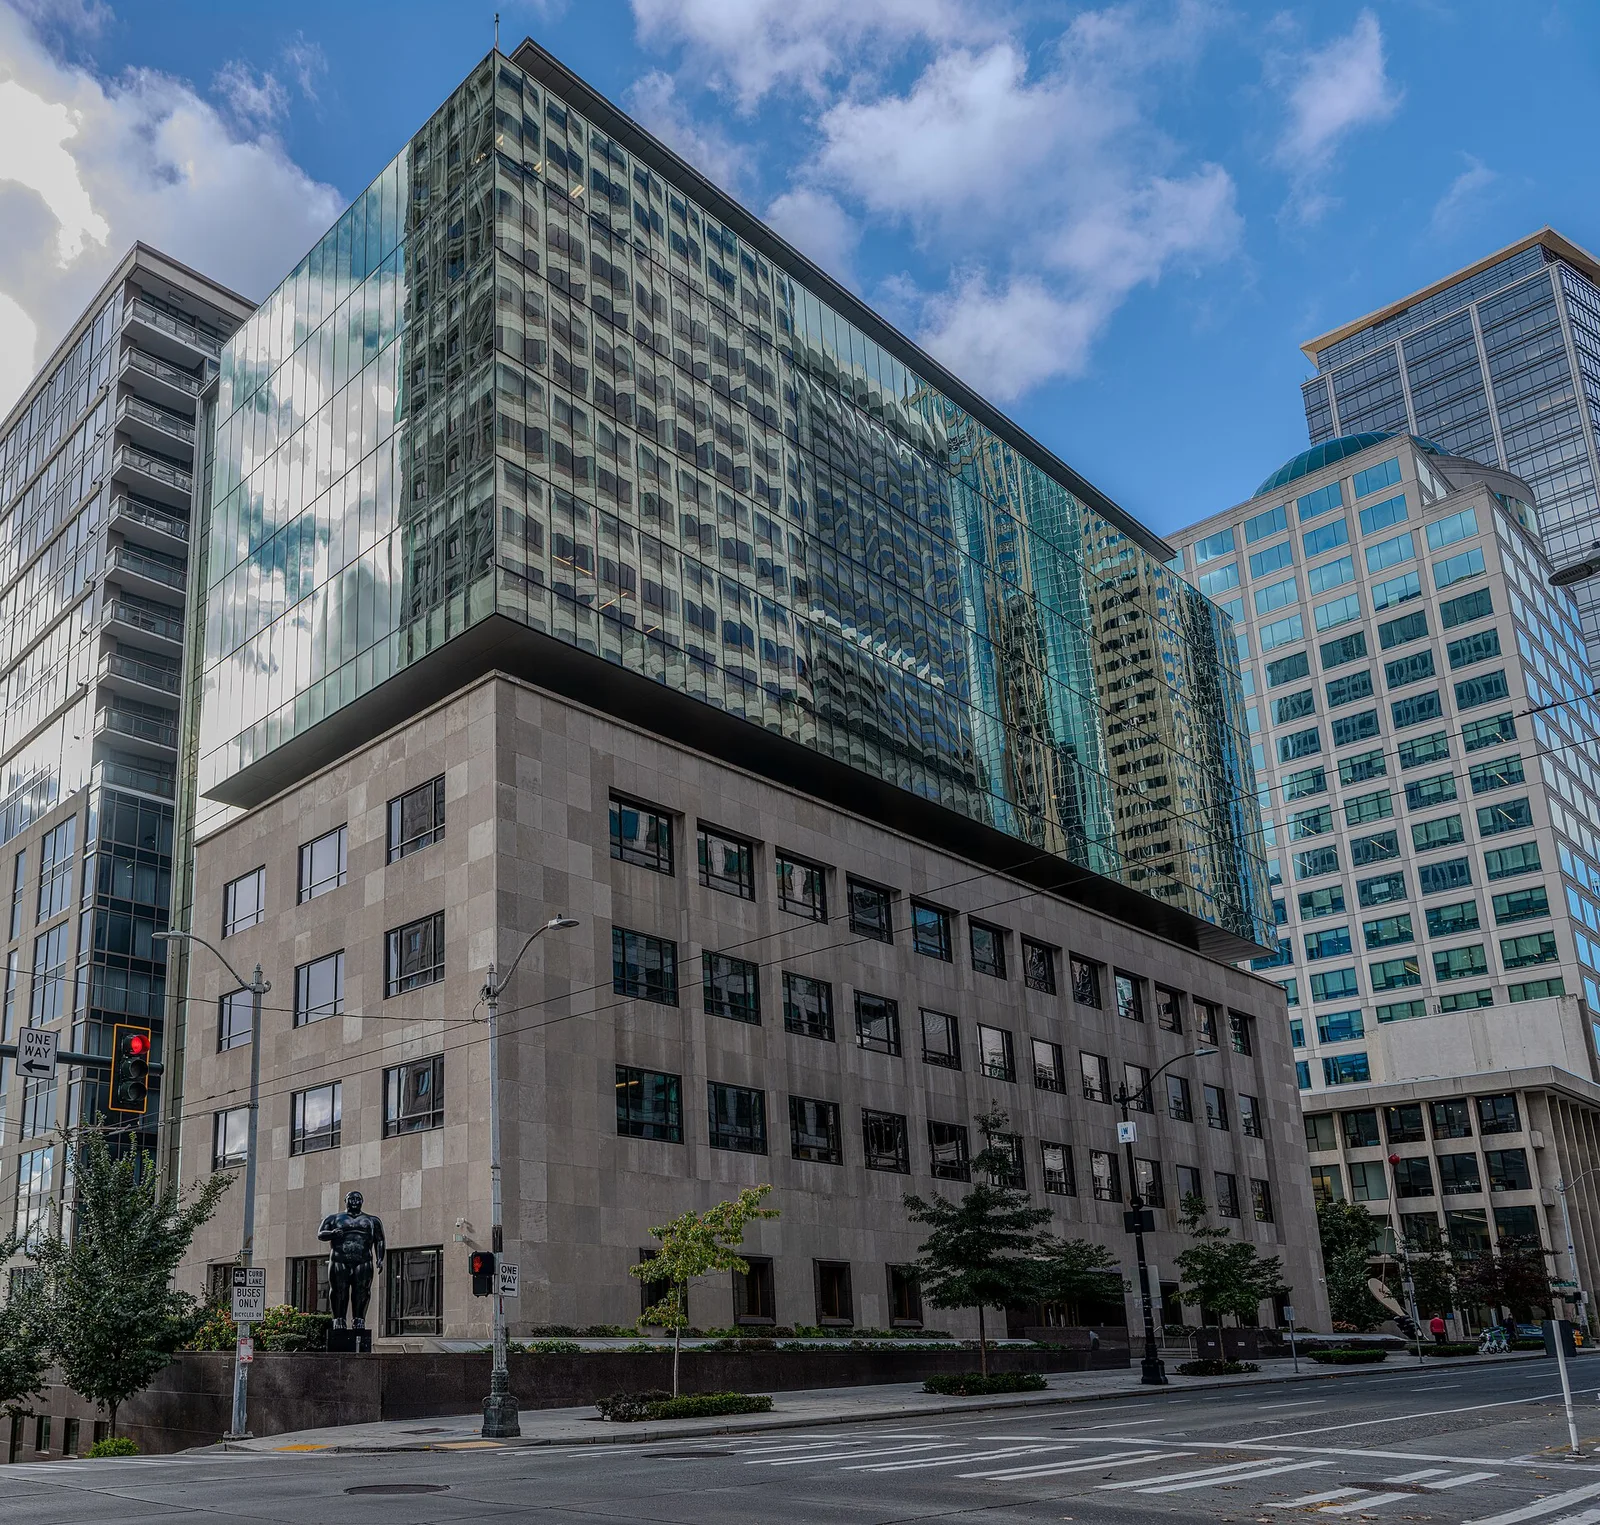
Photo Davidralphhughes · CC BY-SA 4.0 · Wikimedia Commons

Rising rates do not immediately break the business

Every rate headline brings back the same line: when rates go up, tech is finished. For manufacturers and borrowing-dependent companies, there is something to it. High rates raise the cost of new borrowing and refinancing, and they cut directly into the survival room of companies with weak cash flow.

Microsoft, Alphabet, Apple and Nvidia start somewhere else. They carry large operating cash flows and large liquid balance sheets. At the end of June 2026, Microsoft held $76.8 billion in cash, cash equivalents and short-term investments against roughly $46.1 billion in long-term debt principal. Apple held about $146.5 billion in cash and marketable securities against about $84.3 billion in commercial paper and term debt. Alphabet held $242.5 billion in cash, cash equivalents and marketable securities against about $98.2 billion in long-term debt. Nvidia, as of the end of July, held $56.6 billion in cash and marketable debt securities against roughly $33.4 billion in short- and long-term debt.

CompanyLiquid assetsAs of
Microsoft$76.8B cash, cash equivalents and short-term investmentsEnd of June 2026
Alphabet$242.5B cash, cash equivalents and marketable securitiesEnd of June 2026
Apple$146.5B cash and marketable securitiesEnd of June 2026
Nvidia$56.6B cash and marketable debt securitiesEnd of July 2026

So for these companies, high rates are less a question of not being able to borrow and more a question of cost of capital versus return on investment. Alphabet earned $2.8 billion in interest income in the first half of 2026, but its interest expense also rose, to $1.8 billion. Nvidia booked $1 billion in interest income and $300 million in interest expense over the same period. Cash-heavy companies collect income when rates are high. But as AI data center investment and long-term funding scale up, financing costs are no longer a line item you can ignore entirely.

What moves the stock first is the price tag on future cash

The mechanism is discounted cash flow. A stock is worth the cash a company will generate in the future, converted into today's money. The long-term Treasury yield feeds directly into the risk-free rate that anchors the discount rate.

Take the same $100 arriving ten years from now. At a 6% discount rate it is worth about $56 today. At 8%, about $46.

Nothing about the revenue or earnings forecast has to change. A 2 percentage point move in the discount rate alone cuts present value by roughly 18%.

That is why growth stocks are so rate-sensitive. The more of a company's value sits far out in the future, the longer the stock's duration. Aswath Damodaran of NYU has described the approach of using a long-term Treasury yield matched to the duration of the cash flows as the risk-free rate when valuing a business over the long run. The more a company's case rests on free cash flow five and ten years out rather than earnings today, the harder a rise in long-term yields hits.

Not every megacap moves the same way

Rate sensitivity is not settled by whether a stock is labeled tech.

The first factor is valuation. A company already carrying a high P/E takes a larger hit when the discount rate rises. The second is the certainty of growth. If EPS estimates climb faster than rates do, the stock can hold up. The third is investment intensity. A business that requires billions to tens of billions in capex, as AI data centers do, feels a higher cost of capital more directly.

Which is why 2026's Big Tech should not be read the way 2022's was. Alphabet's long-term debt grew from $46.5 billion at the end of 2025 to $98.2 billion at the end of June 2026. Nvidia's long-term debt went from $7.5 billion at the end of January 2026 to $32.4 billion by the end of July. The AI race leaves these companies as powerful cash generators while turning them into far more capital-intensive ones than they used to be.

There are two kinds of rate cut

The error investors most need to avoid is treating a cut as automatically bullish. The cause matters.

Normalization. Inflation cools and the economy lands softly. Revenue and EPS estimates hold or improve while the discount rate falls. Here you can get EPS growth and multiple expansion at the same time.

Recession. Demand drops or financial stress forces the Fed to cut quickly. The discount rate falls, but so do estimates for cloud, advertising, semiconductors and IT spending. Here the cut to EPS can outweigh the lift in the P/E.

The Fed's target range currently stands at 3.50% to 3.75%. At the July FOMC meeting, the committee held rates, judging economic activity solid and inflation still above the 2% target. The next scheduled meeting is September 15 and 16. For a long-term investor, the question is not how many basis points come off. It is what economic conditions made the cut possible.

What to watch

The 10-year Treasury yield. A more direct benchmark for growth valuations than the policy rate. If the 10-year falls while EPS holds, the multiple expansion case gets stronger.

12-month forward EPS. More important than the direction of rates. If yields fall and forward EPS is marked down at the same time, suspect a recessionary cut.

Capex against free cash flow. Rising capital spending is absorbable if FCF rises with it. If capex spikes while FCF margins slide, the cost of capital problem grows.

Balance sheet trend. Watch total debt against cash and marketable securities, and interest income against interest expense. That pairing shows how much AI spending is reshaping the financial structure.

FAQ

Does a rate increase always drag tech stocks down?

No. A higher discount rate is a headwind, but faster-than-expected EPS growth can offset it. AI semiconductors from 2023 to 2025 are the obvious case. Rates are one axis of valuation, not the only axis of a share price.

Should I watch the policy rate or the 10-year?

For valuing long-duration growth companies, a long-term risk-free rate such as the 10-year is more directly relevant. Even if the Fed cuts, long-term yields can rise on deficits and inflation expectations, leaving the discount rate burden on growth stocks intact.

Don't high rates help companies with a lot of cash?

Partly. Interest income on short-term paper and deposits goes up. But at a company worth trillions, a shift of a point or two in the multiple can matter far more to shareholder value than a few billion in interest income.

How do I tell a normalization cut from a recessionary one?

Look at 12-month forward EPS and revenue growth before you look at the size of the cut. EPS holding while long-term yields fall looks like normalization. EPS being marked down quickly while rates fall looks like recession.

For Big Tech, high rates are not about failing to service debt. They are about the price tag on future cash.

Insight Times Editorial Desk

More by topic

Starting with this story's topics, then what readers are following now

Investor psychology, decision-making and books on investing

NVDA

This story's topic92 storiesSee all →

Nvidia and Palantir Put AI Inside the Supply Chain - The Real Shift Is That It's Learning Judgment

A single Vera Rubin rack holds 1.3 million parts. The real breakthrough in Nvidia and Palantir's new supply chain AI isn't automating that complexity, it's capturing the judgment calls that used to live only in planners' heads.

Tech

Amazon Goes After Nvidia's Strongest Moat, and It Is Software, Not GPUs

Amazon's open-source TorchNeuron aims to let existing AI code run on its Trainium chips. The contest comes down to the total cost of AI compute and the return on Amazon's $220 billion in annual capital spending.

Tech

2027 Investing Needs Alignment, Not Prediction

A new investing book argues the hard part was never picking the next winner. It's staying aligned with where value and bottlenecks are moving while keeping old human weaknesses in check.

Investor Mind

AI's Next Bottleneck Is Money, Not Chips

Broadcom is lending Anthropic up to $42 billion, and Nvidia wants to build a $500 billion market for loans backed by GPUs. The AI race may turn on what rate buyers pay to borrow.

Tech

AMD Crossed $1 Trillion, and the Market Started Looking at CPUs Again

AMD's stock topped a $1 trillion market cap for the first time. The rally isn't just about being an Nvidia alternative. It reflects a reassessment of AMD as a full-stack AI infrastructure vendor, one that bundles CPUs, GPUs and networking, as AI shifts from chatbots to agents and reignites data center demand for CPUs.</deck> <parameter name="oneline">As AI moves from chatbots to agents, the market has started counting the CPU sitting next to the GPU again.

Tech

Two Companies Drive 34% of S&P 500 Earnings Growth as AI Pays Sellers First

Nvidia and Micron generate a third of expected earnings growth in US large caps. Apollo says the financial effect of AI is not yet visible in the S&P 493.

Investing

Why Nebius Is Keeping Some 2027 AI Capacity Off the Shelf

Nebius mixes long-term contracts, short-term premiums and auctions. Holding back capacity pays only if the servers stay busy, and it is not yet clear the pricing will last.

Tech

Valuation

This story's topic34 storiesSee all →

Measuring where a share price sits relative to the company’s results.

Anthropic's IPO: The Number That Matters More Than $100 Billion Is $2 Trillion

Claude-maker Anthropic is growing at a stunning pace, but the real question for investors is not how fast, only how long, and how much cash is left after GPUs and data centers.

Tech

Oil at $110, 10-Year Yield at 5%: The Discount Rate on Growth Stocks Is Rising Again

Brent crude spiked to $109.97 intraday and the US 10-year Treasury yield tested the 5% threshold. What matters is not the numbers themselves but that oil-driven inflation fears are pushing bond yields higher across the globe at once.

Macro

Is This AI Memory Supercycle Really Different? The Valuation Trap for Long-Term Investors

Memory is reshaping around AI through 2030. But a good industry and a good entry price are separate questions.

Investing

ARK Sets Tesla 2031 Target at $4,400, Betting on 8.1 Million Robotaxis and Optimus

ARK Invest's new model implies a $17.5 trillion market cap for Tesla by 2031. It reads less like a forecast than a scenario that assumes robotaxis and robots earn real money.

Tech

Year Five of the Bull Market: Why U.S. Stocks Aren't Expensive Yet, and What AI Chips and Power Must Deliver

U.S. stocks have gained about 117% since the October 2022 low. What happens next depends less on the bull market's age than on whether expected earnings, which lean heavily on AI semiconductors, turn into reality.

Investing

Marvell's $115 Billion Lumentum Deal: Is AI's Next Bottleneck Light, Not Chips?

Marvell's purchase of Lumentum points to a contest beyond GPU speed, in data transfer and power efficiency. Whether the price is right is not yet confirmed.

Tech

Lam Research Revenue Jumped 54%. The Stock Fell 12%. Here Is Why

Record results and a sharp sell-off at Lam Research show a paradox of growth investing. The key question is not how fast a company grows, but how much investors paid for that growth.

Tech

GOOGL

This story's topic23 storiesSee all →

Google Catches Up, and Rivals Run Ahead Again

The real test for Gemini 4 Argon is not AI performance. It is whether Google can win customers and keep them.

Tech

Same cloud, three different ways to earn the money back

Microsoft, Alphabet and Amazon are all spending enormous sums on AI infrastructure. The route each one takes to recover that capital is not the same, and that is what decides the winner.

Investing

AI Data Centers in Space? The Real Test Launches This Week

On October 1, a SpaceX rocket carries a sub-50kg satellite with a Nvidia Orin NX chip and Google TPU test hardware into orbit. It is too early to call this a "space data center," but the signal is clear: the AI industry is rethinking where computing should physically sit.

Tech

Apple's Real AI Bet Isn't a Chatbot. It's Siri Running Your Apps

Apple has stepped back from the race to build a smarter chatbot than ChatGPT. Instead it is building an "OS agent" that connects Mail, Photos, Calendar and hundreds of thousands of apps to actually finish tasks. 2026 is the first year that strategy gets tested as a product, not a keynote promise.

Tech

Why Meta jumped 6.5%: Muse is the first price tag on AI compute

Muse is not a big revenue line yet. But in a capex race running toward $145 billion a year, it is the first product-shaped answer to the question every AI investor is asking: how does this money come back?

Tech

The industry wins, the shareholder loses: AI's most awkward scenario

The biggest risk in AI is not that the technology fails. It is that AI works, spreads through the economy, and still destroys returns because too much capacity gets built. The internet succeeded. Plenty of dot-com investors did not.
Investing

The blue links are disappearing: what a website is worth when AI ends the search

Search is shifting from finding good pages to writing the answer itself. The convenience has a bill attached, and the people who produce the original pages are the ones paying it.

Tech

MSFT

This story's topic22 storiesSee all →

The Cheaper Tokens Get, the Bigger Your AI Bill Gets

As AI shifts from training to inference, the token is becoming an industrial commodity. Falling prices are not cutting demand, because agents and automation consume tokens at a scale no human chat session ever did.

Investing

Tesla Semi Waited 9 Years. Now It's Rolling Off a Real Factory Line

The Tesla Semi, unveiled back in 2017, has finally reached full-scale production at a dedicated Nevada plant. The number investors should watch isn't the 50,000-unit annual capacity, though. It's what the truck actually saves per mile.

Tech

Why Microsoft Rebuilt Copilot: AI Billing Shifts From Seats to Workload

The redesign is less about new features than about Microsoft expanding its enterprise AI revenue model beyond the per-seat subscription into task delegation and agent execution.

Tech

AI Was Supposed to Live in the Cloud. Apple Is Bringing It Back to the Desktop.

Four Mac Studios running a trillion-parameter model matters less than the economics behind it: heavy, repeated AI use can make owning compute cheaper than renting it by the token.

Tech

Trust the Model, Never Fully: Nadella's Rule for the Superintelligence Era

The next AI contest is not only about how smart models are. It is about what permissions they get, how they are monitored and when they can be stopped.

Tech

Burry's AI Bubble Warning Moves From Prices to the Balance Sheet

Michael Burry's case has shifted from expensive stocks to debt, long-term commitments and private credit. New BIS data supports part of it. Microsoft's results complicate the rest.

Investing

AI Is Not One Wave. It Is Five, and They Do Not Peak Together

Treating AI as a single chip cycle hides the important part. Training, inference, infrastructure, agents and physical AI run on different clocks and different revenue models, which is why slower growth at Nvidia and the end of the AI supercycle are not the same sentence.

Investing