Memory Chip Supercycle: Not at Peak Yet, But 5 of 6 Warning Signs Are Flashing
Memory prices are still climbing, but the pace is slowing and PC and smartphone demand is starting to crack under the weight of higher chip costs. This looks less like a price peak and more like a profit plateau building toward the next supply cycle.
Six signals for calling the peak
1. Price growth is slowing Status: Half-lit Prices are still rising, but the pace of increase is decelerating.
2. Capex is surging Status: Lit The seeds of future supply growth are already being planted.
3. Customer orders are getting pushed back Status: Half-lit Order urgency is fading, especially in mobile and among some OEMs.
4. AI demand and consumer demand are decoupling Status: Lit This is the sharpest structural shift of the current cycle.
5. China's market share is climbing Status: Lit This could shake up pricing in legacy DRAM and the mobile market.
6. Valuations are overheating Status: Not yet lit The market is discounting how long the cycle can last rather than rewarding today's strong earnings.
In numbers: three signals are clearly on, two are half-lit, and one is still off. That combination usually shows up in the middle-to-late stage of a cycle, not the early stage.
The first shift: it's not the price, it's the speed of the price
TrendForce expects commodity DRAM contract prices to rise 13% to 18% quarter over quarter in the third quarter, with NAND up 10% to 15%.
Looked at in absolute terms, prices are still strong. But the more telling number is the rate of change. How fast prices rise often signals a cycle turn before the direction of prices does.
Mobile DRAM price growth slowed to 8% to 13% in the third quarter, and buyer inventories rose to an average of 12 to 14 weeks. That points to less urgency in price negotiations.
| Metric | Value |
|---|---|
| Q3 commodity DRAM | +13% to 18% QoQ contract price forecast |
| Q3 NAND | +10% to 15% QoQ contract price forecast |
| Mobile DRAM | 12 to 14 weeks average buyer inventory |
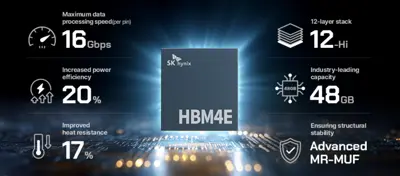
AI memory is telling a completely different story. Enterprise SSD contract prices are expected to rise 23% to 28% quarter over quarter in the fourth quarter, with overall NAND up 15% to 20%.
The second shift: consumers are cracking first
The most important number in this cycle may not be the price of memory itself, but PC and smartphone sales.
IDC expects global smartphone shipments to fall 16.7% in 2026 from a year earlier. PC shipments are forecast to drop 11.3%.
A memory shortage is good news for memory makers but higher cost for their customers. When prices climb too far, customers cut the memory built into each device, raise product prices, or scale back production.
The third shift: the seeds of oversupply are growing inside a shortage
Supply is tight right now. But memory makers have already started investing for the next cycle.
SEMI estimates 300mm memory equipment spending will reach $52 billion in 2026, and a subsequent update projected that memory equipment spending will keep rising past 2026.
Micron has guided for fiscal 2026 capital expenditure of roughly $27 billion, and its new fab in Idaho is targeting first wafer output by mid-2027.
So this is not the moment to worry about oversupply. What matters instead is the lag between capex, equipment installation, cleanroom startup, wafer input, yield stabilization, and an actual increase in bit supply.
The clock that matters for this supply cycle is not set to 2026. It's set to 2027-2029.
China, the new variable
Another difference between this cycle and past memory cycles is China.
According to Counterpoint, CXMT's share of global DRAM revenue rose from 4% in the second quarter of 2025 to 10% in the second quarter of 2026.
Samsung Electronics, SK Hynix and Micron still hold a wide technological lead in HBM and cutting-edge server DRAM. But the story is different in legacy DRAM and the mobile market.
As Chinese capacity grows, the Big Three are likely to keep strong margins on high-value AI products while increasingly having to compete on price with Chinese suppliers in commodity products.
China's impact may show up first not by crashing HBM prices directly, but by lowering the floor under commodity memory prices.
The bottom line
The price surge is likely passing its peak. The profit plateau still has room to run. And the seeds of the next supply cycle are already being planted underneath it.
Insight Times Editorial Desk