The AI Rally Meets a 5% Wall. Micron and Jobs Data Will Decide
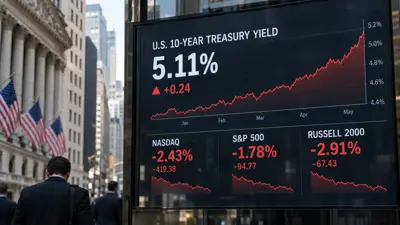
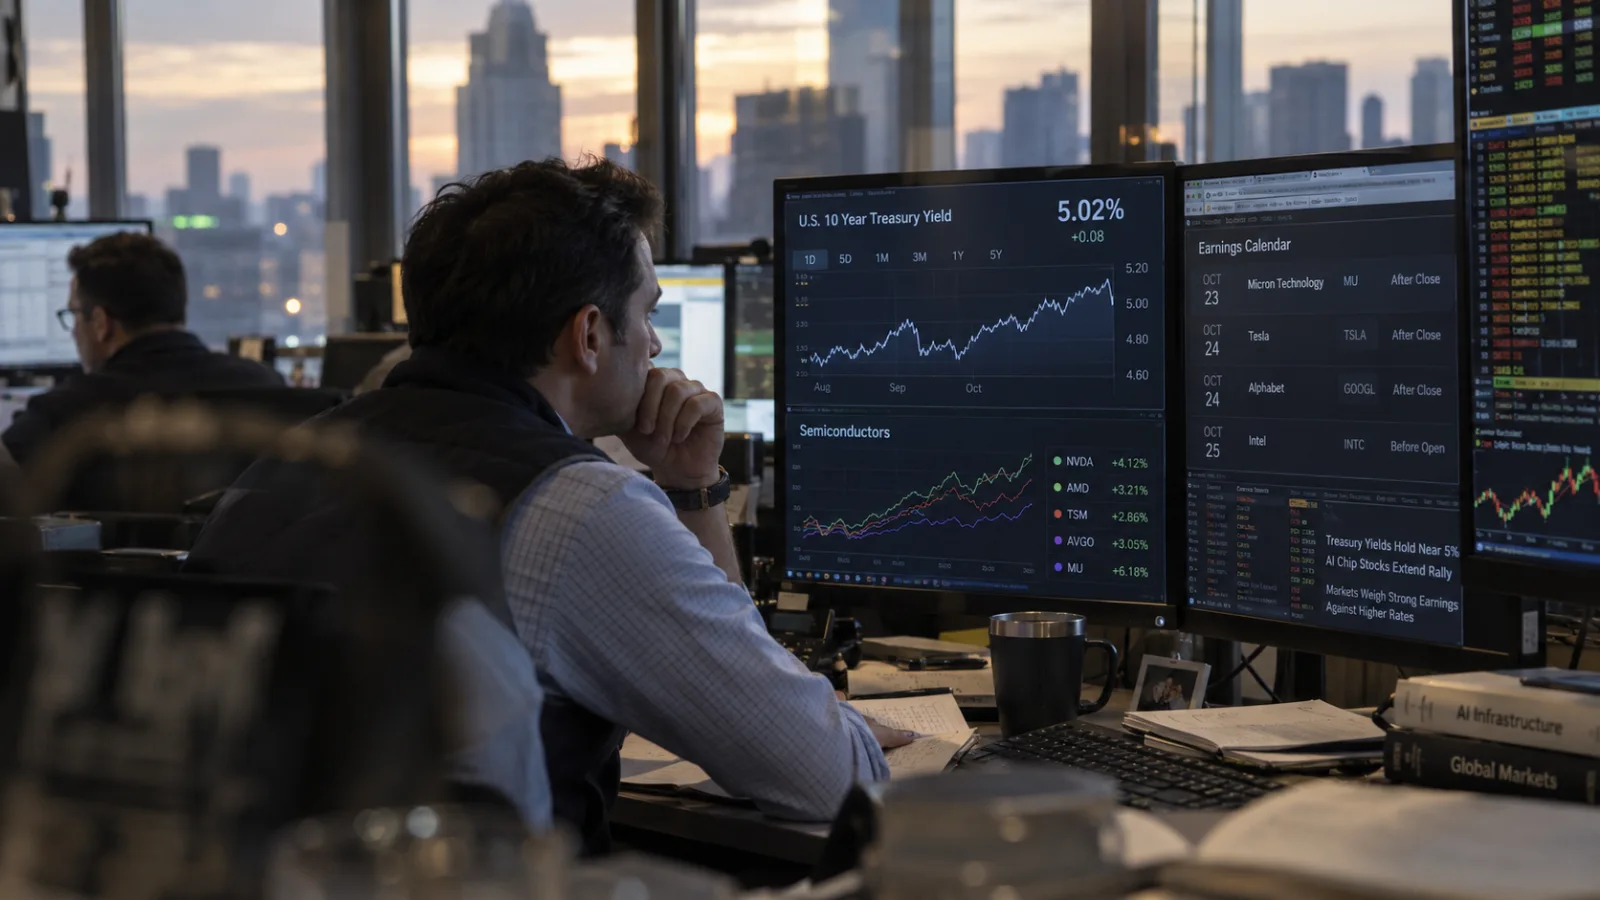
The first week of October tests whether AI earnings growth can outrun long-term rates stuck near 5 percent. Wednesday's PCE report and Micron earnings, and Friday's jobs report and Tesla delivery numbers, could point in different directions.
<span class="kicker">WEEKLY OUTLOOK</span>
The index held. The market underneath did not
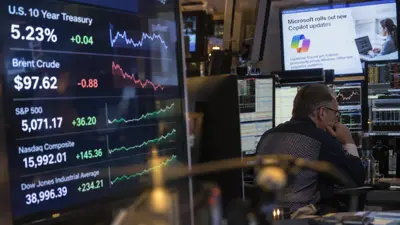
The S&P 500 closed at 7,743.41 on September 25, the Nasdaq at 27,068.72, and the Dow at 51,828.62. Versus the prior Friday, the S&P 500 gained about 1.2%, the Nasdaq about 2.1%, and the Dow about 0.3%. On the surface, it looked like a week when risk appetite came back.
The problem is how narrow that gain was. Semiconductors and a handful of large-cap tech names pulled the indexes higher, but breadth underneath was far weaker. On September 21 the S&P 500 rose 1.49% on the day, yet new 52-week lows outnumbered new highs on both the NYSE and the Nasdaq. The index's strength and the average stock's strength are telling two different stories.
<div class="metric-grid"> <div class="metric"><div class="value">+1.2%</div><div class="label">S&P 500, weekly</div></div> <div class="metric"><div class="value">+2.1%</div><div class="label">Nasdaq, weekly</div></div> <div class="metric"><div class="value">$1T+</div><div class="label">AMD's market cap, a first</div></div> <div class="metric"><div class="value">5%+</div><div class="label">10-year Treasury yield range the market is re-adjusting to</div></div> </div>
<div class="quote"><p>The question this week is not "is AI good." It is "is AI's profit growth fast enough to beat a 5%-plus discount rate."</p></div>
The Fed already turned. Now the data sets the pace
The Fed raised its policy rate 25 basis points on September 16, taking it to a 3.75-4.00% range. The single hike matters less than what it signals: markets have started translating strong economic data back into "upward pressure on rates" again.
The next FOMC meeting is October 27-28. That makes this week's data less about the next rate decision and more about how markets price the odds of further tightening in late October, and where the ceiling on long-term yields sits. The Bureau of Economic Analysis releases August personal income, spending and PCE inflation on September 30. The Bureau of Labor Statistics releases the September jobs report on October 2. August nonfarm payrolls rose by 162,000, with unemployment at 4.1%.
The most comfortable combination for equities is a labor market that holds up while wages and prices cool. The opposite is trickier: if jobs and wages both run hot and PCE comes in high, good news on growth can flip into bad news on the discount rate.
Four things to watch this week
<div class="table-wrap"> <table> <thead><tr><th>Eastern Time</th><th>Event</th><th>Why it matters</th></tr></thead> <tbody> <tr><td>Tue 9/29, 10:00am</td><td>August JOLTS</td><td>Checks whether labor demand is heating back up.</td></tr> <tr><td>Wed 9/30, 8:30am</td><td>August PCE, Q2 GDP (third estimate)</td><td>Feeds directly into late-October Fed expectations and the 10-year yield.</td></tr> <tr><td>Wed 9/30, after close</td><td>Micron FY2026 Q4 earnings</td><td>Tests how much of the HBM and memory-price rally is actually converting into profit.</td></tr> <tr><td>Fri 10/2, 8:30am</td><td>September jobs report</td><td>Payrolls, unemployment and hourly wages are the last big input before rates get repriced.</td></tr> </tbody> </table> </div>
Tesla's third-quarter delivery numbers are also expected in early October. Recent consensus sits around 454,000 vehicles, with Goldman Sachs at 435,000 and Barclays at 475,000, a wide spread. The number itself matters less than production versus deliveries, inventory changes, and how much cash the auto business generates to fund AI-related capital spending.
Micron is testing AI profit, not just AI hype
The single most important company event this week is Micron. The company's own FY2026 Q4 guidance calls for revenue of $50 billion plus or minus $1 billion, non-GAAP EPS of $31 plus or minus $1, and gross margin near 86%. Those numbers already sit so high that simply beating consensus may not be enough to satisfy where the market's expectations have drifted.
What matters more is the next quarter and 2027. On HBM4 specifically, Micron is a step past the question of whether it can get qualified. The company says it is already shipping HBM4 in volume to a lead customer's platform and has sent qualification samples to multiple additional end customers. Watch for how far HBM4 customer adoption spreads, supply constraints, 2027 capacity and pricing, and whether an 86%-range gross margin can hold.
This also matters for Samsung and SK hynix. If Micron shows both high margins and strong next-quarter guidance together, it reconfirms how strong AI memory demand really is. If guidance instead softens, markets may start worrying less about "peak demand" and more about "peak price growth."
Oil isn't a side variable for rates this time. It's a main one
Talks between the US and Iran over a phased ceasefire and reopening the Strait of Hormuz connect to US rates through oil prices. The two sides discussed terms on September 24, but on September 26 President Trump said he rejected Iran's proposal. Diplomatic channels stayed open as of September 27, though no deal has been confirmed.
So the path of "peace deal leads to falling oil leads to lower rates leads to a re-rating for growth stocks" is a possible upside scenario, not a base case. The reverse is just as open: if talks break down again, oil prices and inflation expectations could rise together and push long-term yields higher. That is why AI investors need to watch Middle East headlines this week.
Insight Times Editorial Desk