Meta's Ad Engine Is Strong. Now It Has to Prove the Return on AI
Revenue grew 26% and adjusted operating income rose, but free cash flow was negative $2.12 billion. The third-quarter story is less about AI bulls versus bears than about judging the ad business and the giant capital spending program separately.
Key figures
- +26%: third-quarter revenue growth
- 35.4%: operating margin excluding legal costs
- -$2.12 billion: third-quarter free cash flow
- $145 billion: top of the 2026 capital expenditure forecast
The ad business already shows AI's economic effect
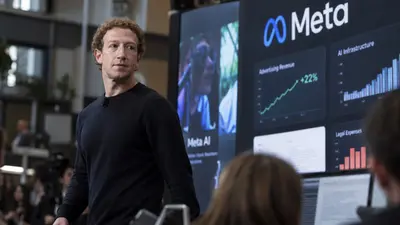
Meta's third-quarter revenue was $64.601 billion, up 26% from $51.242 billion a year earlier. Advertising accounted for $63.061 billion of that, about 97.6% of the total. The existing ad business, not the new AI ventures, is still the main engine of the company.
Daily active people rose only 3%, to 3.64 billion. Ad impressions rose 10% and the average price per ad rose 14%. Multiplying the two gives roughly 25.4%, close to the actual 26% growth in ad revenue. Showing existing users more relevant content and ads appears to matter more than the cost of adding new users.
Meta says AI-driven recommendations and ad efficiency gains are generating additional revenue. Still, not all of the rise in ad prices can be attributed to AI. Advertiser demand and changes in ad mix also play a role. What can be confirmed is that monetization is strong.
The operating income drop hides the core business's strength
Reported operating income was $12.988 billion, down 37% from $20.535 billion a year earlier. That figure includes $9.89 billion in costs to settle youth-related lawsuits with US state attorneys general. Excluding it, operating income was $22.878 billion, an adjusted operating margin of about 35.4%. That is 11.4% above last year's reported operating income.
Diluted earnings per share also need to be read in two ways: $3.83 as reported, and $7.40 excluding the legal costs. The latter is a hypothetical adjusted figure presented by Meta, not a GAAP result. Even without the legal charge, data center depreciation, AI research talent and inference costs keep running.
Fourth-quarter revenue guidance is $73 billion to $76 billion, with a midpoint of $74.5 billion. The guidance supports continued growth, but it does not guarantee long-term profitability.
Is the cash flow deficit a warning sign or a choice to invest for growth?
Third-quarter operating cash flow was $32.786 billion, up about 9.3% from $29.999 billion a year earlier. But purchases of property and equipment of $33.942 billion plus $964 million in principal payments on finance leases, a combined $34.906 billion, exceeded it. Free cash flow, as the company defines it on a non-GAAP basis, was negative $2.12 billion. A year earlier it was positive $10.625 billion.
Reading this as a collapse in operating strength is inaccurate. So is dismissing it as a non-issue. Meta held $82.449 billion in cash and marketable securities at the end of September. The question is less near-term liquidity than how much the scale of investment eats into long-term shareholder returns.
The 2026 full-year capital expenditure forecast, including finance lease principal payments, has had its low end raised, to a range of $135 billion to $145 billion. This is an annual forecast, not a quarterly result. AI infrastructure includes assets that will be used for years, but replacement cycles for computing equipment and depreciation will eventually show up in earnings.
Ten million Muse users is a starting point, not proof of profitability
According to Meta, Muse passed 10 million account setups in the US and Canada about six weeks after launch. Reaching a large base of users matters. But account setups are not daily active users, paying customers or revenue.
If Muse later brokers shopping and bookings and generates advertising or transaction fees, it could add a new revenue layer on top of the existing ad platform. If inference costs per user and product development costs grow faster than usage, economies of scale will be hard to reach. The numbers disclosed so far are not enough to judge Muse's unit economics.
For that reason, Meta's AI spending is best read as two ledgers. AI that raises conversion rates and prices in existing ads shows results in earnings. AI going into Muse and next-generation models still has to prove its payback period and business model.
The Class C shares point to capital allocation and governance, not a funding squeeze
In January 2027, Meta plans to create non-voting Class C common stock and pay one Class C share as a dividend on each existing Class A and Class B share. The initial dividend itself brings no new cash and does not dilute shareholders' economic stake. Economically it resembles a 2-for-1 stock split, and existing voting rights do not change.
The key point comes after that. Meta has said it may use Class C shares for future financing, acquisitions and employee compensation. If additional issuance is large, earnings per share and existing shareholders' economic share could be diluted. At the same time, a non-voting structure preserves Zuckerberg's concentration of voting power.
There is an upside in enabling long-term decision-making. But if investments fail, small shareholders may find it harder to hold management to account. That is why the purpose of any issuance, the net dilution rate and the return on capital should be checked together, rather than the mere existence of new shares.
Insight Times Editorial Desk