Thomson Reuters Grew 10% on AI, but the Stock Fell. Here Is the Trap

Thomson Reuters posted higher revenue and raised its full-year outlook, but shares declined. The result shows that AI software depends less on the technology than on what customers will pay and what profit remains.
The 20-second read

1
Earnings grew, but the stock fell. Thomson Reuters' third-quarter revenue rose 10% from a year earlier, but concerns about the cost of AI investment came into focus.
2
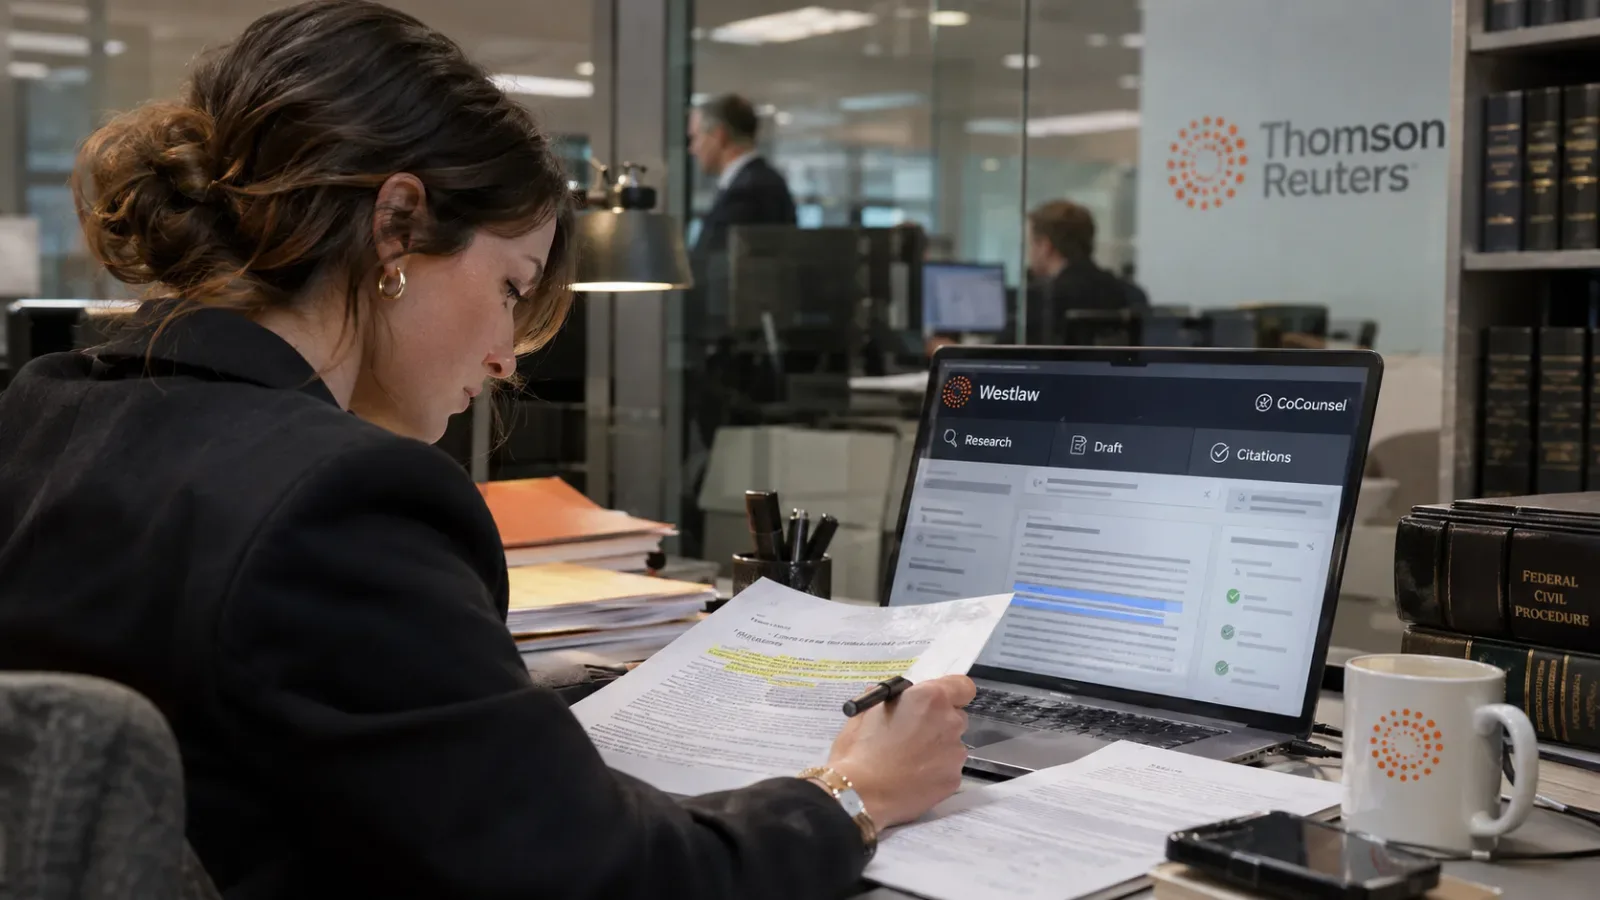
The new competition is about finishing the work, not just giving answers. CoCounsel Legal aims at a workflow that runs from legal research to drafting documents to checking citations.
3
The question for software investors is changing too. What matters is less how much AI functionality sells and more whether revenue per customer, service costs and profit margins are improving together.

1. Why the stock fell on good results

Revenue rose. The full-year outlook went up. The stock still fell. That was the scene after Thomson Reuters (TRI) reported earnings on Nov. 3.

MetricFigureNote
Third-quarter revenue$1.83 billionUp 10% from a year earlier
Adjusted EPS$0.81Third quarter of 2026
Full-year organic growth outlook8.5% to 9.0%Raised from about 8%

On the numbers, the business is heading the right way. The issue is the price of that growth. As the cost of building AI features and rolling them out across products rises, higher revenue may not translate directly into higher profit.

The key is not whether AI revenue exists, but how much of it is left as profit.

2. If AI cuts the hours worked, who makes the money?

Thomson Reuters owns the legal research service Westlaw and CoCounsel, an AI tool for legal work. The new version, CoCounsel Legal, aims at more than giving a lawyer the answer to a single question.

The workflow CoCounsel Legal targets: case research → drafting a brief → rechecking citations

The idea is to connect work that lawyers handle in several separate steps into one flow. For the client, a law firm, the value is saved working hours.

That raises an interesting question. If a law firm bills its clients for the hours it works, what does faster work do to the existing billing model? And if AI software is sold by the seat, a big jump in productivity may not lift the software company's revenue at the same pace.

Who captures the savings AI creates changes the economics for both the law firm and the software vendor.

AI productivity gains and AI vendor revenue growth are not the same thing.

3. Thomson Reuters' real weapon is not the AI model

The value of AI software for professionals is not set by how fluently it writes. Legal documents need exact precedents, verifiable citations and procedures that fit real work.

Thomson Reuters' strengths are the legal data it has built up over many years, specialist services such as Westlaw, and the work environment lawyers already use. Apart from the race to improve AI models, the ability to turn trusted material into finished work product can be a competitive edge.

High customer value does not automatically guarantee high profit, though. The cost of serving customers can also rise as AI use grows. If a pricier product brings equally higher costs, the gain in profitability is limited.

The moat in specialist software looks less like model performance alone and more like a mix of data, workflow integration and trust.

4. The same question for Microsoft, Salesforce and Adobe investors

The issue does not stop at legal software. It is an investing frame that also applies to software companies embedded in customers' daily work, such as Microsoft (MSFT), Salesforce (CRM) and Adobe (ADBE).

More AI features create chances to sell products at higher prices or offer existing customers add-ons. At the same time, development and service costs weigh on margins. Whether the traditional per-seat subscription still fits also deserves a look. The more real workload AI handles, the more customers may price a product on the value of completed work rather than on a simple right to use it.

So a company that owns a good AI product should be told apart from a company that runs a good AI business. Firms whose customers pay extra for AI, and whose revenue from it grows faster than costs, are likely better placed.

Software investors should look at pricing power and the ability to convert revenue to profit, not at the number of AI features.

5. Four numbers to watch next

If lawyers spend fewer hours on their work, is that bad for legal AI companies?
  • Not necessarily. If customers value the time saved and pay extra for it, AI providers can grow too. The key is how much of that value they can build into their prices.
Will the per-seat subscription model disappear?
  • It is better not to assume it will disappear right away. The thing to watch is whether an AI premium, or pricing based on the volume of work processed, gets added to existing seat fees.
Does having proprietary legal data guarantee high profitability?
  • Data and trust help with customer retention and pricing power. But if development costs and the cost of delivering AI services rise quickly, profitability can come under pressure.
What is the most important investment takeaway from these results?
  • Do not judge the quality of growth by the revenue growth rate alone. You need to check AI monetization, revenue per customer, costs and operating margin together.

What to watch

AI conversion rateThe share of existing customers that actually pay extra for AI features. A rise signals that commercialization is progressing.
Revenue per customerThe revenue earned from each customer after adopting AI. It needs to rise for the provider to be capturing part of the productivity value.
Cost of serviceA measure of how much costs rise alongside growing AI workloads.
Operating marginThe final check on whether revenue growth is turning into real profit improvement. If improvement is delayed, the economics of the growth need to be reexamined.
For AI software, watch how much profit remains from new revenue, not just how much revenue grows.

Insight Times Editorial Desk
More by topic

Starting with this story's topics, then what readers are following now

Investor psychology, decision-making and books on investing

Earnings Report

This story's topic39 storiesSee all →

SpaceX AI Revenue Jumps 830%, but Starlink Still Earns the Real Money

In its first quarter as a public company, SpaceX turned profitable and guided to as much as $40 billion in fourth-quarter capex. A possible Tesla merger adds another question for investors.

Investing

AMD Crossed $1 Trillion, and the Market Started Looking at CPUs Again

AMD's stock topped a $1 trillion market cap for the first time. The rally isn't just about being an Nvidia alternative. It reflects a reassessment of AMD as a full-stack AI infrastructure vendor, one that bundles CPUs, GPUs and networking, as AI shifts from chatbots to agents and reignites data center demand for CPUs.</deck> <parameter name="oneline">As AI moves from chatbots to agents, the market has started counting the CPU sitting next to the GPU again.

Tech

Lam Research Falls 12%: The Problem Is the Timing of AI Growth, Not Its End

Revenue up 54%, an operating margin above 40% and $3.2 billion in free cash flow were not enough. The selloff likely reflects worry that revenue arrives later than hoped.

Investing

TSMC Proved the AI Chip Boom Again. So Why Did the Stock Fall?

Third-quarter results beat expectations and fourth-quarter growth is guided higher. Investors should separate the substance of the AI investment cycle from market anxiety.

Investing

ASML Is Discussing 2030 Orders. How Long Can the AI Chip Supercycle Last?

Despite bubble worries, ASML sees equipment shortages through 2028. Investors should watch future production capacity, not just today's orders.

Tech

Meta's Ad Engine Is Strong. Now It Has to Prove the Return on AI

Revenue grew 26% and adjusted operating income rose, but free cash flow was negative $2.12 billion. The third-quarter story is less about AI bulls versus bears than about judging the ad business and the giant capital spending program separately.

Investing

If GPUs Are the Muscle, the Network Is the Nervous System

AI data centers do not get faster just by buying more GPUs. When thousands of accelerators cannot exchange data on time, the most expensive asset in the building sits idle. That is the whole investment case for Arista.

Investing

SaaS

This story's topic14 storiesSee all →

Renting software by subscription instead of buying and installing it.

OpenAI Leaves the Chatbot Behind: DevDay 2026 and the Fight Over Digital Labor

The new model mattered less than Dots, ChatGPT Space, plugins and the Marketplace. OpenAI wants to run agents that keep doing work people hand off, and to control distribution, payment and security around them.

Tech

AI Needs to Find $1 Trillion a Year From Somewhere to Pay Back Its Capex

Saying AI capex is big is no longer the point. The harder question is what end users have to pay for the buildout to pencil out, and Goldman Sachs puts that number at roughly $1 trillion a year.

Tech

Why Microsoft Rebuilt Copilot: AI Billing Shifts From Seats to Workload

The redesign is less about new features than about Microsoft expanding its enterprise AI revenue model beyond the per-seat subscription into task delegation and agent execution.

Tech

Grok 4.7's Real Weapon Isn't Performance, It's Cost Per Finished Task

At $2 per million input tokens and $6 per million output tokens, SpaceXAI is pitching Grok 4.7 as an agent model for long coding and knowledge work. The number investors should watch is not the benchmark leaderboard but the total cost of finishing a job and how widely it gets adopted.

Tech

AI's Second Act: Where the Money Goes After GPUs

Morgan Stanley's 24 "AI Adopter" stocks share one trait: not heavy AI usage, but the ability to convert AI into revenue, margin and cash flow.

Investing

Who Becomes the Windows of the Self-Driving Era?

Hyundai just pushed back its own autonomous driving timeline and turned to Nvidia first. The real story is not the delay, it is Nvidia's bid to become a common platform across the entire auto industry, not just a chip supplier.

Tech

ChatGPT Space Turns the Chat Window Into a Workroom

If you think of ChatGPT as a tool where you ask and it answers, Space changes that. Documents, sources and results now stay in one place, and people and AI can keep editing them for days.

Tech

Profit Margin

This story's topic8 storiesSee all →

Samsung Posts 107 Trillion Won Profit, TSMC Sales Jump 50%. Why Did the Shares Fall?

The AI chip supercycle has not ended. But the market's question has changed: not how fast earnings grow, but how long today's enormous margins can last.

Tech

Revenue

This story's topic9 storiesSee all →