AI Is Growing, but AI Stocks Are Breaking. What Is Wall Street Starting to Doubt?
Nvidia's revenue more than doubled, yet its shares fell about 14% in one day. As AI industry growth and AI stock returns diverge, long-term investors need to know what to trust and what to watch.
The 20-second read
1. Why did stocks break on good earnings?
If the AI industry keeps growing, should AI stocks keep rising? This week the US market put that familiar belief to a direct test.
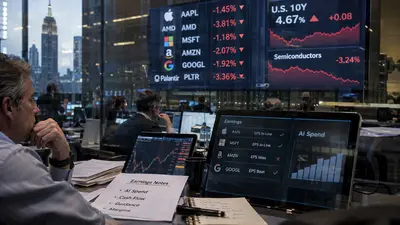
By the close of regular trading on Friday, Nov. 20, the S&P 500 was down more than 10% from its high, which puts it in correction territory. The Nasdaq fell about 10% over the week. Nvidia dropped about 14% on Friday alone. More surprising than the numbers is the earnings report that came just before.
Nvidia's third-quarter revenue for fiscal 2027 was $115.8 billion, up 103% from a year earlier. On those results alone, it is hard to argue that AI demand suddenly vanished. The market sold the stock anyway.
That contradiction is the core of the week. An AI industry can keep growing while AI stocks fall into a bear market. The future of a technology and today's price of a stock are not the same thing.
2. Is this a 2022-style break?
When selloffs run on, investors naturally think of 2022, when rates rose and the high expectations placed on growth stocks gave way. The similarity is that rate pressure and a repricing of stocks are showing up together again.
Similar does not mean the same ending. AI companies' actual revenue is growing fast, and demand for power and data center investment continues. The question is not whether the industry disappears. It is what price the market will put on that growth.
Stock prices reflect good news in advance. If expectations ran too high, a stock can fall even when the company does well. This decline is more convincingly read as a repricing of expectations than as an industry collapse.
Rather than declare a 2022 repeat, it is better to separate two questions: whether corporate earnings hold up, and whether financing strain spreads across the whole industry.
3. Is the correction nearly over?
Some say that after such a drop, a rebound is due. The S&P 500's forward price-to-earnings ratio, which compares the price with expected earnings over the next year, is about 17.7. One source rates that as a three-year low.
Stocks that were expensive are cheaper than before. But a lower price tag does not automatically make a bargain. If expected earnings fall too, the appeal of the stock changes again.
So there is little need to try to call the end of the correction. Sometimes the market stabilizes first. Sometimes earnings forecasts worsen and the decline drags on. Two sources assign different probabilities to their 6-to-12-month scenarios, but both put more weight on the base and bear cases than on the bull case.
A possible rebound and the end of a correction are different matters. Long-term investors should know the difference.
4. The real tests: rates, trust and debt
The first is rates. There is concern that the Federal Reserve could raise its policy rate further to bring down inflation. Core PCE inflation for September was 3.1% from a year earlier. That means inflation excluding volatile food and energy prices is not easing readily.
Markets are pricing a high probability of a 0.25-percentage-point hike at the Federal Open Market Committee meeting on Dec. 8-9, according to CME FedWatch. Yet on the day of the plunge, the 10-year Treasury yield fell to about 4.93% on safe-haven demand. That shows stocks can fall even as yields drop, if investors worry more about the economy and corporate risk.
The second is trust. One source reports Jensen Huang's resignation and an interim CEO arrangement under CFO Colette Kress. Another stresses a Reuters report on an SEC accounting probe and the management change. A report of an investigation does not mean wrongdoing has been established. The market is now asking about management stability and transparency of dealings, not only revenue growth.
The third is debt. Financing tied to SpaceX's AI chips totals about $44 billion. The yield on the related senior secured bonds was cited as 8.259%. The upside is the ability to expand AI capacity sharply. The burden is the high financing cost that comes with it. The lockup expiration for SpaceX shares and a large IPO supply, both scheduled for Dec. 8, are also variables on the supply side.
Rates, trust and debt look like separate problems, but they lead to one question: who will carry the cost of AI's growth, and at what price?
5. What to fear and what not to
The habit most worth guarding against is lumping all AI companies together. The least useful fear is reading this plunge as "the end of the AI industry."
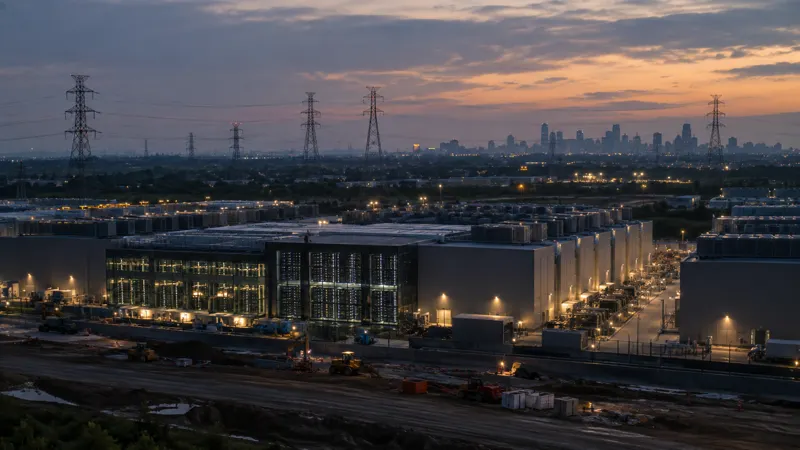
Forecasts from the US Energy Information Administration, the International Energy Agency and BlackRock all maintain the direction of rising power demand. The need for electricity and grids to run AI data centers does not disappear with one day's drop in prices. Some brokerages also call the plunge in memory chip stocks "excessive fear."
Rising power demand does not mean every related stock will rise. Even with solid memory demand, added supply can shake prices and profits. The growth potential of an industry and the returns on an individual stock have to be judged separately to the end.
The way to ease fear is not to seek only optimistic news. It is to check whether industry demand holds, and whether the companies you own actually profit from it.
6. Next week and beyond
On Wednesday, Nov. 25, US PCE inflation data is due. If inflation cools, rate pressure could ease. A hot reading could put pressure on growth stocks again. Then at the Dec. 8-9 FOMC meeting, what the Fed decides and how it describes the path of rates will matter. The SpaceX lockup expiration on the same Dec. 8 is another event the market must absorb.
The next 6 to 12 months are likely to be less about AI ending than about differences among AI companies becoming visible. The market is likely to value differently the companies that can keep growing without borrowing and those that urgently need their next round of funding.
For long-term investors who buy at regular intervals, a drop like this week's may be painful, but there is no reason to hand the whole investment plan over to one day's headline. Nor is there reason to judge everything at once from the lower prices alone. Keep to the planned time horizon and spare cash, check company earnings and balance sheets, and adjust the pace of staged buying.
News declares the end of the market, and a new beginning, with confidence every day. An investor's time horizon is longer than the news. Believing in the AI industry is not the same as believing every price of every AI stock. Those who keep that distinction are more likely to hold on to their own judgment in the next rally.
- The results were strong: revenue of $115.8 billion, up 103% from a year earlier.
- The stock still fell, and expectations that were already high likely played a part.
- Other factors are also cited, including pressure from interest rates, a management change, and reports of an accounting probe.
- It resembles 2022 in that interest rate pressure and a re-rating of growth stocks are overlapping.
- But AI companies' actual revenue is now growing fast, so it is hard to say it will end the same way.
- You need to separate whether corporate earnings hold up from whether financial strain spreads.
- A forward P/E of about 17.7 is seen in one source as a three-year low.
- But if expected earnings fall further, a price that looked cheap can change again.
- The chance of a rebound is a different matter from the correction being over.
- On the day of the plunge, the US 10-year yield fell to about 4.93% on a flight to safe assets.
- If investors worry more about the economy and corporate risk, stocks can fall even when rates fall.
- The US PCE inflation report is scheduled for November 25.
- The FOMC meets on December 8 to 9, and the SpaceX lockup expiration is also scheduled for the 8th.
What to watch
Insight Times Editorial Desk