Is Bitcoin Coming Back? A Recovery That Still Has to Prove Itself

Bitcoin has slipped from above $126,000 to around $83,000 while AI stocks hog the spotlight. It is up more than 40% from its summer low, but it is too early to call a new bull market.
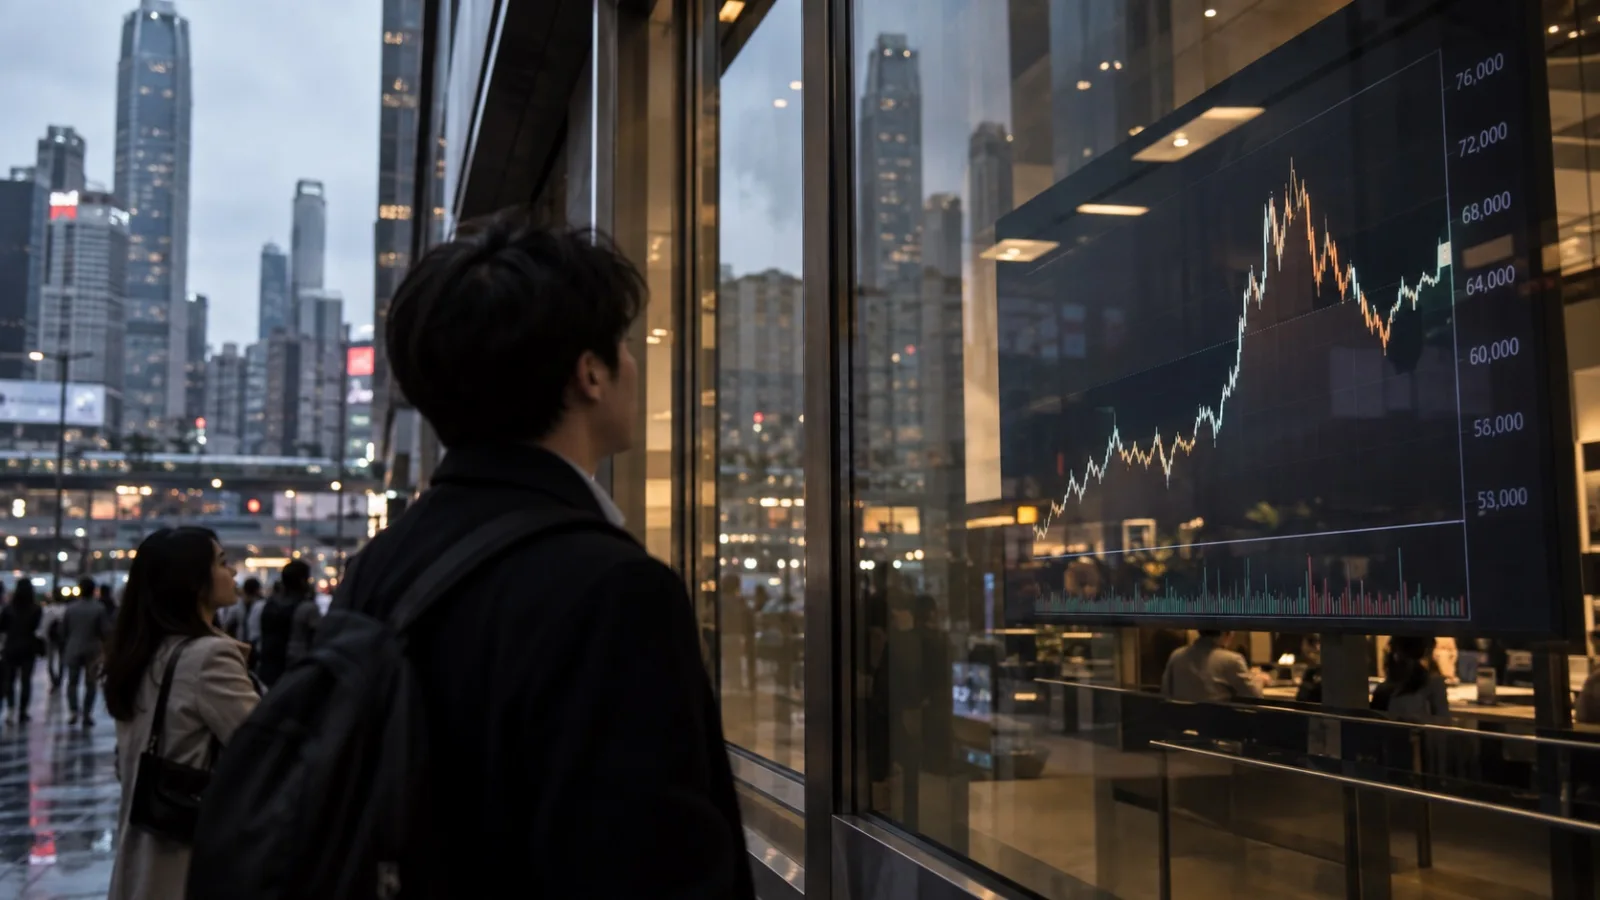
The desk's read: Bitcoin can rise again. But this looks less like the start of a new bull market and more like a stretch in which the recovery has to be proven.

While AI stocks absorb the market's attention, bitcoin has gone quiet. Its price, once above $126,000, has come down to around $83,000. Yet it is hard to call it a finished asset. It fell to around $58,000 this summer and has already bounced more than 40%.

Why has it gone so quiet?

Bitcoin is not a company. It does not report revenue and profit from selling AI chips, as Nvidia does. Holding it pays no dividend or interest. Its price rests on belief that people will accept it as a scarce digital asset and allocate more money to it over time.

That means attention follows price. When it rises, headlines multiply and new investors arrive. When it falls or drifts sideways for long, everyone moves on to another story. AI companies can point to earnings and growth forecasts. Bitcoin has to make its case through price and flows.

But less attention is not the same as a collapsed investor base. U.S. spot bitcoin ETFs have recorded cumulative net inflows of about $57.2 billion since launch. Still, new buying is unsteady. About $729 million left the funds over just two days, October 7 and 8.

Is waiting for the halving still enough?

In the past, the halving, which cuts new bitcoin issuance in half every four years, anchored bullish expectations. After the 2024 halving, the mining reward fell to 3.125 bitcoin per block. That works out to roughly 450 new coins a day.

The problem is that the market is far larger now. Institutional money moving in and out of ETFs, selling by existing holders and shifts in U.S. interest rates can move the price much more than a day's new supply. The halving still constrains supply, but it is not a buy signal.

Rate cuts work the same way. If inflation cools, rates fall and the dollar weakens, that is friendly for bitcoin. But if the Fed cuts in a hurry because of a recession, investors raising cash may sell bitcoin first.

If it is "digital gold," why does it swing so much?

Gold and bitcoin share scarcity. Bitcoin's supply is capped at 21 million coins. But unlike gold, which central banks have held for a long time, bitcoin has a short history and large price swings.

It is risky to assume bitcoin becomes a safe haven the moment a crisis hits, as gold does. More precisely, it is an asset that may hedge against currency debasement over the long run, but can fall sharply like a risk asset in the short run: a high-volatility candidate for digital gold.

Nor would a world of AI agents making payments automatically send money straight into bitcoin. When an AI agent buys data or services, the likelier first tools are dollar-linked stablecoins such as USDC and low-cost payment networks. Growth in the crypto industry should be separated from a rise in the price of BTC.

How high could it go?

Price map: conditional scenarios, not predictions

  • Bearish: If $80,000 breaks and ETF outflows continue, the price could fall into the $70,000s, and in a severe case retest $62,000 to $65,000.
  • Neutral: If the dollar and rates stay high and ETF flows are mixed, a long range between $80,000 and $97,000 is possible.
  • Bullish: If falling real yields and net ETF inflows appear together and the price clears $97,000, a move to $100,000 and then another attempt at the prior high near $126,000 is possible.

The $97,000 level is not a magic number. It rounds up a key valuation marker of about $96,700 identified by on-chain analytics firm Glassnode. Supply has piled up around past purchase prices, so clearing it needs real new buying behind it.

Four things to watch

  • Four-week cumulative flows into U.S. spot ETFs: whether institutional demand returns steadily, rather than in a one-day burst.
  • U.S. real yields and the dollar index: if both fall, the opportunity cost of holding bitcoin may ease.
  • Around $85,000 and near $97,000: whether breaks through resistance come with rising volume.
  • Whether $80,000 holds: a break combined with ETF outflows would mean rethinking the recovery scenario.

FAQ

Is this the bottom?

  • The summer low of $58,000 could be the final low, but that is not confirmed. A bounce alone does not establish a new uptrend.

Does bitcoin rise right away when the Fed cuts?

  • The reason for the cut matters. A cut amid stable inflation can be supportive, but a cut in response to recession may bring an initial sharp drop.

Is growth in AI payments good news for bitcoin?

  • The direct beneficiaries are likely to be stablecoins and payment infrastructure. For BTC, the more realistic path is an indirect benefit from wider adoption of digital assets.

What should long-term investors do?

  • Set a target allocation and a tolerable loss first, then build positions in stages. Watch ETF flows and the macro backdrop more than the price itself.

So can bitcoin come back? Yes, but it is too early to declare that it already has. The evidence for the next leg up will come not from bold forecasts but from new money that keeps buying bitcoin.

Price scenarios are forecasts and do not guarantee investment returns.

Bitcoin can rise again, but it is too early to say it has already recovered.

Insight Times Editorial Desk
More by topic

Starting with this story's topics, then what readers are following now

Investor psychology, decision-making and books on investing

Fed

This story's topic24 storiesSee all →

The central bank of the United States, carrying a dual mandate — stable prices…

Gas Prices, Not Politics, Are Deciding This Midterm Market Story

Forecasts of a Republican defeat are not exaggerated. The House has tilted clearly toward Democrats, the Senate has moved from a toss-up to a slight Democratic edge, and Trump's net approval is the lowest of either term.

Macro

It's Not Just Hormuz: Why the Middle East War Is Becoming a Fed Problem Again

The US-Iran ceasefire has already collapsed, and the risk no longer sits in the Gulf alone. With the Red Sea and Saudi Arabia's bypass pipeline now under threat too, an energy shock is spreading into prices, the Fed, and growth-stock valuations.

Macro

AI Is Growing. Why Are AI Stocks Falling?

Chip demand is strong, yet prices are wobbling. In October 2026 the market is asking not how fast AI grows, but how quickly the capital behind that growth returns as cash.

Investing

Stocks Bounce, but the AI Selloff May Not Be Over: A Two-Week Playbook

The Dow rose more than 1% while the Nasdaq barely moved and semiconductors kept falling. A W-shaped retest looks more likely than a V, and the task now is surviving the next drop.

Investing

S&P 500 Slips 0.22%, but 73% of the Market Fell

Long-term yields above 5% weighed on small caps and semiconductors on Oct. 7. A strong 10-year Treasury auction and a few large tech names limited the index's losses.

Tech

10-Year Yield at 5.34%: The Problem Isn't a Missing Buyer, It's the Price

Washington and the AI industry are pulling in huge sums at once, and the bond market is demanding higher yields to absorb it. Equity investors now need to watch long-term rates, financing costs and AI payback alongside the Fed's next move.

Macro

Weekly Check: The AI Bull Market Isn't Over, It's Just Gotten Harder

A 5% 10-year yield, 470 gigawatts stacked up in Texas, Chinese DRAM, and whether data centers actually get switched on are starting to decide who wins the AI trade through 2027.

Tech

BTC

This story's topic6 storiesSee all →

HBM

75 storiesSee all →

Memory stacked next to the GPU.

Has Memory Peaked? Prices Are Cooling, but the Shortage Looks Set to Run to 2028

Price growth has slowed and consumer demand is already breaking. Server and HBM supply remains short, and Micron says more than 75% of its 2027 volume is already committed to customers.

Tech

AI Chip Peak Check: Demand Still Rising, Risk Building in 2027-2029 Supply and Funding

DRAM and NAND contract prices are still climbing and HBM suppliers hold the edge. Power shortages, AI financing costs and simultaneous memory expansion are the risks for later years.

Investing

US AI Data Centers Are Headed for 90GW. Gigawatts Now Matter More Than Dollars

Goldman Sachs expects US data center capacity to grow from 64GW at the end of 2026 to 90GW at the end of 2027. The AI race is moving from buying GPUs to building power plants and transmission lines alongside them.

Tech

2027 Isn't the End: Citi's Case for a Memory Supercycle Running to 2031

Citi says the memory shortage timeline is stretching again. If AI shifts from "train once" models to continual learning, HBM, server DRAM and enterprise SSDs could all fall short at the same time.

Tech

AI Chips Haven't Peaked. The Real Risk Sits in 2028 Supply

HBM and server DRAM shortages are now spreading into enterprise SSDs. The question isn't today's strength, it's how much new capacity these prices are pulling in and when it lands.

Investing

Memory Chip Supercycle: Not at Peak Yet, But 5 of 6 Warning Signs Are Flashing

Memory prices are still climbing, but the pace is slowing and PC and smartphone demand is starting to crack under the weight of higher chip costs. This looks less like a price peak and more like a profit plateau building toward the next supply cycle.

Investing

2027 Investing Needs Alignment, Not Prediction

A new investing book argues the hard part was never picking the next winner. It's staying aligned with where value and bottlenecks are moving while keeping old human weaknesses in check.

Investor Mind

A building that houses servers and networking gear and supplies them with powe…

Why the White House Swapped "AI" for "Super Intelligence"

Executive Order 14434 renames AI across the federal government without defining a new technology. The real story is about roughly $700 billion in capex, free cash flow and electricity.

Tech

Nvidia's Next Target After GPUs: Controlling What AI Agents Are Allowed to Do

OpenShell and Sentry are not about policing what an AI says. They are about controlling, at the server infrastructure level, which files and APIs an AI can touch, what it can execute, and who can actually pull the plug when something goes wrong.

Tech

AMD Crossed $1 Trillion, and the Market Started Looking at CPUs Again

AMD's stock topped a $1 trillion market cap for the first time. The rally isn't just about being an Nvidia alternative. It reflects a reassessment of AMD as a full-stack AI infrastructure vendor, one that bundles CPUs, GPUs and networking, as AI shifts from chatbots to agents and reignites data center demand for CPUs.</deck> <parameter name="oneline">As AI moves from chatbots to agents, the market has started counting the CPU sitting next to the GPU again.

Tech

Why Nebius Is Keeping Some 2027 AI Capacity Off the Shelf

Nebius mixes long-term contracts, short-term premiums and auctions. Holding back capacity pays only if the servers stay busy, and it is not yet clear the pricing will last.

Tech

DeepSeek's $15 Billion Raise: Model Makers May Feel It Before Nvidia Does

China's DeepSeek is closing a round about twice its original target. For US investors, the question is less the size of the check than where the money goes and whose profits it could erode.

Tech

Tesla Energy's 13.7GWh Paradox: Expectations Ran Faster Than Deployments

Q2 deployments recovered but margins collapsed. Q3 set a record for deployments and still missed estimates. The issue is not the size of AI power demand but how fast it converts into Tesla revenue and profit.

Tech

Why Nvidia Is Happy to Help Make AI Models Nearly Free

Falling model prices can squeeze model makers. For Nvidia, the number that matters is the total volume of tokens generated worldwide and the compute that produces them.

Tech