Nvidia Revenue Jumps 103%, but the Bigger Number Is $518 Billion
Nvidia's third-quarter revenue topped $115.8 billion, and guidance points to $130 billion next quarter. The question now is how much of that growth turns into profit and cash.
The 20-second read
Nvidia's third-quarter fiscal 2027 revenue topped $115.8 billion. That was up 103% from a year earlier and about 6.2% above market expectations. The company guided to $130 billion in revenue for the next quarter.
Bottom line: Demand is confirmed again. What matters now is how much of that revenue remains as profit and cash.
Revenue exploded. The quality of growth is the next test
The bigger surprise is the coming fiscal year. The company raised its FY2028 revenue growth outlook to 75% from 70%.
Combine revenue through the third quarter with the midpoint of fourth-quarter guidance, and FY2027 revenue comes to about $423.7 billion. Apply 75% growth, and FY2028 revenue reaches about $741.4 billion.
That is not an absolute-dollar forecast from the company. It is arithmetic built from published figures. Still, the scale is clear. On this revenue base, each percentage point of growth equals about $4.2 billion in added revenue.
The fourth quarter also contains one extra week. Nominal revenue growth from the prior quarter is about 12.2%. A simple adjustment for 13 weeks versus 14 puts weekly revenue growth at about 4.2%. Higher revenue and a real acceleration in the business are not the same thing.
Revenue up 12%, operating profit up 6%?
Even with a strong product, margins can move the other way.
Non-GAAP gross margin was 74.9% in the third quarter. The fourth-quarter outlook is 71% to 72%. The company expects to recover to 72% to 73% in FY2028, which does not mean a full return to the current level.
Q3 results vs. Q4 guidance midpoint (non-GAAP, $ billions)
| Q3 actual | Q4 estimate | |
|---|---|---|
| Revenue | 115.844 | 130 |
| Gross profit | 86.724 | 92.95 |
| Operating income | 77.883 | 82.25 |
Q4 operating income is an arithmetic estimate combining guidance figures.
Using the same guidance, fourth-quarter revenue rises about 12.2%, but non-GAAP operating income could grow only about 5.6%.
Behind the margin pressure is a timing gap between higher supply costs and the prices promised to existing customers. The key issue ahead is less the supply shortage itself than how quickly higher costs get reflected in prices for new sales.
$518 billion: a safety net for growth or a future burden?
The number investors should study most closely in this report is forward commitments.
| Commitment | Amount |
|---|---|
| Supply and capacity | $390 billion |
| Leases not yet commenced | $74 billion |
| Cloud | $28 billion |
| Equity investments | $20 billion |
| Capital expenditures | $6 billion |
These are commitments spanning several fiscal years, not total current debt.
The total is $518 billion. Supply and capacity commitments account for $390 billion, up about 40% from $279 billion in the prior quarter. The main driver is multiyear contracts to secure memory supply.
In the short term, that can be a competitive edge by reducing production disruptions. But if demand turns out weaker than expected, contracts already signed could become a burden.
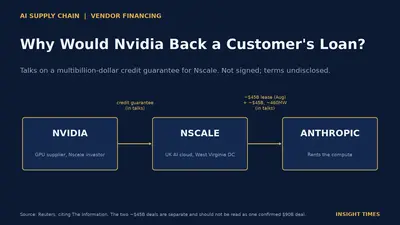
There are also separate neocloud commitments of up to $32 billion and credit guarantees of up to $118 billion. Of the guarantees, $105 billion relate to SB Energy and take effect in stages after data centers are completed and ready to operate.
It would be wrong to add all of these up and call them hidden debt. Future purchase commitments and contingent guarantees are different in nature. But the fact that cash has not yet gone out does not mean there is no risk.
Nvidia is now an AI chip supplier that also takes part in supplying capital and allocating risk across the AI infrastructure ecosystem. The yardsticks for valuing the company need to widen as well.
How fast revenue turns into cash
Third-quarter free cash flow was very strong, at about $43.8 billion.
But accounts receivable rose to $81 billion, and days sales outstanding (DSO) lengthened to 64 days from 60 in the prior quarter. The company cited the timing of Rubin shipments and extended payment terms for some high-quality customers.
A longer collection period does not immediately signal bad debt. But in an environment of expanding supply commitments and customer financing, the speed of cash collection matters as much as revenue growth.
Inventory also rose, to about $39.7 billion. Much of it is raw materials and work in process for new-product ramps, so it cannot be read as weak sales. Finished-goods inventory and reserves should be watched together going forward.
Rubin and the CEO change: two different timetables
Revenue in Rubin's first shipping quarter was about $20 billion. According to the company, the time for major customers to move into actual operation is also shorter than on the prior platform.
This is not simply a matter of supplying more GPUs. If the time shrinks between a customer installing equipment and running a revenue-producing AI service, the economic incentive for further infrastructure spending could grow.
Separately, Jensen Huang resigned on Nov. 12, but the quarter covered by these results ended Oct. 25. These numbers alone make it hard to judge how well interim CEO Colette Kress is running the company.
Nvidia's board created a National Security and Export Control Oversight Committee. That also suggests the company should be judged not only on future earnings but on how it handles export restrictions, retains key staff, manages new-product transitions and keeps customer relationships.
Conclusion
What matters is not only how many GPUs Nvidia can sell. The next yardstick is how profitably it turns that revenue into cash, and how well it controls the capital and credit risk that growth requires.
The strength of demand has been reconfirmed. What remains to be tested is the quality of the capital behind that growth, and whether the organization can execute without its founder at the helm.
- No. It is the total of multiyear commitments tied to purchases, cloud services, leases, investments and facilities. Payment timing, whether the commitments can be canceled, and contractual obligations each need to be considered separately.
- Revenue growth and stock returns are different things. The share price is determined by profitability, cash flow, the discount rate, and the expectations already built into current valuation.
- It is hard to judge from this quarter's numbers alone. The medium- to long-term yardsticks are retention of key talent, execution on platform transitions, and bargaining power with customers and regulators.
- Gross margin and cash collection keep deteriorating even as revenue grows, and customer financing support or inventory burdens pile up. A decline in the quality of growth may show up before a slowdown in the growth rate.
What to watch
Insight Times Editorial Desk