SpaceX AI Revenue Jumps 830%, but Starlink Still Earns the Real Money
In its first quarter as a public company, SpaceX turned profitable and guided to as much as $40 billion in fourth-quarter capex. A possible Tesla merger adds another question for investors.
Is SpaceX now an AI infrastructure company?
SpaceX once launched rockets and sold satellite internet. Now its biggest revenue line is AI computing.
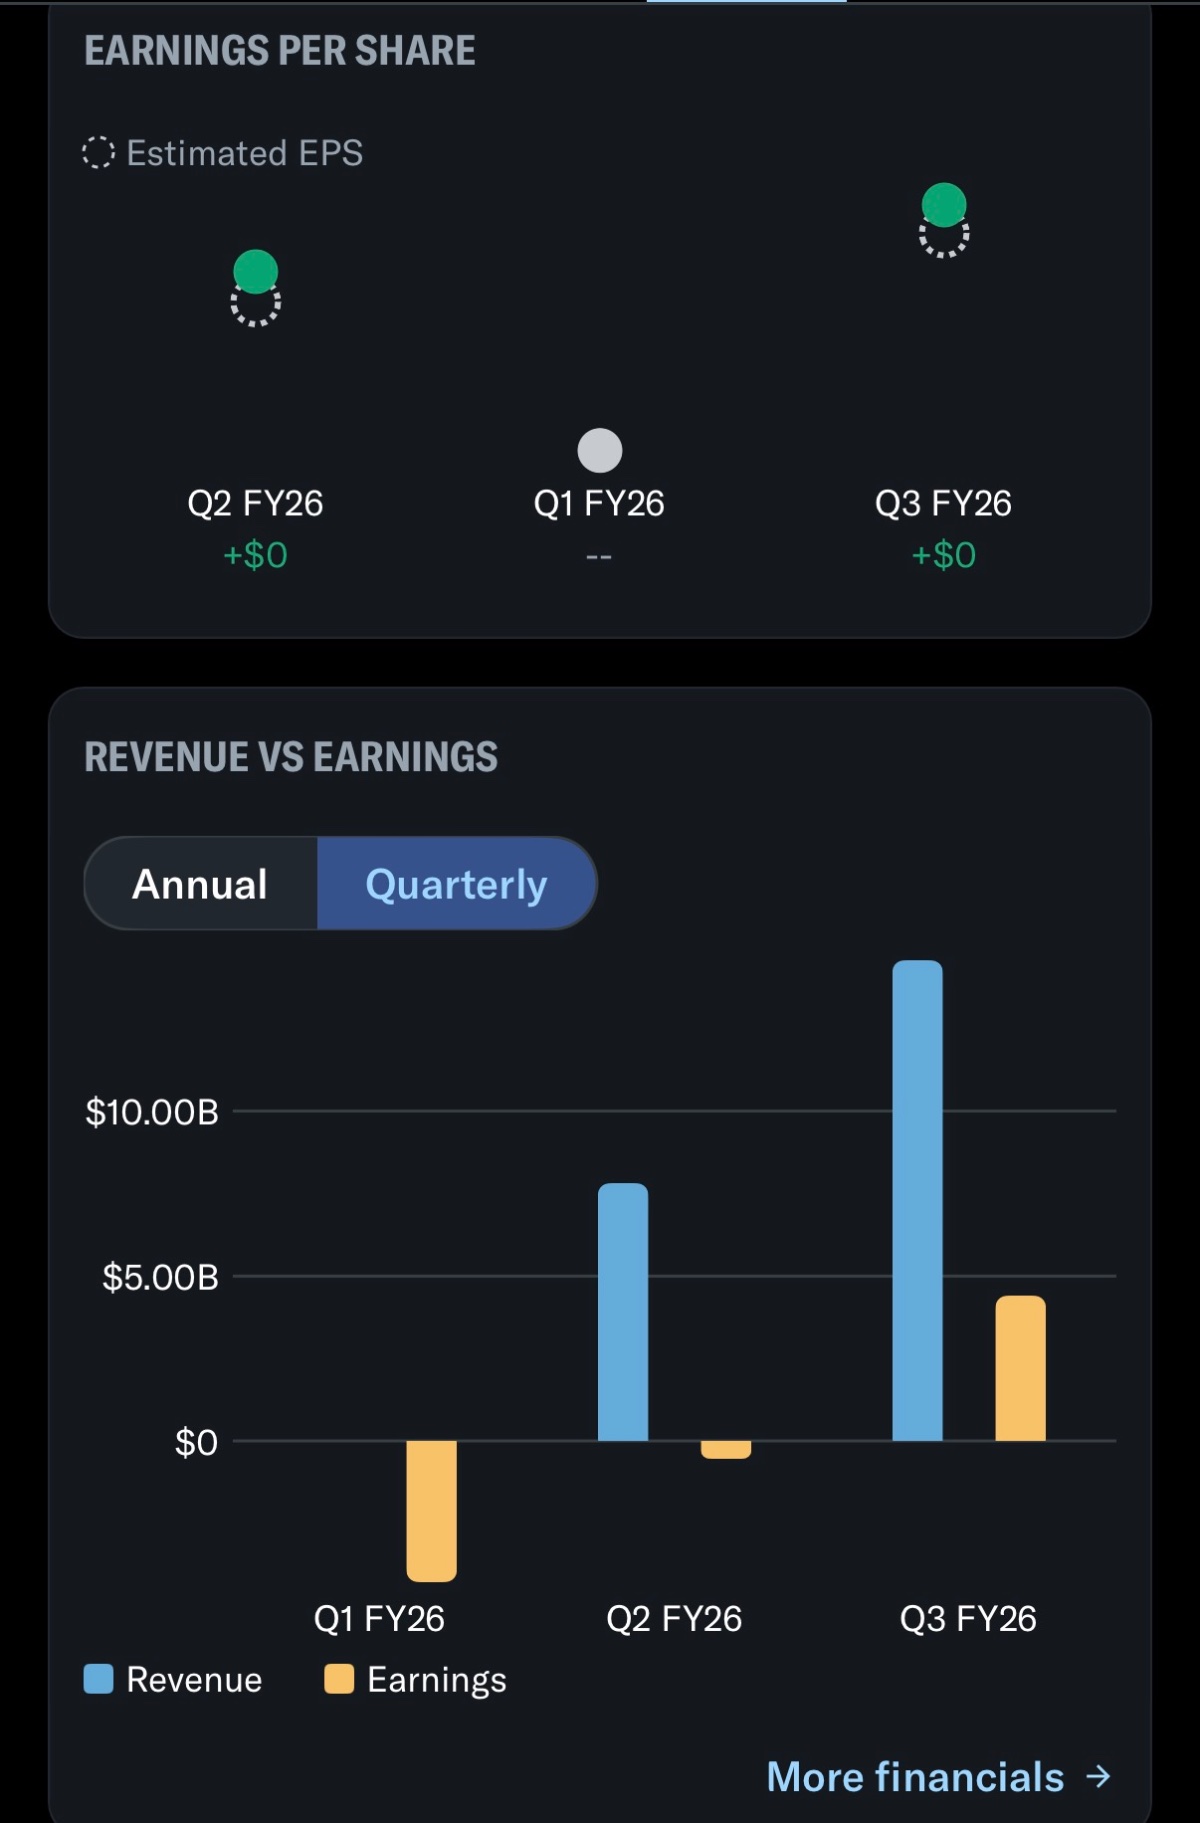
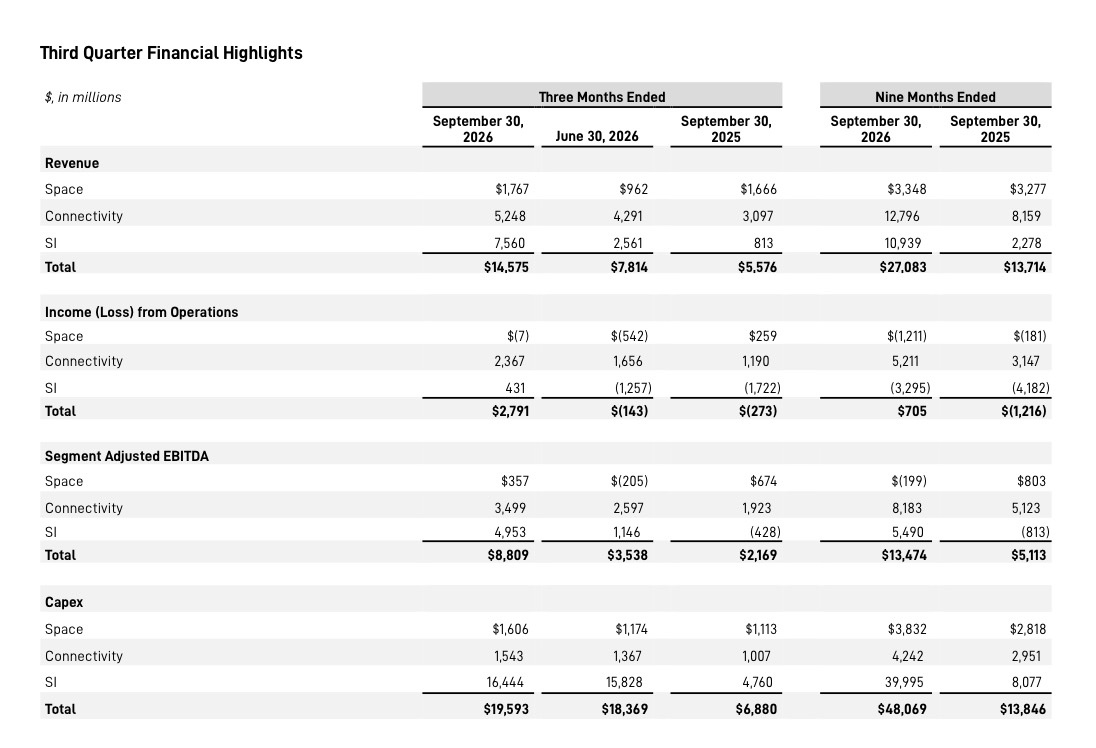
Third-quarter 2026 results, released Oct. 20, showed revenue of $14.575 billion and net income of $4.404 billion. A year earlier the company posted a net loss of $1.054 billion. Adjusted earnings per share of $0.45 far exceeded the $0.13 analysts expected.
Split by segment, the picture changes.
| Segment | Q3 revenue | Operating margin |
|---|---|---|
| Super Intelligence | $7.56 billion | 5.7% |
| Connectivity | $5.25 billion | 45.1% |
| Space | $1.77 billion | -0.4% |
SpaceX Q3 2026 segment results. Operating margin is segment operating income divided by revenue.
Revenue at the AI business, Super Intelligence, jumped from $813 million a year earlier to $7.56 billion. Its operating income was $431 million. Connectivity earned $2.367 billion in operating income.
The AI unit has more revenue, but Connectivity produced about 5.5 times as much operating profit.
That is why SpaceX's growth business and its profit business need to be evaluated separately.
Who is the AI business's real customer?
Reading the AI growth only as a Grok success misses the point.
A large share of the revenue increase came from leasing data center computing capacity to companies such as Anthropic, Google and Reflection AI. SpaceX is becoming both an AI model developer and an infrastructure provider to other AI firms.
Cursor, the AI coding tool SpaceX acquired in August, added about $608 million in revenue through the end of September. Acquired revenue should be separated from organic growth. The AI segment also absorbed about $1.2 billion in stock-based compensation tied to the Cursor deal.
To judge SpaceX as a computing supplier, utilization rates, customer contract length, lease pricing and equipment replacement costs are more useful than the number of GPUs it has secured.
Starlink: profitability matters more than growth
Starlink has 13.6 million consumer subscribers, up 1.6 million from the prior quarter. Average monthly revenue per user (ARPU) is $69. That is below $83 a year earlier but up from $66 last quarter.
As expansion into new regions adds lower-priced plans, ARPU can fall. What matters is how far subscriber growth and larger business and government customers offset that.
Connectivity revenue rose 69% year over year while operating income rose about 99%. That is a positive sign that margins improve with scale.
Cash profitability, once satellite construction, launch and replacement costs are counted, should be judged separately from segment operating income.
A $4.4 billion profit, yet $35 billion of cash shortfall over nine months
Capital spending is the number that deserves the most caution in this report.
- Q3 capex: $19.59 billion, up about 185% year over year
- AI share of Q3 capex: 83.9%
Cash flow and capex, January to September 2026
- Operating cash flow: +$13.097 billion
- Capital expenditure: -$48.069 billion
- Simple cash flow after capex: -$34.972 billion
Based on the SEC cash flow statement. This is operating cash flow minus purchases of property and equipment, not an adjusted free cash flow measure disclosed by the company.
The return to profit is real, but it does not mean cash generation has caught up with the pace of investment. Fourth-quarter capex is guided higher, to $35 billion to $40 billion.
There is no need to read this as an immediate liquidity problem. At the end of September SpaceX held about $51.3 billion in cash and equivalents and about $38.6 billion in marketable securities. Proceeds from the public listing also strengthened its balance sheet.
The question for investors is less the cash burn itself than when, and how much, this heavy upfront spending turns into recurring cash earnings.
Starship's success is not the same as the value of future businesses
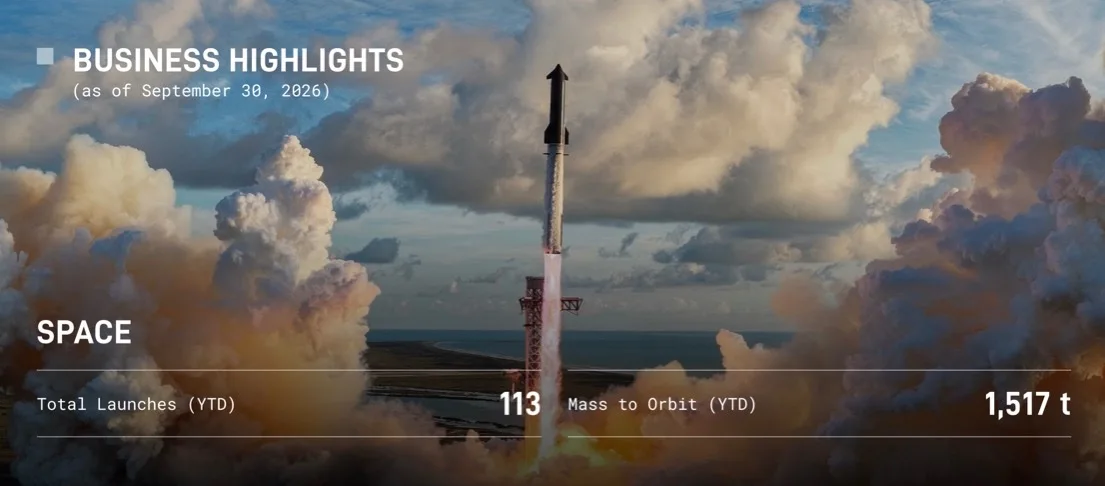
SpaceX said Starship's 14th flight placed 26 Starlink V3 satellites in orbit. As a revenue-generating mission, it is meaningful technical progress.
Repeat launches, full reuse and stable operating costs have not been proven, however. The same goes for the space data center concept: technical feasibility and commercial viability are different things.
It is important not to stack the value of future businesses on top of results already confirmed.
A Tesla-SpaceX merger: who benefits?
Elon Musk said a special committee from both companies is reviewing a possible merger. A deal is not confirmed, and neither a valuation nor an exchange ratio has been announced.
SpaceX's growth could appeal to Tesla shareholders, since the two could cooperate on AI computing, autonomous driving, robotics and communications infrastructure.
But potential synergies do not guarantee higher value per share.
The outcome could disappoint if Tesla pays too high a price, issues large amounts of new stock that dilutes existing holders, or takes on SpaceX's AI investment burden.
Conversely, with a reasonable exchange ratio and clear financial responsibility, cost savings and business expansion could create value.
So the question for Tesla investors is not whether SpaceX is a good company. It is at what price and on what terms a combination raises Tesla's value per share.
Insight Times Editorial Desk