Is Microsoft Really an AI Winner? The Key Is Where Work Starts, Not the LLM

Azure grew 48% and Microsoft still produced $18.6 billion in free cash flow. But its long-term edge depends less on model rankings than on where people begin their work and who they pay.
The 20-second read

1
Growth and cash together: In the first quarter of fiscal 2027, revenue was $92.3 billion, Azure grew 48%, and free cash flow was $18.6 billion. The company kept its cash generation even as AI spending expanded.
2
Work standards matter more than the AI model: Even if its own LLM is not the best, Microsoft can sell AI through Excel, Word, PowerPoint, enterprise data, and its permission management systems.
3
The key long-term risk: Customer access and pricing power depend on whether users apply AI inside Microsoft 365, or finish their work in outside AI such as ChatGPT and Claude and only bring the files back.

1. Wall Street prized cash generation more than AI growth

Microsoft's fiscal first-quarter 2027 revenue (July to September 2026) was $92.3 billion, up 19% from a year earlier. Azure revenue reached $33.17 billion, up 48%. The company guided to 49% to 50% Azure growth next quarter in constant currency.

Operating cash flow was $58 billion. Free cash flow (FCF) was $18.6 billion. Microsoft left a sizable amount of cash even while spending heavily on AI.

MetricFigureChange
Quarterly revenue$92.3 billion+19% year over year
Azure growth+48%year over year
Operating cash flow$58 billion+29% year over year
Free cash flow$18.6 billionabout -27% year over year

Microsoft FY2027 Q1. Figures rounded.

A closer look at cash flow shows a different picture.

Quarterly capital spending was $45.2 billion. Delays in infrastructure deliveries from some outside suppliers played a part, and the company expects capex above $50 billion next quarter.

The $45.2 billion includes finance leases. Cash paid for property and equipment was about $39.4 billion. Subtract that from operating cash flow and the result is the $18.6 billion in free cash flow.

The key point is that free cash flow fell about 27% from a year earlier. It was better than the market expected, but cash flow itself did not improve.

Microsoft's strength in the AI buildout is a reliable cash-generating base. Still, the fact that existing businesses can fund AI spending is not the same as AI spending earning a high return.

2. Why Microsoft can make money without the best LLM

One question comes up often when Microsoft's AI strategy is assessed.

If its own LLM is not better than the top models from OpenAI, Anthropic and Google, does its competitiveness weaken over the long run?

Microsoft is developing its own models, including MAI-Thinking-1. It also uses outside models in its Copilot products. The agent in Microsoft 365 Copilot that creates Word, Excel and PowerPoint files uses an Anthropic model.

This structure is both a weakness and an opportunity.

Heavy reliance on outside models exposes Microsoft to suppliers' pricing and contract terms. But if it can choose and swap models, it can tune quality and cost to the task.

The yardstick for the value of its own models changes too. They do not need to rank first on every benchmark. Handling repetitive enterprise work at lower cost, and so lifting the margin on the service, is enough to create economic value.

The key, then, is not the rank of Microsoft's own LLM but its bargaining power with model suppliers and the unit cost of its AI services.

3. Azure is smaller than AWS. Is it still competitive?

Global cloud infrastructure market share in the third quarter of 2026 was estimated at 26% for AWS, 19% for Microsoft and 16% for Google. AWS's scale advantage is clear.

But market share, growth and return on investment are different measures.

Azure is winning new demand quickly, growing 48%. About three-quarters of this quarter's capex, however, went to relatively short-lived assets such as CPUs and GPUs. That structure could mean heavier depreciation and equipment replacement costs ahead.

A cloud company's competitiveness does not end with how many servers it secures. What matters is how heavily it uses those servers and how much profit remains after costs and depreciation.

4. The real moat is in Excel, Word and PowerPoint

To understand Microsoft's long-term position, it helps to look away from LLMs and the cloud.

Why do so many companies around the world still use Excel, Word and PowerPoint?

It is not because cheaper alternatives are missing. Corporate documents, financial models, macros, data connections and approval processes are already built around these tools.

A financial firm that wants to move off Excel, for example, cannot just convert file formats. It must verify existing calculations, external data links, macros and compatibility with clients.

That is switching cost.

Microsoft's strength is not that people like Excel. It is that replacing Excel means an organization must change too many other things at once.

If that structure holds in the AI era, Microsoft can have a chance to monetize AI without building the best LLM itself.

5. Where work starts matters more than how smart the AI is

An AI that writes a good answer is different from an AI that performs real corporate work.

Corporate work requires access to documents and data, user permissions, security policies, review and approval, and collaboration. Microsoft 365 integrates Copilot into that work environment.

Two scenarios then split how AI value gets divided.

Scenario A: Microsoft 365 is where work starts

  • Work starts in Excel, Word and Teams within Microsoft 365.
  • Copilot plus outside and in-house AI models supply the intelligence inside the existing work environment.
  • Outcome: Microsoft keeps the customer relationship and gets a chance at added AI revenue.

Scenario B: an outside AI is where work starts

  • Work starts in ChatGPT, Claude or Gemini: analysis, drafting, editing and review.
  • Results are handed off as Excel and Word files, and Office becomes the final editing tool.
  • Outcome: the customer relationship shifts, and pricing power comes under pressure.

In the first scenario, AI raises the value of Office. Microsoft keeps its existing customer relationships and can charge extra.

In the second, even if the Office file format survives, the place users pay may be the outside AI.

The difference is decisive.

Keeping the standard file format is not the same as controlling where work begins.

It is not known how many top model developers will remain. More important is whether they stay Microsoft's technology suppliers or become competitors that win enterprise customers directly.

Conclusion: When models change, where does work start?

Microsoft's competitiveness cannot be explained by a single top-performing LLM. It combines the cash-generating power of existing businesses, enterprise customer relationships, cloud infrastructure and work standards built up over decades.

Whether AI becomes a feature that makes Office stronger, or turns Office into a mere tool for processing output, is not yet settled.

For individual investors assessing Microsoft, the question is this.

If AI models keep changing, will people still start their work in Microsoft? And can Microsoft turn that customer relationship into lasting profit and cash flow?

This quarter's results lent support to that possibility. Long-term investment returns will likely depend on how that question is answered, and on how much of the answer the current share price already reflects.

If Microsoft's own LLM is not the best, is that a long-term disadvantage?
  • There is a risk of higher fees for outside models and greater technical dependence. On the other hand, choosing among model suppliers and handling some tasks with its own models could strengthen Microsoft's cost bargaining power. The key test is not whether it owns the top-performing model, but total cost relative to service quality, and customer retention.
AWS has the No. 1 market share, so is Azure still attractive as an investment?
  • AWS leads at its current scale. Azure is winning new demand with its high growth rate. Long-term value is determined not only by market share but also by infrastructure utilization, depreciation, operating profit, and cash flow.
Can AI agents fully replace Excel?
  • AI's role in creating and editing Excel files can expand. But replacing a company's existing data connections, calculation checks, permission management, and collaboration environment is a separate contest. The survival of the file format should be distinguished from the pricing power of the Excel program.
Capital spending came in lower than expected. Isn't that a positive sign?
  • Some spending moved into the next quarter because of delays in outside infrastructure deliveries. The company's outlook for next quarter's capital spending is above $50 billion. A more important test is whether Azure growth and free cash flow hold up together afterward.
What should a long-term investor check first?
  • Whether growth in paying Copilot customers and usage turns into real additional profit. Whether Microsoft 365's customer access and pricing power hold. Whether the current share price is reasonable relative to expected profit and cash flow growth.

What to watch

Key indicatorsItems to track.
Criteria for judgmentHow to read them.
Copilot paid adoptionAre actual usage, paid seats, renewals, and add-on revenue growing?
AI business profitabilityCan Microsoft keep its profit margin while covering model fees and infrastructure costs?
Capital spending and FCFDoes cash generation hold up after quarterly spending of $50 billion or more?
Change in where work startsDo enterprise users start work in Microsoft 365, or move to outside AI?
ValuationWill future growth in profit and cash flow meet the growth expectations built into the current share price?
Portfolio-wide exposure to the AI investment cycleThis should be reviewed too. The GPUs and memory Microsoft buys become revenue for Nvidia and the semiconductor supply chain. Even if you spread your money across several companies, you may still be exposed to the same AI capital spending cycle.
Microsoft's fate is likely to turn less on AI model rankings than on where people start their work.

Insight Times Editorial Desk
More by topic

Starting with this story's topics, then what readers are following now

Investor psychology, decision-making and books on investing

Cloud Computing

This story's topic14 storiesSee all →

Why Nebius Is Keeping Some 2027 AI Capacity Off the Shelf

Nebius mixes long-term contracts, short-term premiums and auctions. Holding back capacity pays only if the servers stay busy, and it is not yet clear the pricing will last.

Tech

Anthropic Talked Slowdown. Its Actions Say Otherwise

A next-gen Claude model, an IPO push, and an actual biology lab. Put the three together and Anthropic's message isn't "stop AI." It's build stronger models while scaling up verification and control at the same pace.

Tech

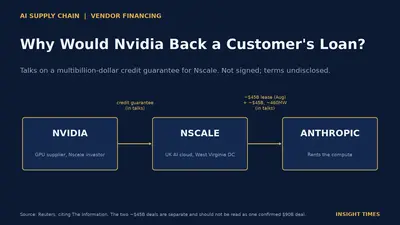
Dark navy cover. Flow diagram: Nvidia to Nscale (credit guarantee, in talks) to Anthropic (~$45B compute lease signed in August plus a separate ~$45B, ~460MW deal in talks). Title: Why Would Nvidia Back a Customer's Loan?

Why Would Nvidia Guarantee Its Customers' Data Center Loans?

Nvidia is reportedly in talks to back financing for Nscale's West Virginia data center. Nothing is signed, and the terms are not public.

Tech

AI Needs to Find $1 Trillion a Year From Somewhere to Pay Back Its Capex

Saying AI capex is big is no longer the point. The harder question is what end users have to pay for the buildout to pencil out, and Goldman Sachs puts that number at roughly $1 trillion a year.

Tech

Same cloud, three different ways to earn the money back

Microsoft, Alphabet and Amazon are all spending enormous sums on AI infrastructure. The route each one takes to recover that capital is not the same, and that is what decides the winner.

Investing

Why Microsoft Rebuilt Copilot: AI Billing Shifts From Seats to Workload

The redesign is less about new features than about Microsoft expanding its enterprise AI revenue model beyond the per-seat subscription into task delegation and agent execution.

Tech

AI Was Supposed to Live in the Cloud. Apple Is Bringing It Back to the Desktop.

Four Mac Studios running a trillion-parameter model matters less than the economics behind it: heavy, repeated AI use can make owning compute cheaper than renting it by the token.

Tech

HBM

75 storiesSee all →

Memory stacked next to the GPU.

AI Chip Peak Check: Demand Still Rising, Risk Building in 2027-2029 Supply and Funding

DRAM and NAND contract prices are still climbing and HBM suppliers hold the edge. Power shortages, AI financing costs and simultaneous memory expansion are the risks for later years.

Investing

Has Memory Peaked? Prices Are Cooling, but the Shortage Looks Set to Run to 2028

Price growth has slowed and consumer demand is already breaking. Server and HBM supply remains short, and Micron says more than 75% of its 2027 volume is already committed to customers.

Tech

The Real ASML Number Isn't the 3% Pop, It's the 30% Capacity Hike

ASML's rally isn't just an AI trade. Customers are already locking in 2027 tool slots, and ASML is raising Low-NA EUV capacity by roughly 30% to keep up.

Investing

2027 Isn't the End: Citi's Case for a Memory Supercycle Running to 2031

Citi says the memory shortage timeline is stretching again. If AI shifts from "train once" models to continual learning, HBM, server DRAM and enterprise SSDs could all fall short at the same time.

Tech

AI Chips Haven't Peaked. The Real Risk Sits in 2028 Supply

HBM and server DRAM shortages are now spreading into enterprise SSDs. The question isn't today's strength, it's how much new capacity these prices are pulling in and when it lands.

Investing

The Next AI Chip Race Is About How Chips Connect

Applied Materials will lift its stake in Dutch equipment maker BESI from about 9% to 20%. The bet is less about control than about a new way to link chips.

Tech

US AI Data Centers Are Headed for 90GW. Gigawatts Now Matter More Than Dollars

Goldman Sachs expects US data center capacity to grow from 64GW at the end of 2026 to 90GW at the end of 2027. The AI race is moving from buying GPUs to building power plants and transmission lines alongside them.

Tech

A building that houses servers and networking gear and supplies them with powe…

Nvidia and Palantir Put AI Inside the Supply Chain - The Real Shift Is That It's Learning Judgment

A single Vera Rubin rack holds 1.3 million parts. The real breakthrough in Nvidia and Palantir's new supply chain AI isn't automating that complexity, it's capturing the judgment calls that used to live only in planners' heads.

Tech

Why the White House Swapped "AI" for "Super Intelligence"

Executive Order 14434 renames AI across the federal government without defining a new technology. The real story is about roughly $700 billion in capex, free cash flow and electricity.

Tech

2027 Investing Needs Alignment, Not Prediction

A new investing book argues the hard part was never picking the next winner. It's staying aligned with where value and bottlenecks are moving while keeping old human weaknesses in check.

Investor Mind

AMD Crossed $1 Trillion, and the Market Started Looking at CPUs Again

AMD's stock topped a $1 trillion market cap for the first time. The rally isn't just about being an Nvidia alternative. It reflects a reassessment of AMD as a full-stack AI infrastructure vendor, one that bundles CPUs, GPUs and networking, as AI shifts from chatbots to agents and reignites data center demand for CPUs.</deck> <parameter name="oneline">As AI moves from chatbots to agents, the market has started counting the CPU sitting next to the GPU again.

Tech

DeepSeek's $15 Billion Raise: Model Makers May Feel It Before Nvidia Does

China's DeepSeek is closing a round about twice its original target. For US investors, the question is less the size of the check than where the money goes and whose profits it could erode.

Tech

AI Data Centers Are Rewriting Contracts While They Wait for Power

Oracle's Project Jupiter shows that the AI power shortage is no longer a "2030 forecast." The mere possibility of a delayed power hookup has already triggered a force majeure clause, and it is starting to shake billions in loans and lease-income timelines.

Tech

Nvidia's Next Target After GPUs: Controlling What AI Agents Are Allowed to Do

OpenShell and Sentry are not about policing what an AI says. They are about controlling, at the server infrastructure level, which files and APIs an AI can touch, what it can execute, and who can actually pull the plug when something goes wrong.

Tech

NVDA

92 storiesSee all →

Amazon Goes After Nvidia's Strongest Moat, and It Is Software, Not GPUs

Amazon's open-source TorchNeuron aims to let existing AI code run on its Trainium chips. The contest comes down to the total cost of AI compute and the return on Amazon's $220 billion in annual capital spending.

Tech

AI's Next Bottleneck Is Money, Not Chips

Broadcom is lending Anthropic up to $42 billion, and Nvidia wants to build a $500 billion market for loans backed by GPUs. The AI race may turn on what rate buyers pay to borrow.

Tech

Two Companies Drive 34% of S&P 500 Earnings Growth as AI Pays Sellers First

Nvidia and Micron generate a third of expected earnings growth in US large caps. Apollo says the financial effect of AI is not yet visible in the S&P 493.

Investing

China's AI Labs Went Open Source Because They Had to, Not Because They Wanted To

A GPU shortfall pushed Chinese AI labs toward efficiency and open weights, and that constraint is now reshaping the global competition over who controls AI's basic infrastructure.

Tech

The US-China Summit Didn't Erase Taiwan Risk for Chip Stocks

Washington's Taiwan policy held, but roughly $14 billion in arms sales is still on hold. For AI chip investors, the summit reads less like risk removed and more like a fragile balance extended.

Macro

ASML Is Discussing 2030 Orders. How Long Can the AI Chip Supercycle Last?

Despite bubble worries, ASML sees equipment shortages through 2028. Investors should watch future production capacity, not just today's orders.

Tech

Tesla Energy's 13.7GWh Paradox: Expectations Ran Faster Than Deployments

Q2 deployments recovered but margins collapsed. Q3 set a record for deployments and still missed estimates. The issue is not the size of AI power demand but how fast it converts into Tesla revenue and profit.

Tech