Apple's $299 HomeView Is Unlikely to Move the Needle. The Services Math Might

Even 10 million units a year would add less than 1% to Apple's revenue. The real test is whether the smart display deepens iCloud+ and other recurring revenue.
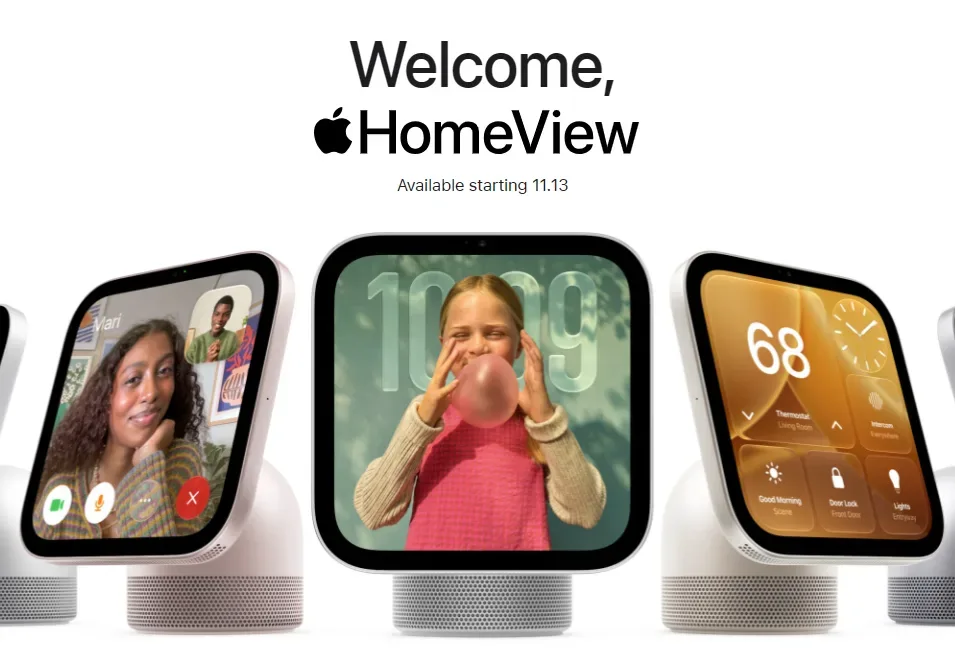
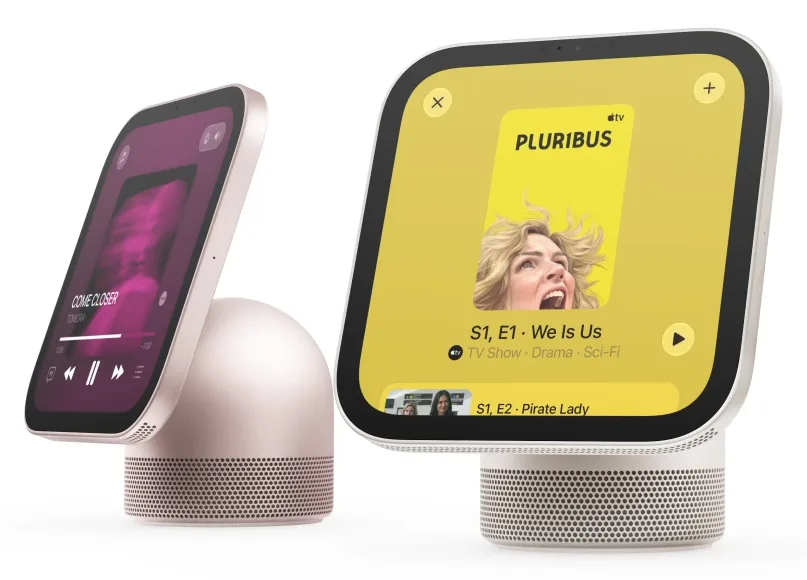
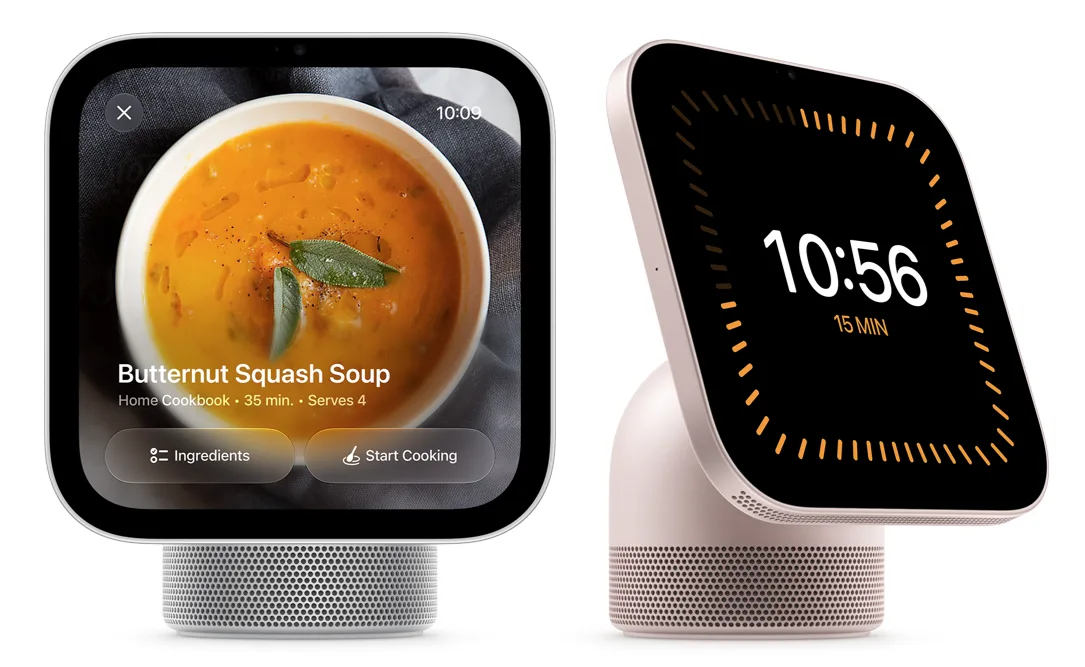
Apple unveiled HomeView on Oct. 13 at a price of $299. It is not a device you carry like an iPhone. It is a 7-inch smart display that sits in the home and is shared by the family.
The space Apple wants after the iPhone

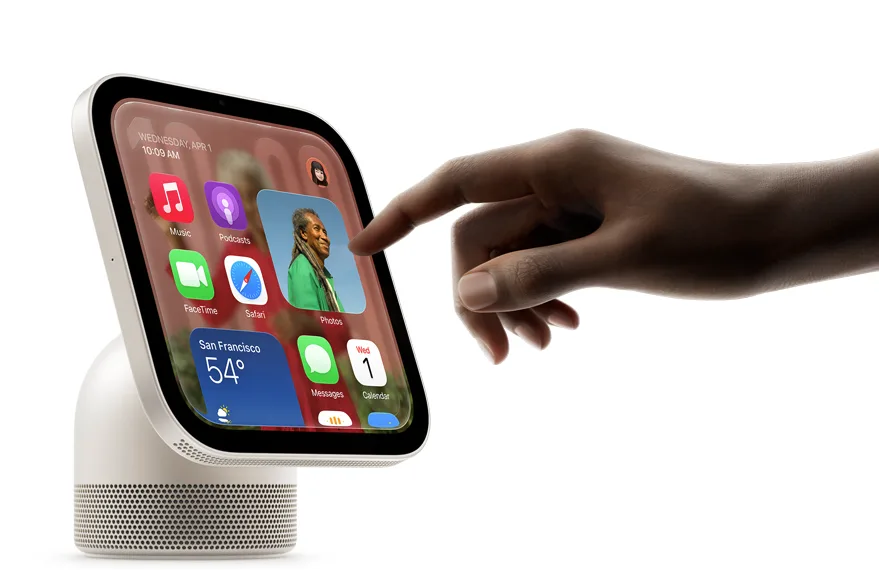
HomeView has a 7-inch Liquid Retina display, an A18 chip and a 12MP camera. It recognizes up to six family members by face and shows personalized messages, calendars and photos.

It handles FaceTime calls, music and appliance control. It can also show feeds from up to nine security cameras on one screen. With Matter and Thread support, it connects smart home devices from different makers.

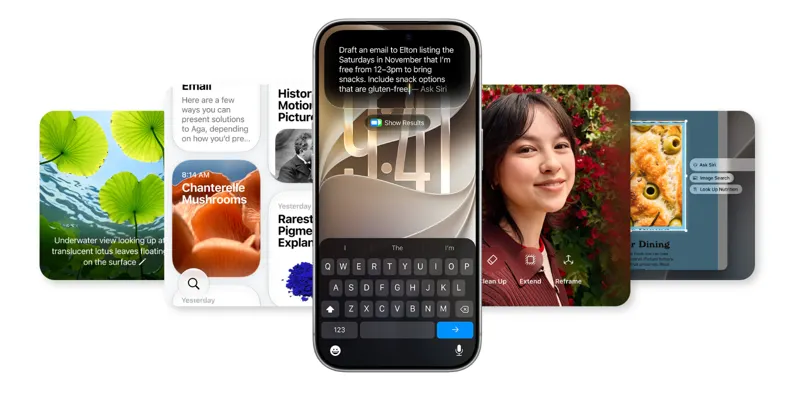
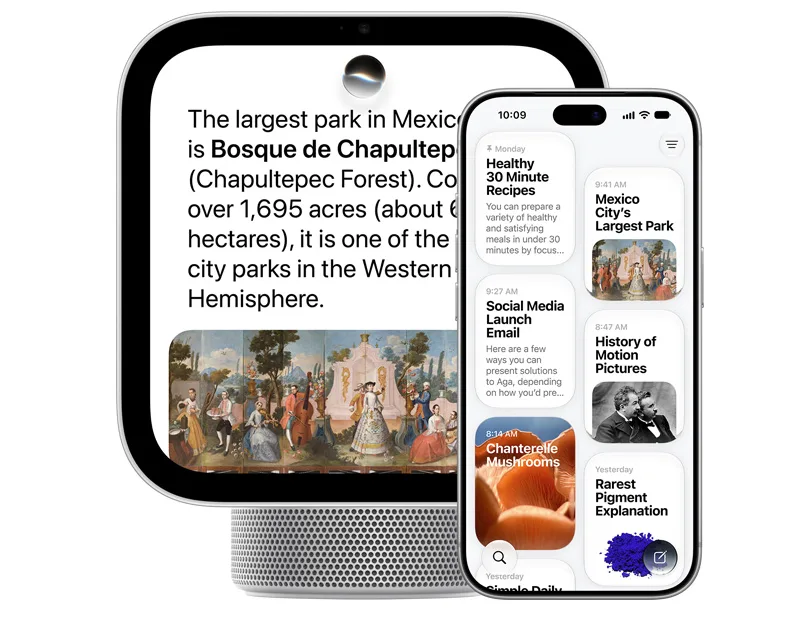
The biggest change is that Siri expands from a voice assistant that answers questions into an AI interface that understands household information and operates devices.

Still, the advanced features that draw on personal context stored on an iPhone or iPad require pairing with a device that supports Apple Intelligence. It is too early to call HomeView a finished home agent that carries out every task on its own.
Even 10 million units would be under 1% of Apple's revenue

Start with the math.

Apple's fiscal 2025 revenue was $416.161 billion. Of that, the Wearables, Home and Accessories segment brought in $35.686 billion, about 8.6% of the total.

The table below assumes every unit sells at $299. Actual reported revenue could differ with discounts, returns, sales channels and revenue recognition.

Annual unit salesAssumed revenueShare of Apple revenue
1 million$299 million0.072%
5 million$1.495 billion0.359%
10 million$2.99 billion0.718%

Assumes all units sell at $299. Benchmark is Apple's total fiscal 2025 revenue of $416.161 billion.

Ten million units a year is not a demand forecast. It is an assumption to show the scale involved. Even at that level, the effect on Apple's overall revenue growth rate would be limited.

Profit tells a similar story. In fiscal 2025, Apple's gross margin was 36.8% on products and 75.4% on services. HomeView's own margin has not been disclosed, so applying the product average to estimate actual profit would not be appropriate.
Apple is not after the profit on a single device

Alongside HomeView, Apple introduced the HomePod mini 2, a new Apple TV 4K and a line of smart home accessories with partners including LG Electronics and Schneider Electric.

Add locks, doorbells, security cameras and thermostats, and HomeView becomes a kind of control screen for the house. That changes the business model.

A household that wants smart security features has a reason to keep its iCloud+ subscription. Music and video services may also become easier to use. The connected experience built up between an iPhone and home devices raises the cost of switching to another ecosystem.

But more usage does not necessarily mean new subscription revenue. Existing subscribers may simply use the services more. That is why the numbers to watch are new paying subscribers and subscription retention, not HomeView itself.

Late to the party. What is different?

Amazon's Echo Show and Google's Nest Hub already offer screen-based smart home experiences. Apple is a latecomer, and HomeView's $299 price is high next to cheaper rivals.

Apple's pitch is an integration of per-family personalization, device-to-device connectivity, privacy and an AI-based voice interface.

Those strengths have to be proven in real homes. The Nov. 13 first-sale markets are limited to eight countries: the US, UK, Canada, Australia, New Zealand, India, Singapore and South Africa.

The European Union is excluded because of restrictions tied to Siri AI, and South Korea and Japan are not among the initial launch markets. Siri AI language support at launch is also centered on English. Global potential is one thing. The market Apple can actually sell into today is another.

Apple is not selling a small screen. It is selling a new touchpoint meant to keep iPhone users living around Apple's AI at home as well.

Whether HomeView is a successful product can be judged by unit sales. Whether it is a successful investment story depends on how much more recurring revenue and profit it generates for Apple.

HomeView matters to Apple's story only if it adds recurring services revenue, since hardware sales alone would barely register.

Insight Times Editorial Desk

More by topic

Starting with this story's topics, then what readers are following now

Investor psychology, decision-making and books on investing

AAPL

This story's topic11 storiesSee all →

Apple's Real AI Bet Isn't a Chatbot. It's Siri Running Your Apps

Apple has stepped back from the race to build a smarter chatbot than ChatGPT. Instead it is building an "OS agent" that connects Mail, Photos, Calendar and hundreds of thousands of apps to actually finish tasks. 2026 is the first year that strategy gets tested as a product, not a keynote promise.

Tech

Brent at $109, the 10-year at 4.94%: the discount rate is beating the AI trade

Stocks fell for a fourth straight session on Sept. 10 as producer prices and energy costs pushed long yields toward 5%. After the close, Oracle showed AI demand is converting into signed contracts. The question is no longer demand. It is what multiple the market can pay for it.

Tech

Apple's first foldable barely moved the stock. Margin, not the $1,999 price, is why

The iPhone Duo is a real break in Apple's product strategy. For investors, the question is not how many it sells, but whether the price increase survives memory and foldable component costs and reaches EPS.

Investing

AI's Next KPI Isn't Token Price. It's Cost Per Successful Task

Apple is cutting the cost of where inference happens, Anthropic is cutting the cost of running its models, and Snorkel AI shows money flowing into the data and evaluation layer that reduces failed attempts. All three point to one shift: AI competition is moving from bigger models to cheaper successful outcomes.

Tech

AI Was Supposed to Live in the Cloud. Apple Is Bringing It Back to the Desktop.

Four Mac Studios running a trillion-parameter model matters less than the economics behind it: heavy, repeated AI use can make owning compute cheaper than renting it by the token.

Tech

Why the iPhone Fold's Crease Barely Shows in the Middle

Apple's foldable engineering makes sense once you think about bookshelves, matte wallpaper, and window screens. Apple didn't erase the crease. It tricked force, light, and the camera into hiding it.

Tech

Higher Rates Don't Break Big Tech's Business. They Reprice Its Future.

Microsoft, Alphabet, Apple and Nvidia are sitting on more cash than debt. What rates actually change is the discount rate applied to cash flows a decade out, and whether a cut is a soft landing or a recession signal.

Tech

A building that houses servers and networking gear and supplies them with powe…

US AI Data Centers Are Headed for 90GW. Gigawatts Now Matter More Than Dollars

Goldman Sachs expects US data center capacity to grow from 64GW at the end of 2026 to 90GW at the end of 2027. The AI race is moving from buying GPUs to building power plants and transmission lines alongside them.

Tech

Tesla Energy's 13.7GWh Paradox: Expectations Ran Faster Than Deployments

Q2 deployments recovered but margins collapsed. Q3 set a record for deployments and still missed estimates. The issue is not the size of AI power demand but how fast it converts into Tesla revenue and profit.

Tech

Why the White House Swapped "AI" for "Super Intelligence"

Executive Order 14434 renames AI across the federal government without defining a new technology. The real story is about roughly $700 billion in capex, free cash flow and electricity.

Tech

Why Nvidia Is Happy to Help Make AI Models Nearly Free

Falling model prices can squeeze model makers. For Nvidia, the number that matters is the total volume of tokens generated worldwide and the compute that produces them.

Tech

Nvidia Put $2 Billion Into Lumentum. Optics May Be the Next Bottleneck, but the Stock Has Already Run

Optical networking is emerging as the next constraint on AI data centers. Investors need to separate the industry's growth potential from the price they are already paying for it.

Tech

Nvidia's Next Target After GPUs: Controlling What AI Agents Are Allowed to Do

OpenShell and Sentry are not about policing what an AI says. They are about controlling, at the server infrastructure level, which files and APIs an AI can touch, what it can execute, and who can actually pull the plug when something goes wrong.

Tech

AI Needs to Find $1 Trillion a Year From Somewhere to Pay Back Its Capex

Saying AI capex is big is no longer the point. The harder question is what end users have to pay for the buildout to pencil out, and Goldman Sachs puts that number at roughly $1 trillion a year.

Tech

HBM

63 storiesSee all →

Memory stacked next to the GPU.

Has Memory Peaked? Prices Are Cooling, but the Shortage Looks Set to Run to 2028

Price growth has slowed and consumer demand is already breaking. Server and HBM supply remains short, and Micron says more than 75% of its 2027 volume is already committed to customers.

Tech

AI Chip Peak Check: Demand Still Rising, Risk Building in 2027-2029 Supply and Funding

DRAM and NAND contract prices are still climbing and HBM suppliers hold the edge. Power shortages, AI financing costs and simultaneous memory expansion are the risks for later years.

Investing

How Far Can China Push DRAM Without EUV

CXMT says it has shrunk DRAM features to 11.95nm using quadruple patterning instead of EUV lithography. The real question is not whether China caught up, but how much more it now costs China to get there.

Tech

Memory Chip Supercycle: Not at Peak Yet, But 5 of 6 Warning Signs Are Flashing

Memory prices are still climbing, but the pace is slowing and PC and smartphone demand is starting to crack under the weight of higher chip costs. This looks less like a price peak and more like a profit plateau building toward the next supply cycle.

Investing

The Real ASML Number Isn't the 3% Pop, It's the 30% Capacity Hike

ASML's rally isn't just an AI trade. Customers are already locking in 2027 tool slots, and ASML is raising Low-NA EUV capacity by roughly 30% to keep up.

Investing

2027 Isn't the End: Citi's Case for a Memory Supercycle Running to 2031

Citi says the memory shortage timeline is stretching again. If AI shifts from "train once" models to continual learning, HBM, server DRAM and enterprise SSDs could all fall short at the same time.

Tech

Samsung, SK Hynix Sold Off on AI Fears. The Orders Haven't Followed Yet

The selloff reflects a market recalculating AI capex speed and memory earnings expectations, not confirmed cancellations. So far, the data show a gap between fear and reality.

Investing

NVDA

75 storiesSee all →

The US-China Summit Didn't Erase Taiwan Risk for Chip Stocks

Washington's Taiwan policy held, but roughly $14 billion in arms sales is still on hold. For AI chip investors, the summit reads less like risk removed and more like a fragile balance extended.

Macro

Nvidia's $500 Billion Experiment: Wall Street Asks Who Backs the GPU, Not Just the Chip

The real issue in Nvidia's financing platform is not chip sales. It is how far Wall Street will trust GPU resale prices and rental income three to four years out.

Tech

The AI Bubble Question Has Changed: By Late 2026, It's ROIC Over GPUs

There is no sign yet that AI investment is slowing. If anything, hyperscaler spending forecasts keep climbing. But as the scale of that capital has grown, the market's question has shifted from "is AI growing" to "when, and how much, does this capital come back as cash."

Tech

2027 Investing Needs Alignment, Not Prediction

A new investing book argues the hard part was never picking the next winner. It's staying aligned with where value and bottlenecks are moving while keeping old human weaknesses in check.

Investor Mind

What Jensen Huang sold at the G20 was not GPUs. It was national infrastructure

Nvidia's message is that AI should be laid down like electricity, roads and the internet. After the hyperscalers, the buyers are governments, telcos, regional clouds and industrial data centers.

Tech

ASML Is Discussing 2030 Orders. How Long Can the AI Chip Supercycle Last?

Despite bubble worries, ASML sees equipment shortages through 2028. Investors should watch future production capacity, not just today's orders.

Tech

Nvidia and AMD Back Common Design to Build AI Data Centers Like Lego Blocks

A new Open Compute Project spec aims to let one building host rival chip systems. Whether it speeds up construction is not yet confirmed.

Tech