Lam Research Revenue Jumped 54%. The Stock Fell 12%. Here Is Why

Record results and a sharp sell-off at Lam Research show a paradox of growth investing. The key question is not how fast a company grows, but how much investors paid for that growth.
The numbers were close to perfect

Lam Research, the US semiconductor equipment maker, reported results on Oct. 21 that looked strong by almost any measure.

Revenue for the quarter ended Sept. 27, 2026, was $821.942 million...

Correction, stated plainly: revenue was $8,219.42 million, or about $8.22 billion. That was up 54.4% from a year earlier and 22.3% from the prior quarter.

GAAP gross margin was 52.3% and GAAP operating margin was 40.0%. Of every $100 in revenue, the company kept $40 as operating profit. That is a very high level of profitability for a chip equipment company.

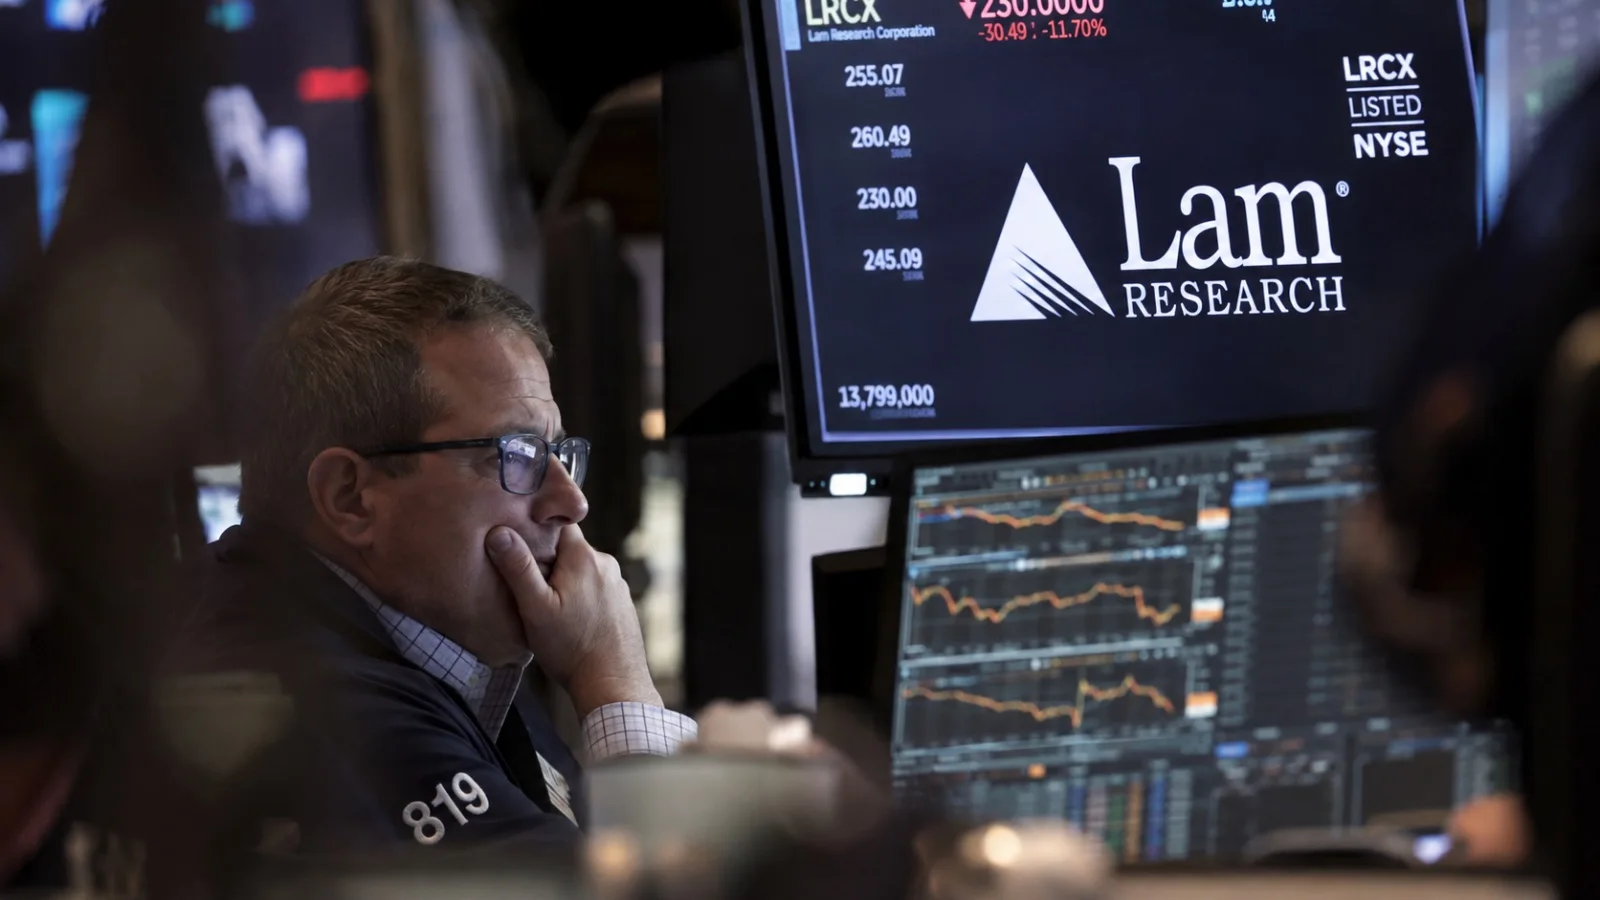
Yet on Oct. 22 the stock fell from $260.81 to $230.15. The one-day decline was 11.76%.

Lam Research: results vs. stock reaction

ItemFigure
Quarterly revenue growth, YoY+54.4% ($8.22 billion)
Stock move on Oct. 22-11.76% (close at $230.15)
GAAP gross margin52.3%
GAAP operating margin40.0%
GAAP diluted EPS$2.19
Non-GAAP diluted EPS$2.20
Next-quarter revenue guidance$8.6 billion, plus or minus $400 million

Fiscal 2027 first-quarter results. Source: Lam Research.

The market was disappointed by the future, not the past

The key is the gap between expectations and results.

Consensus called for revenue of about $8.14 billion and non-GAAP EPS of $2.18. Actual results beat both, but the EPS beat was only about 0.9%.

Next-quarter revenue guidance of $8.6 billion was almost identical to the consensus of $8.57 billion. Management also said that guidance would have been higher without supply chain constraints. It expects China's share of revenue to fall considerably next quarter.

China accounted for 35% of September-quarter revenue, above Korea at 20% and Taiwan at 18%. These figures are by customer location, not by where chips are ultimately consumed.

A broader worry about the scale and returns of AI spending added to the pressure. The Philadelphia Semiconductor Index fell about 6.7% the same day. The problem was not Lam's alone.

Strong chip sales do not guarantee strong equipment sales

Lam sells the tools that make chips, such as etch and deposition equipment, not the chips themselves.

That distinction matters.

When demand for AI chips rises, manufacturers such as Samsung, SK hynix and TSMC may buy equipment to expand capacity. But if they already have enough capacity, chip sales can grow while new equipment orders shrink.

An equipment maker's revenue therefore depends less on current chip sales than on customers' future capital spending plans.

Lam gave a preliminary forecast that global wafer fab equipment (WFE) spending will exceed $200 billion in 2027, up sharply from the mid-$150 billion range in 2026. This is the company's outlook, not confirmed customer orders.

What happens when you buy a good company at a high price?

A stock price reflects more than current earnings. It also reflects how much investors are willing to pay for future profit.

Suppose a company earns $10 per share and you buy at 40 times earnings, or $400.

A year later, EPS grows 50% to $15. But if the market's multiple falls to 25 times, the stock is worth $375.

StartOne year later
Price$400 (EPS $10 x 40)$375 (EPS $15 x 25)

EPS growth is +50%. The stock return is -6.25%.

Hypothetical case, excluding dividends and trading costs. It does not describe Lam Research's actual P/E change.

Earnings growth and changes in the valuation multiple can move in opposite directions.

Four things to watch

  1. Whether Lam meets its quarterly guidance. If supply chain bottlenecks ease, revenue could come in above the current outlook.
  2. China's share of revenue and absolute revenue. It matters whether a falling share reflects growth elsewhere or a shrinking China business.
  3. Global WFE spending. Watch whether the company's forecast of more than $200 billion in 2027 turns into actual customer investment.
  4. Operating margin and valuation. Check whether the 40% operating margin holds, and what P/E the stock carries relative to future EPS growth.

Owning a good company is one thing. Investing at a good price is another. Lam Research's latest results put numbers on that difference.

Good results can still send a stock lower when market expectations were already high, and Lam Research is the example.

Insight Times Editorial Desk

More by topic

Starting with this story's topics, then what readers are following now

Investor psychology, decision-making and books on investing

Valuation

This story's topic25 storiesSee all →

Measuring where a share price sits relative to the company’s results.

Nvidia Put $2 Billion Into Lumentum. Optics May Be the Next Bottleneck, but the Stock Has Already Run

Optical networking is emerging as the next constraint on AI data centers. Investors need to separate the industry's growth potential from the price they are already paying for it.

Tech

AI Needs to Find $1 Trillion a Year From Somewhere to Pay Back Its Capex

Saying AI capex is big is no longer the point. The harder question is what end users have to pay for the buildout to pencil out, and Goldman Sachs puts that number at roughly $1 trillion a year.

Tech

AI Can Lift More Than Stocks: It May Push Long-Term Yields Higher Too

The AI boom can grow the numerator of corporate earnings while also growing the denominator of the discount rate. Investors watching long-term Treasury yields now need to add "AI capital demand" to the Fed, inflation and the deficit.

Tech

Anthropic's IPO: The Number That Matters More Than $100 Billion Is $2 Trillion

Claude-maker Anthropic is growing at a stunning pace, but the real question for investors is not how fast, only how long, and how much cash is left after GPUs and data centers.

Tech

2027 Investing Needs Alignment, Not Prediction

A new investing book argues the hard part was never picking the next winner. It's staying aligned with where value and bottlenecks are moving while keeping old human weaknesses in check.

Investor Mind

AMD Crossed $1 Trillion, and the Market Started Looking at CPUs Again

AMD's stock topped a $1 trillion market cap for the first time. The rally isn't just about being an Nvidia alternative. It reflects a reassessment of AMD as a full-stack AI infrastructure vendor, one that bundles CPUs, GPUs and networking, as AI shifts from chatbots to agents and reignites data center demand for CPUs.</deck> <parameter name="oneline">As AI moves from chatbots to agents, the market has started counting the CPU sitting next to the GPU again.

Tech

Apple's first foldable barely moved the stock. Margin, not the $1,999 price, is why

The iPhone Duo is a real break in Apple's product strategy. For investors, the question is not how many it sells, but whether the price increase survives memory and foldable component costs and reaches EPS.

Investing

A building that houses servers and networking gear and supplies them with powe…

US AI Data Centers Are Headed for 90GW. Gigawatts Now Matter More Than Dollars

Goldman Sachs expects US data center capacity to grow from 64GW at the end of 2026 to 90GW at the end of 2027. The AI race is moving from buying GPUs to building power plants and transmission lines alongside them.

Tech

Tesla Energy's 13.7GWh Paradox: Expectations Ran Faster Than Deployments

Q2 deployments recovered but margins collapsed. Q3 set a record for deployments and still missed estimates. The issue is not the size of AI power demand but how fast it converts into Tesla revenue and profit.

Tech

Why the White House Swapped "AI" for "Super Intelligence"

Executive Order 14434 renames AI across the federal government without defining a new technology. The real story is about roughly $700 billion in capex, free cash flow and electricity.

Tech

Why Nvidia Is Happy to Help Make AI Models Nearly Free

Falling model prices can squeeze model makers. For Nvidia, the number that matters is the total volume of tokens generated worldwide and the compute that produces them.

Tech

Nvidia's Next Target After GPUs: Controlling What AI Agents Are Allowed to Do

OpenShell and Sentry are not about policing what an AI says. They are about controlling, at the server infrastructure level, which files and APIs an AI can touch, what it can execute, and who can actually pull the plug when something goes wrong.

Tech

Nvidia's $500 Billion Experiment: Wall Street Asks Who Backs the GPU, Not Just the Chip

The real issue in Nvidia's financing platform is not chip sales. It is how far Wall Street will trust GPU resale prices and rental income three to four years out.

Tech

The AI Bubble Question Has Changed: By Late 2026, It's ROIC Over GPUs

There is no sign yet that AI investment is slowing. If anything, hyperscaler spending forecasts keep climbing. But as the scale of that capital has grown, the market's question has shifted from "is AI growing" to "when, and how much, does this capital come back as cash."

Tech

HBM

63 storiesSee all →

Memory stacked next to the GPU.

Has Memory Peaked? Prices Are Cooling, but the Shortage Looks Set to Run to 2028

Price growth has slowed and consumer demand is already breaking. Server and HBM supply remains short, and Micron says more than 75% of its 2027 volume is already committed to customers.

Tech

AI Chip Peak Check: Demand Still Rising, Risk Building in 2027-2029 Supply and Funding
DRAM and NAND contract prices are still climbing and HBM suppliers hold the edge. Power shortages, AI financing costs and simultaneous memory expansion are the risks for later years.

Investing

How Far Can China Push DRAM Without EUV

CXMT says it has shrunk DRAM features to 11.95nm using quadruple patterning instead of EUV lithography. The real question is not whether China caught up, but how much more it now costs China to get there.

Tech

Memory Chip Supercycle: Not at Peak Yet, But 5 of 6 Warning Signs Are Flashing

Memory prices are still climbing, but the pace is slowing and PC and smartphone demand is starting to crack under the weight of higher chip costs. This looks less like a price peak and more like a profit plateau building toward the next supply cycle.

Investing

The Real ASML Number Isn't the 3% Pop, It's the 30% Capacity Hike

ASML's rally isn't just an AI trade. Customers are already locking in 2027 tool slots, and ASML is raising Low-NA EUV capacity by roughly 30% to keep up.

Investing

2027 Isn't the End: Citi's Case for a Memory Supercycle Running to 2031

Citi says the memory shortage timeline is stretching again. If AI shifts from "train once" models to continual learning, HBM, server DRAM and enterprise SSDs could all fall short at the same time.

Tech

Samsung, SK Hynix Sold Off on AI Fears. The Orders Haven't Followed Yet

The selloff reflects a market recalculating AI capex speed and memory earnings expectations, not confirmed cancellations. So far, the data show a gap between fear and reality.

Investing

NVDA

75 storiesSee all →

The US-China Summit Didn't Erase Taiwan Risk for Chip Stocks

Washington's Taiwan policy held, but roughly $14 billion in arms sales is still on hold. For AI chip investors, the summit reads less like risk removed and more like a fragile balance extended.

Macro

What Jensen Huang sold at the G20 was not GPUs. It was national infrastructure

Nvidia's message is that AI should be laid down like electricity, roads and the internet. After the hyperscalers, the buyers are governments, telcos, regional clouds and industrial data centers.

Tech

ASML Is Discussing 2030 Orders. How Long Can the AI Chip Supercycle Last?

Despite bubble worries, ASML sees equipment shortages through 2028. Investors should watch future production capacity, not just today's orders.

Tech

Nvidia and AMD Back Common Design to Build AI Data Centers Like Lego Blocks

A new Open Compute Project spec aims to let one building host rival chip systems. Whether it speeds up construction is not yet confirmed.

Tech

AI Data Centers in Space? The Real Test Launches This Week

On October 1, a SpaceX rocket carries a sub-50kg satellite with a Nvidia Orin NX chip and Google TPU test hardware into orbit. It is too early to call this a "space data center," but the signal is clear: the AI industry is rethinking where computing should physically sit.

Tech

Samsung's HBM4 Yield Hits 80% - Now the Real Fight Is Production Volume

Reports confirm Samsung's HBM4 yield has climbed to roughly 80 percent, but the bigger number is capacity: HBM wafer input is projected to jump nearly 40 percent next year, from about 180,000 to 250,000 wafers a month.

Tech

The Question Markets Asked This Week: Who Controls the AI Bottleneck, Not Who Owns AI

The Fed hiked again and the 10-year topped 5 percent, but the center of the AI trade held. The market is no longer asking whether AI is growing, it is asking who controls memory, power and capital.

Tech