Musk's Terafab: What a $119 Billion Chip Plant Is Really For

From Tesla's robots to SpaceX's orbital data centers, Musk wants to control chip production itself. The open question is whether he can make advanced chips at high yield.
1. Terafab's real purpose is not selling chips

Elon Musk is probably not trying to enter the chip market and compete head-on with TSMC.

Tesla needs AI chips for its self-driving vehicles and Optimus robots. SpaceX needs dedicated compute chips that can run in space. As AI models advance and production volumes rise, reliance on outside chipmakers could become a long-term constraint.

That is the economic logic behind Terafab.

The question is less how much profit the chips themselves earn than how much loss Tesla avoids when a chip shortage keeps it from building cars and robots on time.

Making chips in-house is not always cheaper, though. Advanced foundries demand huge upfront investment, high fixed costs and the burden of stabilizing yields. Without enough volume, costs could end up higher than with contract manufacturing.

2. The $119 billion: what is actually under way

  • Long-term planned investment assets: $119.39 billion (about $119.4 billion)
  • Planned investment phases: 4, an expansion concept laid out in the filings

Figure combines school-district JETI filings tied to Grimes County. It does not represent actual spending or a confirmed final budget.

Terafab splits into two roles.

The Austin research fab would validate new chip processes and shorten the development cycle from design to testing. On an earnings call, Musk described a plan in which Tesla runs the research facility and SpaceX leads the initial buildout of the large-scale production site.

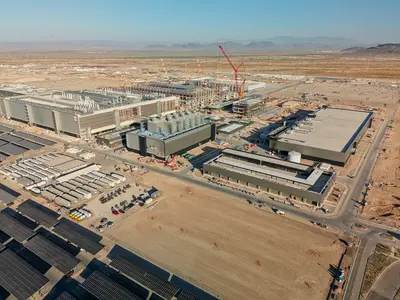
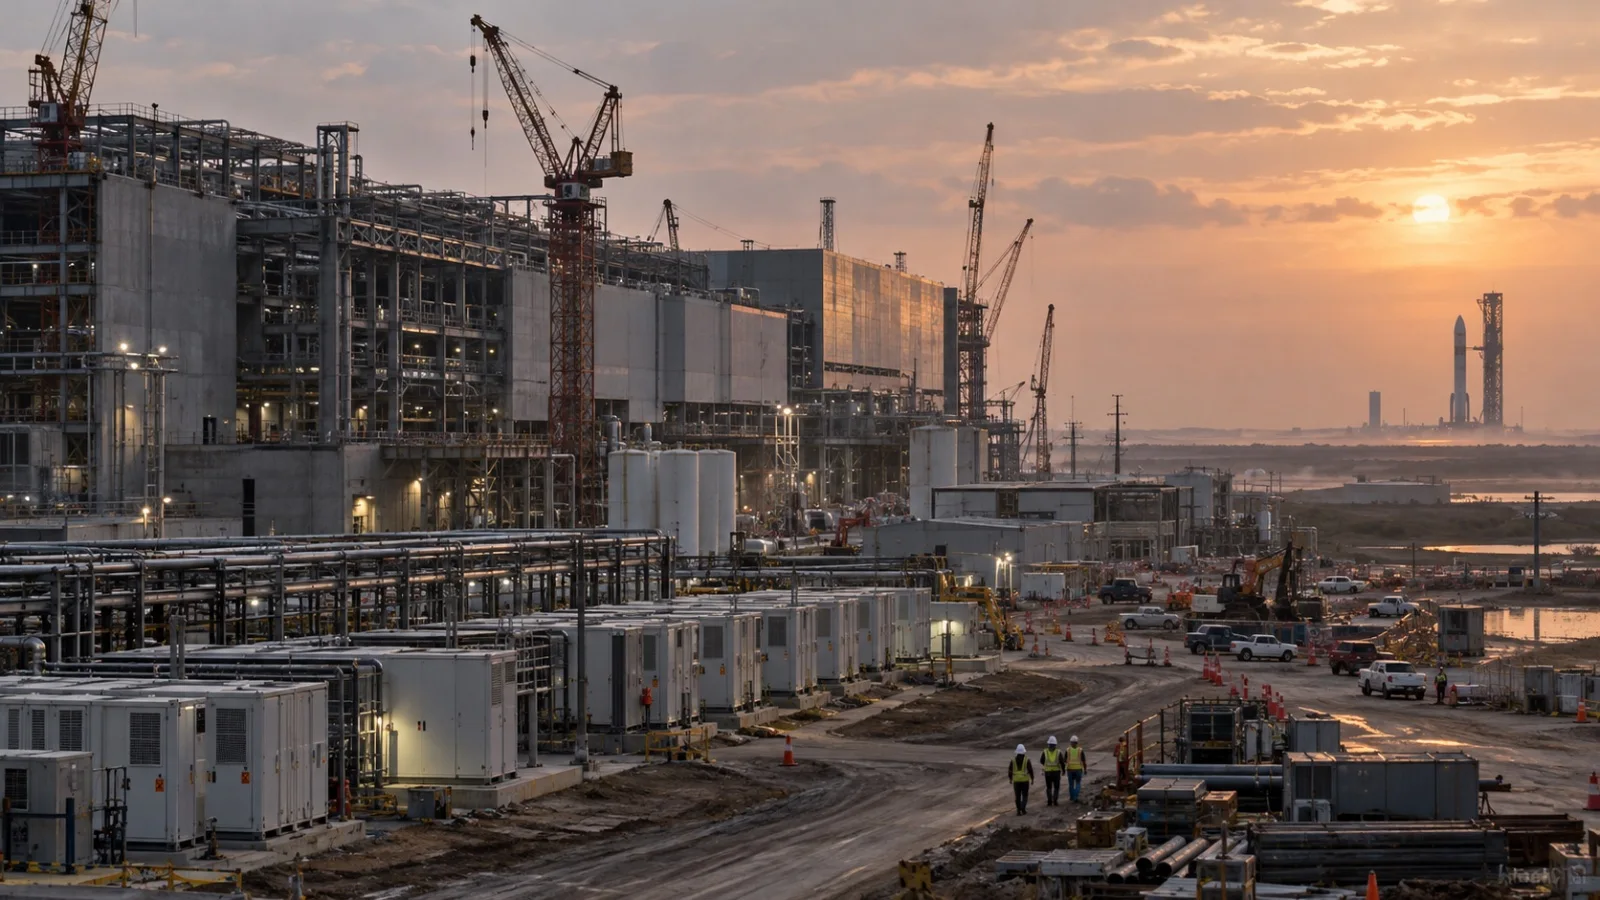
The Grimes County production site is an investment project for large-scale manufacturing. It aims to use the power, water and industrial land around the Gibbons Creek power plant site, and local tax-incentive procedures have moved forward. Still, the size of the filing should not be read as secured funding or as capacity that will be built.

3. Why Intel and equipment suppliers matter

Building a chip plant is nothing like putting up a building.

Thousands of process conditions must be stabilized, defect rates lowered, and chips of the same quality produced again and again. That takes process know-how built up over decades.

This is why Musk has described plans to use Intel's 14A process. Even with its own fab, a company need not develop every manufacturing technology from scratch. Leaning on Intel's technology and the existing equipment industry could cut some development risk.

But 14A itself still needs validation and production stabilization. A technology partnership does not guarantee Terafab's success.

Reports also point to South Korean equipment and materials suppliers getting involved, including HPSP (high-pressure hydrogen annealing test equipment), Hanmi Semiconductor (advanced packaging equipment) and several materials, piping and gas-handling firms. Reports of firm orders need to be separated from companies still in talks or at the NDA stage. Linking deals with undisclosed order values and delivery dates to a big jump in earnings is premature.

4. Robots for Tesla, space computing for SpaceX

For Tesla, the key metrics are performance per watt and cost per finished product, more than peak compute. A saving of a few dozen dollars per robot becomes meaningful money if output grows to millions of units.

SpaceX has a longer-term idea: combining launch vehicles, satellite communications and its own compute chips to build orbital data centers.

Putting data centers in space does not by itself make them economical. Even if an orbit with favorable solar conditions can be chosen, constraints remain: Earth's shadow, radiation, waste-heat rejection and satellite replacement costs.

The view that space computing will become cheaper than ground-based data centers is a hypothesis that needs testing, not a proven business result.

  • Tesla: low-power AI inference chips tailored to self-driving vehicles, Cybercab and Optimus
  • SpaceX: AI compute chips for space, designed for radiation tolerance and power efficiency

5. A Tesla-SpaceX merger cuts both ways for investors

On SpaceX's Oct. 20 earnings call, Musk said independent directors of both companies have formed a special committee to examine a possible merger. Terms have not been agreed, and whether a deal happens is undecided.

If a merger happened, Terafab's cost sharing, ownership of chip design assets and allocation of production capacity could be coordinated within one corporate structure.

On the other hand, Tesla shareholders could end up sharing the heavy investment burden of the space infrastructure business. New share issuance, the exchange ratio and the valuation would all change existing shareholders' economic stake.

So the merger announcement itself matters less than what Tesla shareholders would gain, and what new costs and risks they would take on.

The bottom line

The most important thing about Terafab is not the $119 billion figure. It is whether, after pouring in that much capital, Musk can actually produce the chips he wants faster and more efficiently than outside foundries.

Musk has succeeded before in changing how established industries make things. But in semiconductors, building a new plant quickly and producing leading-edge chips at high yield are separate challenges.

Terafab's future will be proven not by the grand factory plan but by the first small test chips made inside it.

Terafab looks less like a chip business and more like a way to secure chips for Tesla and SpaceX, and its fate will turn on the yield of its first test chips.

Insight Times Editorial Desk

More by topic

Starting with this story's topics, then what readers are following now

Investor psychology, decision-making and books on investing

Semiconductors

This story's topic48 storiesSee all →

The whole business of designing, fabricating and testing chips.

Memory Chip Supercycle: Not at Peak Yet, But 5 of 6 Warning Signs Are Flashing

Memory prices are still climbing, but the pace is slowing and PC and smartphone demand is starting to crack under the weight of higher chip costs. This looks less like a price peak and more like a profit plateau building toward the next supply cycle.

Investing

The US-China Summit Didn't Erase Taiwan Risk for Chip Stocks

Washington's Taiwan policy held, but roughly $14 billion in arms sales is still on hold. For AI chip investors, the summit reads less like risk removed and more like a fragile balance extended.

Macro

The Real ASML Number Isn't the 3% Pop, It's the 30% Capacity Hike

ASML's rally isn't just an AI trade. Customers are already locking in 2027 tool slots, and ASML is raising Low-NA EUV capacity by roughly 30% to keep up.

Investing

Stocks Bounce, but the AI Selloff May Not Be Over: A Two-Week Playbook

The Dow rose more than 1% while the Nasdaq barely moved and semiconductors kept falling. A W-shaped retest looks more likely than a V, and the task now is surviving the next drop.

Investing

ASML Is Discussing 2030 Orders. How Long Can the AI Chip Supercycle Last?

Despite bubble worries, ASML sees equipment shortages through 2028. Investors should watch future production capacity, not just today's orders.

Tech

Samsung Posts 107 Trillion Won Profit, TSMC Sales Jump 50%. Why Did the Shares Fall?

The AI chip supercycle has not ended. But the market's question has changed: not how fast earnings grow, but how long today's enormous margins can last.

Tech

White House Swaps AI for "SI." The Real Investment Signal Is Infrastructure, Not the Name

An executive order renames artificial intelligence "Super Intelligence" and six frontier labs sign a voluntary safety accord. What investors should watch is the data center, power, nuclear and chip policy now gathered under one national-competitiveness frame.

Tech

TSLA

This story's topic34 storiesSee all →

The Cybercab is not a $30,000 car. Tesla is selling hours, not vehicles

No steering wheel, no pedals. The economics of Tesla's robotaxi turn on how many paid hours a day it runs, not on what it costs to build.

Tech

Tesla Energy's 13.7GWh Paradox: Expectations Ran Faster Than Deployments

Q2 deployments recovered but margins collapsed. Q3 set a record for deployments and still missed estimates. The issue is not the size of AI power demand but how fast it converts into Tesla revenue and profit.

Tech

Tesla's FSD Clears Eight European Countries. The Number That Matters Now Is Paid Conversion

European regulatory barriers for FSD Supervised are falling. But investors who lump supervised software revenue together with the value of driverless robotaxis risk pricing the same news twice.

Tech

Why Tesla Lined Up $30 Billion in Credit It Says It Won't Use This Year

Tesla's 2026 capex is set to nearly triple. The question is less about debt than about when spending on AI, robotaxis, chips and energy turns into cash flow.

Tech

The AI Bubble Question Has Changed: By Late 2026, It's ROIC Over GPUs

There is no sign yet that AI investment is slowing. If anything, hyperscaler spending forecasts keep climbing. But as the scale of that capital has grown, the market's question has shifted from "is AI growing" to "when, and how much, does this capital come back as cash."

Tech

Why Elon Musk's 4% Growth Call Deserves a Serious Read

Elon Musk says AI could double US GDP growth next year from roughly 2% to 4%. The number that matters isn't 4%, it's the idea that intelligence is turning from scarce labor into replicable capital.

Macro

The Number That Matters More Than 0.81 Seconds: 2028 and Tesla's Roadster

The second-generation Roadster has flown, using SpaceX-derived thrusters. For investors, the better question is not whether it can fly but what it can change in Tesla's value.

Tech

Semiconductor Foundry

This story's topic5 storiesSee all →

A building that houses servers and networking gear and supplies them with powe…

US AI Data Centers Are Headed for 90GW. Gigawatts Now Matter More Than Dollars

Goldman Sachs expects US data center capacity to grow from 64GW at the end of 2026 to 90GW at the end of 2027. The AI race is moving from buying GPUs to building power plants and transmission lines alongside them.

Tech

Why the White House Swapped "AI" for "Super Intelligence"

Executive Order 14434 renames AI across the federal government without defining a new technology. The real story is about roughly $700 billion in capex, free cash flow and electricity.

Tech

Why Nvidia Is Happy to Help Make AI Models Nearly Free

Falling model prices can squeeze model makers. For Nvidia, the number that matters is the total volume of tokens generated worldwide and the compute that produces them.

Tech

Nvidia Put $2 Billion Into Lumentum. Optics May Be the Next Bottleneck, but the Stock Has Already Run

Optical networking is emerging as the next constraint on AI data centers. Investors need to separate the industry's growth potential from the price they are already paying for it.

Tech

Nvidia's Next Target After GPUs: Controlling What AI Agents Are Allowed to Do

OpenShell and Sentry are not about policing what an AI says. They are about controlling, at the server infrastructure level, which files and APIs an AI can touch, what it can execute, and who can actually pull the plug when something goes wrong.

Tech

AI Needs to Find $1 Trillion a Year From Somewhere to Pay Back Its Capex

Saying AI capex is big is no longer the point. The harder question is what end users have to pay for the buildout to pencil out, and Goldman Sachs puts that number at roughly $1 trillion a year.

Tech

Nvidia's $500 Billion Experiment: Wall Street Asks Who Backs the GPU, Not Just the Chip

The real issue in Nvidia's financing platform is not chip sales. It is how far Wall Street will trust GPU resale prices and rental income three to four years out.

Tech