Tesla's Paradox: Profit Halved, Yet Cash Came In Positive
Tesla posted $1.53 billion in free cash flow against an expected $4.92 billion outflow. What matters is less the cash itself than how fast Tesla invests in AI and what that capital eventually earns.
1. How the $6.451 billion gap between forecast and actual came about
Tesla's third-quarter revenue was $28.046 billion. That beat the market forecast of about $27.88 billion but was nearly flat against $28.095 billion a year earlier. Operating income fell from $1.624 billion to $718 million.
Free cash flow (FCF), by contrast, was a surplus of $1.531 billion. Reuters reported the market expected a deficit of about $4.92 billion. The gap is about $6.451 billion. Not all of it can be read as improved business strength.
| Metric | Figure |
|---|---|
| Operating cash flow | $6.263B |
| Capital expenditure | $4.732B |
| Free cash flow | +$1.531B |
| Market FCF forecast | -$4.92B (Reuters-cited consensus) |
Actual capex came in about $2.77 billion below the market forecast of about $7.5 billion. Hold operating cash flow constant and substitute the forecast capex, and FCF turns into a deficit of about $1.24 billion. That is a simple sensitivity calculation, not a reconstruction of the exact components of the consensus FCF.
The cash flow statement also reflects inflows of about $3.991 billion from changes in accounts payable, accrued expenses and other liabilities, and about $1.255 billion from changes in deferred revenue. Both added to this quarter's cash flow. Neither can be assumed to repeat at the same size every quarter.
2. The auto recovery showed up before revenue growth
Deliveries were 486,532 vehicles, above the market forecast of about 461,100. They were still about 2% below a year earlier, and automotive revenue fell 3% year over year. A rebound in volume alone does not confirm top-line growth.
The positive change is that automotive gross margin excluding regulatory credits improved to 18.1% from 16.3% in the prior quarter. Total gross profit rose about $440 million from a year earlier. But operating expenses rose about $1.346 billion, so operating income fell.
| Key metric | Q3 2025 | Q3 2026 |
|---|---|---|
| Revenue | $28.095B | $28.046B |
| Gross profit | $5.054B | $5.494B |
| Operating expenses | $3.430B | $4.776B |
| Operating income | $1.624B | $718M |
| Operating margin | 5.8% | 2.6% |
R&D expense rose sharply to $2.761 billion. It is fair to see that as investment in future businesses. But the $1.165 billion in stock-based compensation is a real economic cost too. Shareholders should look not only at adjusted earnings but at per-share cash flow after dilution.
3. FSD already shows customers will pay
Paid Full Self-Driving (FSD) customers worldwide reached 1.74 million, up 260,000 from the prior quarter. The FSD take rate on new North American deliveries also exceeded 75%. That suggests AI features can help sell cars and also become a separate software revenue stream.
However, the 1.74 million includes prepaid purchasers as well as monthly subscribers. Recurring-revenue estimates that treat everyone as a monthly subscriber are therefore inaccurate. A high early take rate is not the same as customers still paying three or six months later.
The metrics to watch are paid retention, conversion of existing vehicle owners and actual revenue per customer, in addition to new sign-ups. The results of FSD, which requires driver supervision, should also not be treated as equivalent to the safety of unsupervised robotaxis.
4. Robotaxi will be decided by profit per vehicle, not vehicle count
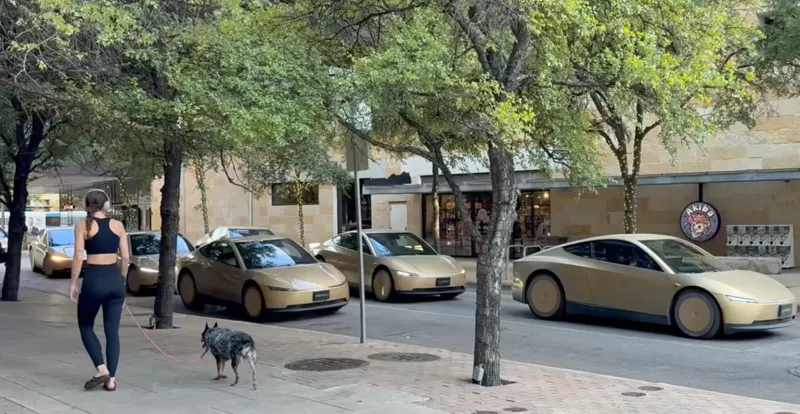
Tesla launched a robotaxi service using the Cybercab in Austin in September. Cumulative unsupervised miles rose about eightfold from the prior quarter. Fleet expansion is technical progress, but it is not immediate proof of commercial profitability.
To earn repeatable profit, robotaxi must raise paid operating hours while cutting the costs of empty repositioning, charging, cleaning, insurance, maintenance, remote support and vehicle depreciation.
Robotaxi unit economics: paid ride revenue per vehicle, minus total operating and support costs, minus insurance, maintenance and depreciation, equals economic profit per vehicle.
The cost of $0.30 per mile cited by management is not yet an achieved figure. If paid utilization is low or field operating costs are high, losses could widen as the fleet grows.
So more important than announcements of new cities is how paid usage per vehicle and fully loaded cost change in Austin, and whether those economics repeat in other cities.
5. Optimus and AI capacity: speed of commercialization over size of spending
Optimus has entered early production in Fremont. Having a production line is not the same as supplying useful robots in volume that customers will pay for.
The key investment metrics are hours of work done without human intervention, success rate on repeat tasks, mean time between failures, maintenance cost and the customer's labor savings. These need to improve for higher output to turn into economic value.
AI compute and semiconductor capacity are similar. When capacity actually comes online, and its performance per dollar, matter more than planned capacity or power. Bigger AI spending is not in itself enough for growth.
6. Annual capex cut from more than $25 billion to about $20 billion: what it means
Tesla lowered its full-year capital expenditure outlook from more than $25 billion to about $20 billion. Yet capex in the quarter itself rose 110% from a year earlier. Reading this as a halt to AI investment is wrong.
| Possible explanation | Meaning | Evidence to check |
|---|---|---|
| Better build efficiency | Same capability with less capital | Utilization, cost and schedule held |
| Spending deferred | Cash flow gain may be temporary | Higher capex next quarter or next year |
| Supply chain or technology bottlenecks | Possible delay in commercializing growth businesses | Changes to production or service targets |
The important question is not how much the spending fell, but how much capital it took to secure useful capacity on the planned date.
A possible merger with SpaceX should be examined separately as a capital allocation issue. Reuters reported the two companies are discussing a combination. But terms, exchange ratio and funding burden are not settled, so this FCF should not be read as money already earmarked for a deal.
7. Can energy cushion the AI transition financially?
Energy storage deployments were 13.7 GWh, up 10% from a year earlier, but energy revenue fell 16% to $2.881 billion. The 33.1% energy gross margin was also affected by tariff refunds and warranty cost adjustments, so it is hard to extend as normal profitability.
Still, growing data center power demand could underpin long-term Megapack demand. The Texas Megapack factory has started production, with planned annual capacity of 50 GWh. If actual shipments and a normalized gross margin rise together, the cash-generating base between autos and new AI businesses could thicken.
Insight Times Editorial Desk