Nvidia Sells the Chips, CoreWeave Rents Them: Why the Risks Differ

Both ride the AI boom, but one sells GPUs and the other rents them out. The way each makes money, and the risk each carries, is not the same.
1. Same AI boom, different bills

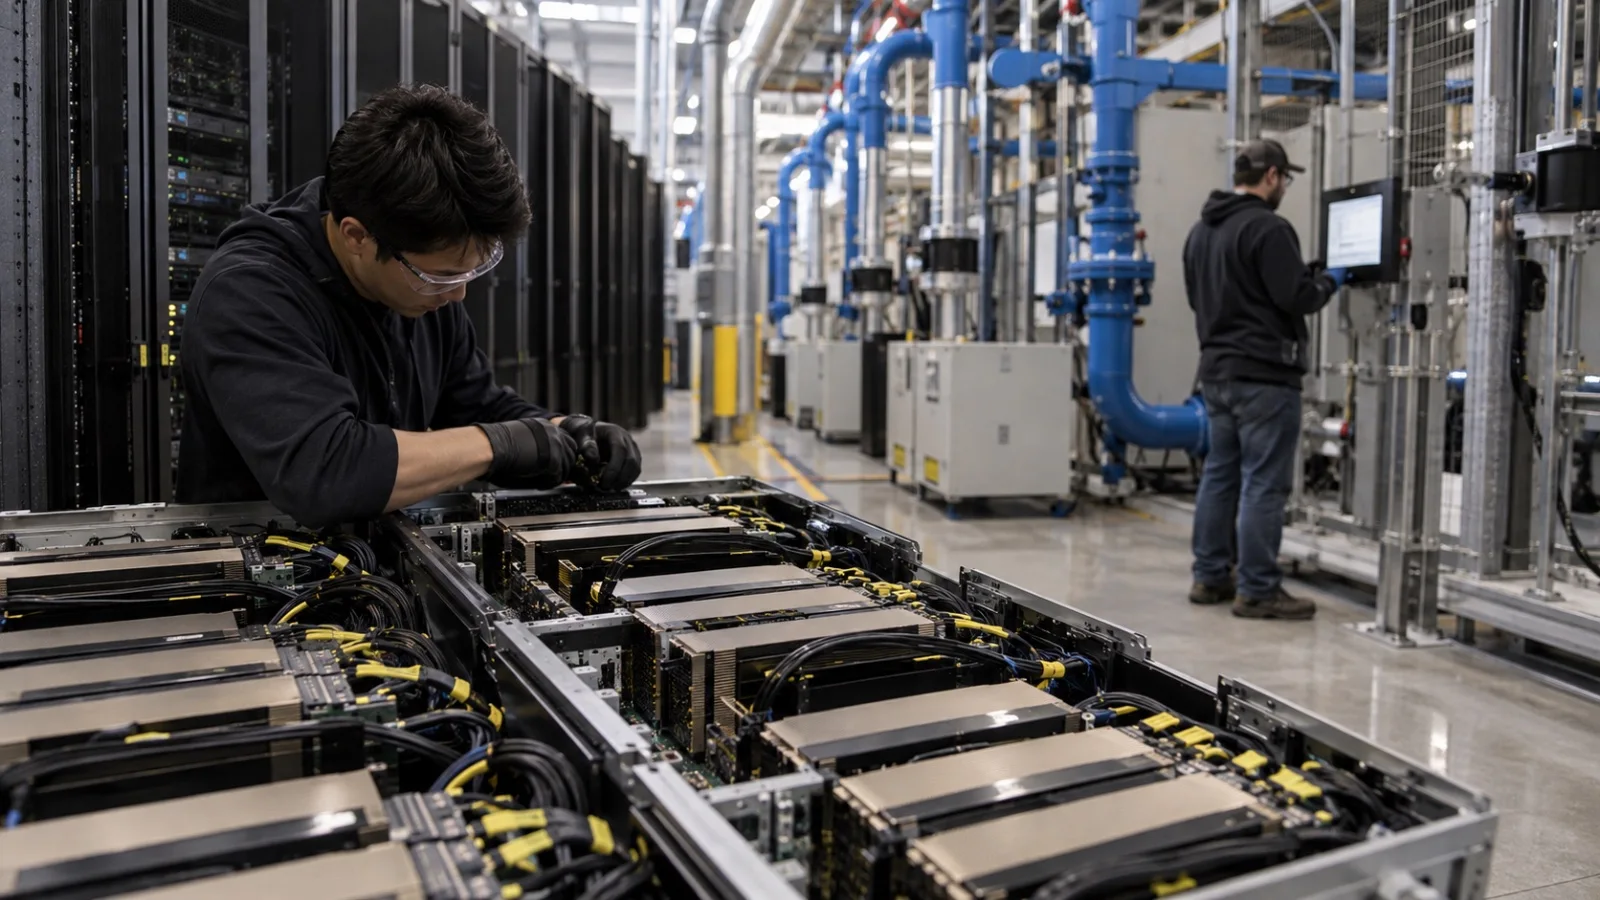
Picture a single AI data center being built.

One company sells the high-performance GPUs and networking systems that go inside. Another secures GPUs in bulk, adds power and cooling, and sells computing services to customers.

Both have a chance to grow revenue as AI demand rises. But there is a decisive difference.

A chip seller books revenue when it sells the product. An infrastructure operator invests in equipment first, then recovers that money by running it over several years.

Nvidia also has to spend on research and development and on its supply chain. CoreWeave can also gain visibility into future revenue through long-term contracts. Neither is automatically the better business.

The difference lies in the time it takes to recoup an investment and in the capital burden.

2. What do the results show side by side?

NvidiaCoreWeave
PeriodFiscal Q2 2027, ended July 26, 2026Q2 2026, ended June 30, 2026
Quarterly revenue$96.2 billion$2.575 billion
Year-over-year revenue growth+106%+112%
GAAP gross margin75.0%n/a
GAAP net lossn/a$626 million

Source: the companies' official earnings releases. Quarter-end dates and fiscal years differ, and gross margin and net loss are different measures, so this is not a direct ranking of profitability.

Of Nvidia's $96.2 billion in revenue, $89.0 billion came from its data center business. GAAP operating income was $63.7 billion.

CoreWeave also grew revenue, from $1.212 billion in the same quarter a year earlier to $2.575 billion. But it posted an operating loss of $49 million and a net loss of $626 million. Net interest expense alone was $640 million.

The notable point is that CoreWeave's revenue growth rate is about the same as Nvidia's.

On revenue growth alone, both are explosive growth companies. That does not mean the economics of that growth are the same.

3. Why revenue can double and cash can still run short

CoreWeave's business is cloud infrastructure that provides high-performance computing capacity to customers.

As customers grow, it needs more than GPUs. It also needs servers, networking, power equipment and data center space. It spends the money first and collects usage fees over the contract term.

In the first half of 2026, CoreWeave generated about $3.663 billion in cash from operations. Investing activities, however, drew out about $14.874 billion, while financing activities brought in about $13.985 billion.

Where did CoreWeave's cash move? First-half 2026 cumulative cash flow (rounded)

  • Operating activities: +$3.663 billion
  • Investing activities: -$14.874 billion
  • Financing activities: +$13.985 billion

These are the three categories in the cash flow statement. The full investing outflow should not be read as capital spending alone, and the full financing inflow should not be read as new borrowing alone.

The numbers show how much capital CoreWeave's growth strategy requires.

Borrowing itself is not a flaw. If cash from long-term contracts comfortably covers financing costs and principal, debt can speed up growth.

The reverse is also true. If GPU utilization falls short of expectations or equipment rental prices drop, capital already spent and interest costs could squeeze profitability.

4. Is CoreWeave's $104 billion backlog a safety net?

CoreWeave reported a revenue backlog of about $104 billion at the end of June 2026.

That is more than 40 times quarterly revenue, a positive sign for visibility into future customer revenue.

But a backlog is neither net income nor cash in the bank.

To serve customers, CoreWeave must finish data centers, supply power and run the GPUs. The time when contract revenue is recognized can also differ from the time cash arrives.

So a backlog shows visibility into future revenue. It does not prove profitability or that the investment will be recovered.

5. Is Nvidia free of risk?

No.

Nvidia posts a high gross margin and strong operating income, but it depends heavily on customers' AI capital spending.

If cloud companies or AI infrastructure operators cut investment plans, GPU orders and pricing power could be affected. Rivals' in-house AI chips, product transitions and export controls are also long-term risks.

There is one more important distinction.

A good company and a good stock are not the same thing.

Even if Nvidia's growth and margins are outstanding, investors could see low returns if the share price already reflects very high future earnings.

Conversely, if CoreWeave raises utilization, eases its financing burden and improves free cash flow, the way the market values it could change.

A company with strong current results does not always deliver higher stock returns.

Revenue growth is similar, but a company that sells chips and one that builds and rents capacity differ in how fast they recoup investment and how much debt they carry.

Insight Times Editorial Desk

More by topic

Starting with this story's topics, then what readers are following now

Investor psychology, decision-making and books on investing

GPU

This story's topic59 storiesSee all →

A chip built to draw graphics, whose ability to run thousands of identical cal…

US AI Data Centers Are Headed for 90GW. Gigawatts Now Matter More Than Dollars

Goldman Sachs expects US data center capacity to grow from 64GW at the end of 2026 to 90GW at the end of 2027. The AI race is moving from buying GPUs to building power plants and transmission lines alongside them.

Tech

Why Nvidia Is Happy to Help Make AI Models Nearly Free

Falling model prices can squeeze model makers. For Nvidia, the number that matters is the total volume of tokens generated worldwide and the compute that produces them.

Tech

Amazon Goes After Nvidia's Strongest Moat, and It Is Software, Not GPUs

Amazon's open-source TorchNeuron aims to let existing AI code run on its Trainium chips. The contest comes down to the total cost of AI compute and the return on Amazon's $220 billion in annual capital spending.

Tech

Nvidia's Next Target After GPUs: Controlling What AI Agents Are Allowed to Do

OpenShell and Sentry are not about policing what an AI says. They are about controlling, at the server infrastructure level, which files and APIs an AI can touch, what it can execute, and who can actually pull the plug when something goes wrong.

Tech

The US-China Summit Didn't Erase Taiwan Risk for Chip Stocks
Washington's Taiwan policy held, but roughly $14 billion in arms sales is still on hold. For AI chip investors, the summit reads less like risk removed and more like a fragile balance extended.

Macro

2027 Investing Needs Alignment, Not Prediction

A new investing book argues the hard part was never picking the next winner. It's staying aligned with where value and bottlenecks are moving while keeping old human weaknesses in check.

Investor Mind

AMD Crossed $1 Trillion, and the Market Started Looking at CPUs Again

AMD's stock topped a $1 trillion market cap for the first time. The rally isn't just about being an Nvidia alternative. It reflects a reassessment of AMD as a full-stack AI infrastructure vendor, one that bundles CPUs, GPUs and networking, as AI shifts from chatbots to agents and reignites data center demand for CPUs.</deck> <parameter name="oneline">As AI moves from chatbots to agents, the market has started counting the CPU sitting next to the GPU again.

Tech

HBM

74 storiesSee all →

Memory stacked next to the GPU.

Has Memory Peaked? Prices Are Cooling, but the Shortage Looks Set to Run to 2028

Price growth has slowed and consumer demand is already breaking. Server and HBM supply remains short, and Micron says more than 75% of its 2027 volume is already committed to customers.

Tech

AI Chip Peak Check: Demand Still Rising, Risk Building in 2027-2029 Supply and Funding

DRAM and NAND contract prices are still climbing and HBM suppliers hold the edge. Power shortages, AI financing costs and simultaneous memory expansion are the risks for later years.

Investing

AI Chips Haven't Peaked. The Real Risk Sits in 2028 Supply

HBM and server DRAM shortages are now spreading into enterprise SSDs. The question isn't today's strength, it's how much new capacity these prices are pulling in and when it lands.

Investing

Memory Chip Supercycle: Not at Peak Yet, But 5 of 6 Warning Signs Are Flashing

Memory prices are still climbing, but the pace is slowing and PC and smartphone demand is starting to crack under the weight of higher chip costs. This looks less like a price peak and more like a profit plateau building toward the next supply cycle.

Investing

2027 Isn't the End: Citi's Case for a Memory Supercycle Running to 2031

Citi says the memory shortage timeline is stretching again. If AI shifts from "train once" models to continual learning, HBM, server DRAM and enterprise SSDs could all fall short at the same time.

Tech

How Far Can China Push DRAM Without EUV

CXMT says it has shrunk DRAM features to 11.95nm using quadruple patterning instead of EUV lithography. The real question is not whether China caught up, but how much more it now costs China to get there.

Tech

Samsung, SK Hynix Sold Off on AI Fears. The Orders Haven't Followed Yet

The selloff reflects a market recalculating AI capex speed and memory earnings expectations, not confirmed cancellations. So far, the data show a gap between fear and reality.

Investing

A building that houses servers and networking gear and supplies them with powe…

Tesla Energy's 13.7GWh Paradox: Expectations Ran Faster Than Deployments

Q2 deployments recovered but margins collapsed. Q3 set a record for deployments and still missed estimates. The issue is not the size of AI power demand but how fast it converts into Tesla revenue and profit.

Tech

Why the White House Swapped "AI" for "Super Intelligence"

Executive Order 14434 renames AI across the federal government without defining a new technology. The real story is about roughly $700 billion in capex, free cash flow and electricity.

Tech

Nvidia Put $2 Billion Into Lumentum. Optics May Be the Next Bottleneck, but the Stock Has Already Run

Optical networking is emerging as the next constraint on AI data centers. Investors need to separate the industry's growth potential from the price they are already paying for it.

Tech

Nvidia's $500 Billion Experiment: Wall Street Asks Who Backs the GPU, Not Just the Chip

The real issue in Nvidia's financing platform is not chip sales. It is how far Wall Street will trust GPU resale prices and rental income three to four years out.

Tech

AI Data Centers' Next Bottleneck: Getting Power From the Grid to the GPU

Securing a gigawatt of power does not mean a gigawatt reaches GPU compute. The next fight in AI infrastructure is happening inside the data center, over how little electricity gets wasted before it reaches the chip.

Tech

The AI Bubble Question Has Changed: By Late 2026, It's ROIC Over GPUs

There is no sign yet that AI investment is slowing. If anything, hyperscaler spending forecasts keep climbing. But as the scale of that capital has grown, the market's question has shifted from "is AI growing" to "when, and how much, does this capital come back as cash."

Tech

The Question Markets Asked This Week: Who Controls the AI Bottleneck, Not Who Owns AI

The Fed hiked again and the 10-year topped 5 percent, but the center of the AI trade held. The market is no longer asking whether AI is growing, it is asking who controls memory, power and capital.

Tech

NVDA

83 storiesSee all →

ASML Is Discussing 2030 Orders. How Long Can the AI Chip Supercycle Last?

Despite bubble worries, ASML sees equipment shortages through 2028. Investors should watch future production capacity, not just today's orders.

Tech

AI's Next Bottleneck Is Money, Not Chips

Broadcom is lending Anthropic up to $42 billion, and Nvidia wants to build a $500 billion market for loans backed by GPUs. The AI race may turn on what rate buyers pay to borrow.

Tech

TSMC's August number that matters is not 53%. It is September's threshold

TSMC posted its first month above NT$500 billion. The useful reading is not the growth rate but what September revenue has to be to hit the top of third-quarter guidance, and whether AI demand is still alive on the factory floor.

Tech

The Cheaper Tokens Get, the Bigger Your AI Bill Gets

As AI shifts from training to inference, the token is becoming an industrial commodity. Falling prices are not cutting demand, because agents and automation consume tokens at a scale no human chat session ever did.

Investing

What Jensen Huang sold at the G20 was not GPUs. It was national infrastructure

Nvidia's message is that AI should be laid down like electricity, roads and the internet. After the hyperscalers, the buyers are governments, telcos, regional clouds and industrial data centers.

Tech

Before Robots Sell, Chips Sell First: Following the Money in the Humanoid Race

Billions of dollars are moving before humanoid robots reach mass sales. Compute suppliers may see revenue first, but that does not guarantee stock returns.

Tech

Why Nebius Is Keeping Some 2027 AI Capacity Off the Shelf

Nebius mixes long-term contracts, short-term premiums and auctions. Holding back capacity pays only if the servers stay busy, and it is not yet clear the pricing will last.

Tech