SpaceX Forecast at About $730 Billion in 2028 Revenue: The Bigger Opportunity Musk Sees
Sequoia Capital made a bold forecast, and Elon Musk replied, "I think we can do better." The future SpaceX is looking at is far bigger than the rocket launch business. The plan is to link satellite communications, AI data centers and orbital computing into one giant business.
The 20-second read
How can a company that builds rockets grow into a giant infrastructure company for the AI era?
The 20-second briefing
- About $730 billion in 2028 revenue. The growth outlook for SpaceX laid out by Sequoia's Shaun Maguire.
- The cost advantage Starship creates. Its ability to carry huge loads is the key technology changing the economics of satellite communications and AI infrastructure.
- Musk's next market is space. SpaceX's growth plan extends from AI data centers on the ground to orbital computing.
1. Why did Musk say "we can do better"?
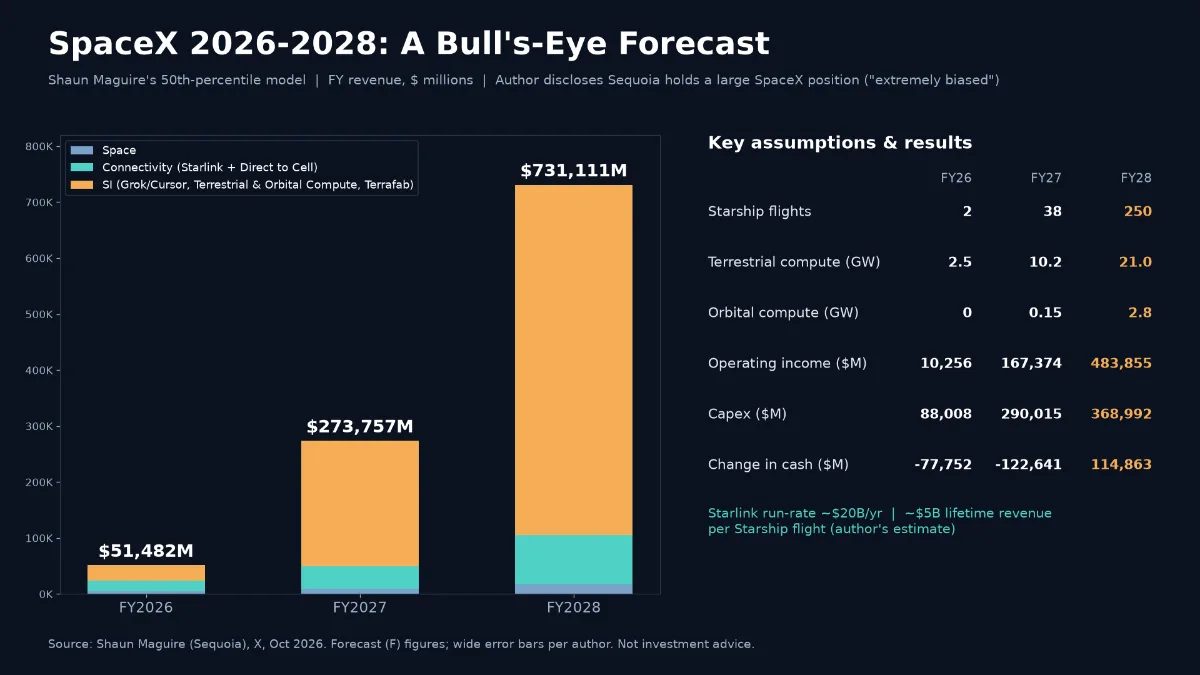
Shaun Maguire's 2028 revenue forecast for SpaceX is $731.111 billion, a huge number of roughly $730 billion.
Maguire compared this pace of growth to the explosive revenue growth Nvidia has shown over the past three years.
What stands out is the reply Musk himself left on Maguire's post.
"I think we can do better."
Musk is looking at an even bigger future than the growth scenario Maguire drew.
SpaceX's business already goes well beyond rocket launches.
Starlink provides satellite internet service, and Direct to Cell targets the market for connecting ordinary mobile phones directly to satellites. On top of that, a large-scale AI computing business is being added.
A company that started with rockets is evolving into one that spans communications and AI infrastructure.
To understand SpaceX's growth potential, look at the new markets its rockets create rather than at rocket revenue.
2. SpaceX's real edge is its people and execution
What Maguire values most is not SpaceX's rocket technology but its organizational culture.
Rockets either fly or explode. The result is clear. When something fails, the team finds the cause, fixes the design and tests again.
Maguire calls this "a culture where physics beats politics."
What matters is actually solving the problem, not explaining the failure.
The way SpaceX solves problems, as he describes it, is striking.
If turbines are in short supply, it builds them itself. If a power plant permit is blocked, it runs a power plant in another region and connects the transmission lines.
That organizational strength can pay off in the AI data center business as well.
An AI data center is not finished just by securing Nvidia chips. It needs enormous amounts of power, cooling to handle the heat and high-speed networks.
It is a massive construction project in which a vast amount of equipment and infrastructure has to come together at the same time.
What it takes is technical skill plus the ability to solve complex problems quickly.
SpaceX has built up exactly that ability while developing rockets.
In the AI infrastructure race, the ability to get chips running quickly matters as much as the ability to secure good chips.
3. What Starship changes is not the price of a rocket
Starship is SpaceX's most powerful weapon.
Maguire rates Starship as one of the largest economic moats in history.
An economic moat is a competitive advantage that rivals cannot easily copy.
In his view, Starship's real edge is not the performance of a single rocket.
It is the ability to connect design, manufacturing, launch, recovery and satellite deployment into one system.
Transport efficiency deserves particular attention.
In Maguire's calculation, one Starship launch equals about 20 Falcon 9 launches.
That difference changes the economics of the satellite communications business.
Sending more satellites into space at once changes the cost of building and expanding a satellite network.
Starlink can serve wider areas, and Direct to Cell gains the chance to expand the market for connecting phones directly to satellites.
The service revenue each launch supports grows as well.
Go one step further, and it connects to a business of carrying AI computing equipment into space.
Starship, in other words, is not a product for selling rockets but a foundation technology that grows SpaceX's many businesses.
For rivals, catching up on rocket technology alone is not enough. They would also have to build the production system, launch operations and satellite network.
Starship's real value lies less in the price of a single rocket than in its ability to lower the cost of communications and AI infrastructure as a whole.
4. Can SpaceX also be cost-competitive in AI computing?
Another SpaceX strength in Maguire's eyes is a low cost of producing AI compute.
Put simply, AI computing is the business of providing the processing power needed to train and run AI models.
It takes huge numbers of chips and huge amounts of power, so the upfront cost is large.
Maguire compares this market to the oil industry.
When oil prices fall, the highest-cost producers struggle first. Producers with low costs, by contrast, gain the upper hand.
His view is that AI computing could develop along similar lines.
If SpaceX can build power and data centers faster and more cheaply than its rivals, it can secure a strong position even in a market where prices for AI compute services fall.
Low costs lead to price competitiveness, and price competitiveness becomes the basis for winning customers and gaining market share.
Add the organization's speed of execution.
If SpaceX gets its facilities running and lands customers while other companies are still solving power and construction problems, it can also pull ahead in recovering its investment.
That is why Maguire sees SpaceX not as just another AI data center operator but as a low-cost producer of AI compute.
In the AI compute market, the key edge is broadening from how many chips you own to how cheaply you can supply processing power.
5. The bigger market Musk sees is in space
AI data centers on the ground play a key role in Maguire's growth plan.
Musk, however, is looking further ahead.
His reply to a post that visualized Maguire's model is even more striking.
In effect, he said ground-based compute is a drop in the bucket next to orbital compute.
Musk expects the orbital computing capacity deployed each month to exceed that on the ground by around the end of 2028, with the gap widening sharply in 2029.
Starship again plays a central role in this plan.
Deploying AI computing equipment in space at scale requires the ability to haul enormous amounts of equipment and launch again and again.
The rocket technology and launch system SpaceX is already building become the foundation of its AI infrastructure business.
Maguire puts AI compute on the ground at the center of growth, while Musk points to the next stage: orbital computing.
Put the two views together, and the shape of SpaceX's future business becomes clearer.
AI processing power from data centers on the ground, orbital computing expanded with Starship, and Starlink's communications technology tying it together.
Rockets, communications and AI computing link up into a single industrial ecosystem.
The future SpaceX is preparing is expanding from sending rockets into space to turning space itself into new ground for AI infrastructure.
6. The key to huge growth is getting the money back
Investors' readings of Maguire's outlook kept coming.
SpaceX bull @spcxGOD argued that rapidly expanding AI computing facilities could sharply accelerate revenue growth.
@mikejt4, who visualized Maguire's financial outlook, highlighted another interesting shift.
By the end of 2028, AI computing would make up a far larger share of SpaceX's revenue than rocket launches.
The yardstick for valuing SpaceX is shifting from launch counts to the capacity and revenue of its AI infrastructure.
Meanwhile, @UnstructuredCap pointed to taxes and changes in working capital in Maguire's financial model.
Working capital is the money a company ties up in things like customer receivables and inventory while running its business.
The core of this debate is clear.
How much cash can a company with soaring revenue actually generate?
Maguire's 2028 capital spending forecast for SpaceX is about $370 billion.
That is an enormous investment.
The number reflects a business that has to build data centers, secure chips, and put in power and networks.
If this large-scale investment generates revenue quickly, and that revenue in turn funds the next round of investment, growth can accelerate even further.
And if SpaceX establishes itself as a low-cost producer, it will hold a strong position in price competition for compute services.
Packy McCormick of the newsletter Not Boring pushed back against critics who judge a huge future business only through overly detailed numbers.
The debate shows two different investment perspectives.
One focuses on the size of the market and the company's ability to execute. The other focuses on recovering investment and generating cash.
To understand SpaceX's long-term value, you need to look at both.
A growing company's strength comes from its ability to open new markets, and the durability of that growth comes from its ability to turn the money it earns into the next round of growth.
Shaun Maguire (@shaunmmaguire), "People don't understand SpaceX"
Elon Musk (@elonmusk), "I think we can do better", 2026-10-31 07:13 KST
Elon Musk (@elonmusk), reply on orbital computing, 2026-10-31 11:41 KST
Brian Wang (@nextbigfuture), launches needed for orbital computing
@spcxGOD, growth outlook for SpaceX's computing business
@mikejt4, visualization of SpaceX's financial outlook
@UnstructuredCap, critique on taxes and working capital
Packy McCormick (@packyM), rebuttal to critiques of the financial outlook
Insight Times, "A Third of SpaceX's Revenue Comes From Anthropic: The Customer Concentration Risk to Check Before 'AI Profits'", 2026-10-30
The way people look at SpaceX is changing.
In the past, how good a rocket it could build and how often it could launch were the key measures of its competitiveness.
Now the question has grown bigger.
How large an industry can SpaceX move with its rocket technology and its ability to execute?
If Starship lowers the cost of building satellite networks, Starlink and Direct to Cell can expand faster.
The ability to build power and data centers quickly turns into a cost advantage in the AI computing market.
Add orbital computing, and SpaceX can grow into an AI infrastructure company that spans the ground and space.
The heart of this structure is that each business strengthens the others.
Rocket technology lowers the cost of satellite communications, and satellite communications and the launch system support new space infrastructure businesses. The execution of an organization that builds large-scale facilities carries over to the AI computing business as well.
When these businesses connect inside one company, they create a structural advantage that rivals find hard to match.
It is an important shift for investors too.
The yardstick for SpaceX's long-term value is widening from rocket launch revenue to the growth and cash generation of its entire communications and AI computing infrastructure.
That makes it important to weigh the company's pace of growth together with the current share price.
Finding a good company and buying it at a good price are two different skills.
For long-term investors, the fitting approach is to keep watching how the company's competitiveness strengthens and how its actual results change, while spreading out position size and timing of purchases.
SpaceX's real edge starts with the technology to send rockets into space and lies in using that technology to change the cost structure of the communications and AI industries.
And the next stage Musk envisions is not Earth but space.
- The 2028 revenue forecast released by investor Shaun Maguire is $731.111 billion.
- That works out to about $730 billion. The article does not confirm whether this is official guidance issued by the company itself.
- Maguire's 2028 capital expenditure forecast is about $370 billion.
- That figure covers the money needed to build data centers, semiconductors, power and communications networks.
- By Maguire's calculation, one Starship launch equals about 20 Falcon 9 launches.
- Sending more satellites at once could change the cost of building a satellite network.
- It could also connect to the business of carrying AI computing equipment into space.
- It is the idea of placing AI computing equipment in orbit in space instead of on the ground.
- Musk projected that by around the end of 2028, the new orbital computing capacity deployed each month would exceed that on the ground.
- This is Musk's projection. Whether it will actually happen has not been confirmed.
- One side puts more weight on the size of the market and the ability to execute.
- The other side points to taxes and working capital and asks how much cash the business will actually generate.
- The article concludes that you need to consider both views together to gauge long-term value.
What to watch
Insight Times Editorial Desk
How we use AI
이 기사는 사람 편집자가 기획하고, 사람과 AI가 같이 초안을 쓰고 수정하고, 최종 사람 편집자가 사실과 표현을 확인해 발행했습니다. 수치와 인용은 본문에 적힌 자료에서 가져왔습니다.