Is This AI Memory Supercycle Really Different? The Valuation Trap for Long-Term Investors

Memory is reshaping around AI through 2030. But a good industry and a good entry price are separate questions.
The 20-second read

1
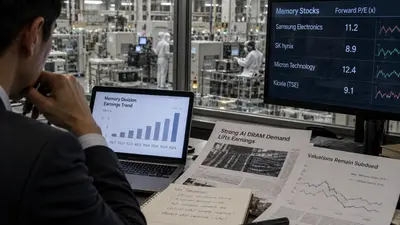
AI is changing the size of the memory market. WSTS raised its 2026 semiconductor market forecast from $975 billion to $1.51 trillion. Gartner expects memory revenue alone to reach $837.3 billion this year.
2
HBM growth also affects the supply of commodity DRAM. HBM and DDR5 compete for the same production resources. Limited capacity combined with a shift to higher-value products is creating supply constraints unlike those of the past.
3
A supercycle does not mean a permanent boom. Growth may continue beyond 2027, but once memory prices and margins normalize, a P/E that looked low could become a metric that hides investment risk.

1. What is different about this memory boom

The memory market used to track PC and smartphone sales. Makers added supply, prices fell, production cuts followed, and prices recovered.

AI data centers have changed the nature of demand. As GPU compute improves, high-bandwidth memory (HBM), which feeds data to the chip quickly, matters more. AI servers need not only HBM but also DDR5 and high-capacity NAND flash.

Gartner's August 2026 forecast has the memory market growing from $220.1 billion in 2025 to $837.3 billion in 2026 and $1.0755 trillion in 2027. That does not mean shipments are surging by the same amount. Rising selling prices explain a large share of the revenue growth.

Global memory revenue forecastRevenue
2025$220.1 billion
2026 (forecast)$837.3 billion
2027 (forecast)$1.0755 trillion

2. Why more HBM means tighter supply of commodity DRAM

HBM stacks several DRAM chips vertically and links them at very high speed. It takes more die area, more manufacturing steps and more packaging work than standard DRAM.

When a memory maker raises its HBM share, the same wafer input can yield fewer bits of commodity DRAM. This is known as the wafer penalty.

TrendForce cites this capacity race and delays in stabilizing yields on next-generation products in forecasting tight supply through 2027. It expects the average selling price of HBM to rise 121% in 2027 from a year earlier. That is a blended ASP forecast that includes a higher mix of expensive HBM4. It does not mean the price of the same product rises 121% across the board.

The structure favors memory makers but raises costs for PC and smartphone makers. If prices climb too far, those makers may cut memory capacity in consumer products, or buyers may delay upgrades.

3. Can SK hynix's 80% operating margin last?

SK hynix reported third-quarter 2026 revenue of 104.6155 trillion won and operating profit of 83.3338 trillion won. That is an operating margin of about 79.7%.

The company says it has secured long-term contracts for more than 50% of its 2027 to 2028 capacity. That may give better earnings visibility than in past cycles. It does not mean all future volumes and prices are fixed.

CompanyStrengthsRisk for investors to check
SK hynixHBM lead, packaging technology, customer tiesDurability of high profitability
Samsung ElectronicsDRAM production base, foundry, integrated packagingHBM yields, customer qualification, profitability
MicronLeading-edge DRAM, data-center-focused product strategyReturn on large capacity expansion

For US investors, Micron (MU) is the main way to own the memory cycle directly. But a US listing alone does not justify a higher valuation than its rivals.

Micron reported fiscal fourth-quarter 2026 revenue of $54.23 billion. Fiscal third-quarter revenue was $41.46 billion. Investors should not confuse the company's fiscal quarters with calendar quarters.

4. What may change from 2027 to 2030

Competition is widening from HBM volume to next-generation HBM4 yields, base-die design and advanced packaging capacity.

In 2029 to 2030, CXL-based memory expansion and sharing, and research into next-generation 3D DRAM, could become important variables. The CXL 4.0 specification was released in 2025 and raises transfer speed to 128 GT/s. A published spec is not the same as large-scale commercial adoption.

If memory pooling spreads, servers can share memory more efficiently. That could create new demand for server memory. It could also reduce duplicate purchases of existing memory.

5. Long-term valuation turns on normalized earnings, not peak earnings

When a high operating margin and a low forward P/E show up together, one question comes first.

Can today's earnings hold in 2030?

Say the share price is 100 and EPS is 20. The P/E is 5x. If memory prices normalize and EPS falls to 10, the P/E becomes 10x at the same share price.

A low P/E can signal undervaluation. It can also mean the market expects earnings to fall.

Hypothetical 2030 scenarioEPSP/E appliedImplied price
Bull258x200
Base157x105
Bear86x48

Assumes a current share price of 100 and current EPS of 20. This is an illustrative model, not a price target, probability or return forecast for any company. Dividends excluded.

Monte Carlo simulations also depend on the assumptions for volatility and expected return. One source cited a 10,000-run simulation with a probability of gains, but it gave no input parameters or result distribution, so the figure cannot be verified.

Feeding a model the assumption that the industry is safer than before, then getting a high probability of gains, does not mathematically prove that industry risk has fallen.

FAQ

Q. If AI keeps growing, will memory prices keep rising?

  • Wider AI adoption is positive for demand, but capacity additions and efficiency technologies can restrain price gains.
  • Rising demand and continuously rising prices are different things.

Q. Do long-term contracts end memory downturns?

  • Contracts improve volume visibility. They do not remove the risk of price adjustments, customers cutting investment or changes in contract terms.

Q. If you hold to 2030, is today's low P/E enough?

  • Estimate normalized EPS that can hold across several industry conditions, not peak-cycle EPS.
  • Also weigh future capital spending, free cash flow and changes in share count.

In short, memory in the AI era is becoming a bigger and more technically complex market. But a good industry does not always come with a good price. Believing in the supercycle is one thing. What you pay for its earnings is another.

How is this memory boom different from past ones?
  • In the past, PC and smartphone sales drove the memory market.
  • This time, AI data centers are lifting demand for HBM, DDR5 and high-capacity NAND together.
Why does more HBM lead to a shortage of commodity DRAM?
  • HBM takes up more chip area and puts a heavier burden on processing and packaging than standard DRAM.
  • If manufacturers raise their HBM share, the supply of commodity DRAM made from the same wafers can shrink. This is called the wafer penalty.
What does TrendForce's forecast of a 121% rise in HBM prices mean?
  • It is a forecast that the average selling price of HBM in 2027 will be 121% higher than the year before.
  • The figure also reflects a growing share of high-priced HBM4. It does not mean the price of the same product will rise 121% across the board.
Does SK hynix's long-term contracts mean there is no need to worry about a downturn?
  • That is hard to say. The company said it has secured more than 50% of its 2027 to 2028 capacity through long-term contracts.
  • However, that does not mean all future volumes and selling prices are fixed. The risk of price adjustments or changes in contract terms remains.
Can a memory stock with a low P/E be considered cheap?
  • Not necessarily. A low P/E can be a sign of undervaluation.
  • It can also be low because the market expects earnings to fall. The key question is whether today's earnings will still hold in 2030.

What to watch

HBM blended ASP and prices by productDistinguish the effect of a larger share of high-priced products from actual price increases.
DRAM bit supply growthThe balance between HBM expansion and commodity DRAM supply.
HBM4 yield and packaging capacityHow quickly orders turn into actual revenue and profit.
Capex vs. FCFHow much of the cash generated in the boom is left for shareholders.
Return on AI data center investmentWhether end customers can keep absorbing memory price increases.
Memory being a good industry does not make today's share prices a good price.

Insight Times Editorial Desk
More by topic

Starting with this story's topics, then what readers are following now

Investor psychology, decision-making and books on investing

HBM

This story's topic78 storiesSee all →

Memory stacked next to the GPU.

Memory Is Still Short, but Less Short: Checking for the Peak This Week

Citi trimmed its 2027 DRAM and NAND shortage forecasts together. Server pricing remains strong, while consumer markets show weakness. This week's numbers show where the memory boom may peak.

Investing

A 3x P/E is not a discount. It is a verdict on how long memory profits last

Nomura's buy case on Samsung Electronics and SK Hynix does not stop at higher memory prices. It argues that if AI has turned memory from a cyclical component into strategic infrastructure, the formula the market uses to value both companies has to change too.

Investing

AI ran out of memory before it ran out of GPUs

The HBM bottleneck is spreading into DRAM prices, server costs and the price of the next laptop or phone.

Tech

2027 Isn't the End: Citi's Case for a Memory Supercycle Running to 2031

Citi says the memory shortage timeline is stretching again. If AI shifts from "train once" models to continual learning, HBM, server DRAM and enterprise SSDs could all fall short at the same time.

Tech

Has Memory Peaked? Prices Are Cooling, but the Shortage Looks Set to Run to 2028

Price growth has slowed and consumer demand is already breaking. Server and HBM supply remains short, and Micron says more than 75% of its 2027 volume is already committed to customers.

Tech

AI Chip Peak Check: Demand Still Rising, Risk Building in 2027-2029 Supply and Funding
DRAM and NAND contract prices are still climbing and HBM suppliers hold the edge. Power shortages, AI financing costs and simultaneous memory expansion are the risks for later years.

Investing

The Real ASML Number Isn't the 3% Pop, It's the 30% Capacity Hike

ASML's rally isn't just an AI trade. Customers are already locking in 2027 tool slots, and ASML is raising Low-NA EUV capacity by roughly 30% to keep up.

Investing

Valuation

This story's topic38 storiesSee all →

Measuring where a share price sits relative to the company’s results.

Marvell's $115 Billion Lumentum Deal: Is AI's Next Bottleneck Light, Not Chips?

Marvell's purchase of Lumentum points to a contest beyond GPU speed, in data transfer and power efficiency. Whether the price is right is not yet confirmed.

Tech

The S&P 500 Looks Fine. So Why Do Most Stocks Hurt?

The index sits near its high, yet most of its members are down 20% to 30% or more from their own peaks. A look at the "stealth bear market" and the numbers long-term investors should watch.

Investing

Year Five of the Bull Market: Why U.S. Stocks Aren't Expensive Yet, and What AI Chips and Power Must Deliver

U.S. stocks have gained about 117% since the October 2022 low. What happens next depends less on the bull market's age than on whether expected earnings, which lean heavily on AI semiconductors, turn into reality.

Investing

Anthropic's IPO: The Number That Matters More Than $100 Billion Is $2 Trillion

Claude-maker Anthropic is growing at a stunning pace, but the real question for investors is not how fast, only how long, and how much cash is left after GPUs and data centers.

Tech

Why a Wobbly Yen Carry Trade Hits US AI Stocks First

It is not just dollar-yen at 160. Watch the US-Japan rate gap, yen direction, volatility, and US long-term rates together, because AI and high-valuation growth stocks get squeezed first when all four move at once.

Macro

Apple and Palantir Beat Estimates, but Two Questions Remain

Apple has to show how much of its revenue turns into profit. Palantir has to show how long its explosive growth can last.

Investing

Editorial chart cover: illustrative 18-year growth of one SpaceX (SPCX) share in a Trump account, comparing 7% vs 10% returns and 5-20% share growth scenarios.

Why Musk wants to give 72 million US children a share of SpaceX

Elon Musk says he will gift one SpaceX share to every American child. The plan is not yet detailed, and the bigger driver of a child's wealth may be 18 years of steady saving.

Investing

A building that houses servers and networking gear and supplies them with powe…

Why Nebius Is Keeping Some 2027 AI Capacity Off the Shelf

Nebius mixes long-term contracts, short-term premiums and auctions. Holding back capacity pays only if the servers stay busy, and it is not yet clear the pricing will last.

Tech

Is Space Cooler for AI? Why Musk Wants Data Centers in Orbit

The next limit on AI may be power and cooling, not GPUs. Elon Musk is looking to Earth orbit for an answer, but the test is cost per hour of compute.

Tech

White House Swaps AI for "SI." The Real Investment Signal Is Infrastructure, Not the Name

An executive order renames artificial intelligence "Super Intelligence" and six frontier labs sign a voluntary safety accord. What investors should watch is the data center, power, nuclear and chip policy now gathered under one national-competitiveness frame.

Tech

Musk Sees the Next Phase of AI Infrastructure: Who Can Switch GPUs On, Fast

If neoclouds struggle under financial pressure, AI demand may not shrink. It may simply favor the few operators with the capital and execution to serve it, a shift that could matter for SpaceX and Tesla.

Tech

Weekly Check: The AI Bull Market Isn't Over, It's Just Gotten Harder

A 5% 10-year yield, 470 gigawatts stacked up in Texas, Chinese DRAM, and whether data centers actually get switched on are starting to decide who wins the AI trade through 2027.

Tech

Is Memory Peaking? In the AI Era, Watch the Bottleneck, Not the Demand

Demand still outruns supply. But memory stocks can peak before demand does. The real question is how long HBM4, server DRAM, CXL and Big Tech capex keep the cash flowing.

Tech

Nvidia and Palantir Put AI Inside the Supply Chain - The Real Shift Is That It's Learning Judgment

A single Vera Rubin rack holds 1.3 million parts. The real breakthrough in Nvidia and Palantir's new supply chain AI isn't automating that complexity, it's capturing the judgment calls that used to live only in planners' heads.

Tech

NVDA

101 storiesSee all →

Who Hits $1 Trillion Next: Reading AMD and ASML by Different Rules

One company is chasing Nvidia's GPU empire. The other sells the machine that draws the chips for every advanced chipmaker, including Nvidia. Both get floated as 2028 trillion-dollar candidates, but the numbers investors need to watch are entirely different.

Investing

Box Shows AI Its Manuals, and the AI Starts Redesigning the Workflow

Box Architect, built with NVIDIA, moves AI from reading documents to designing how work gets done. It has not yet reached beta, so the real-world payoff remains to be seen.

Tech

Tech Selloff: Is the Bull Market Over? Wall Street's Four-Year Chart Says Not Yet

The uptrend has survived five double-digit pullbacks in four years. This time, AI companies' debt and cash flow are the new variables.

Investing

If You Only Watch Tesla, You May Be Missing Half the AI Story

Nvidia builds the AI brain. Who supplies the electricity to run it? Six power companies Tesla investors should know, and why Tesla's storage business is just one link in the chain.

Investing

Nvidia Moves From GPUs to CPUs as AI Agents Reshape a $200 Billion Chip Market

A customer's early test found Nvidia's Vera CPU handled about twice the AI agent workload of its existing chips. The bigger story is where the money in semiconductors is heading as AI shifts from answering questions to doing work.

Tech

Nvidia's $500 Billion Experiment: Wall Street Asks Who Backs the GPU, Not Just the Chip

The real issue in Nvidia's financing platform is not chip sales. It is how far Wall Street will trust GPU resale prices and rental income three to four years out.

Tech

China's AI Labs Went Open Source Because They Had to, Not Because They Wanted To

A GPU shortfall pushed Chinese AI labs toward efficiency and open weights, and that constraint is now reshaping the global competition over who controls AI's basic infrastructure.

Tech